
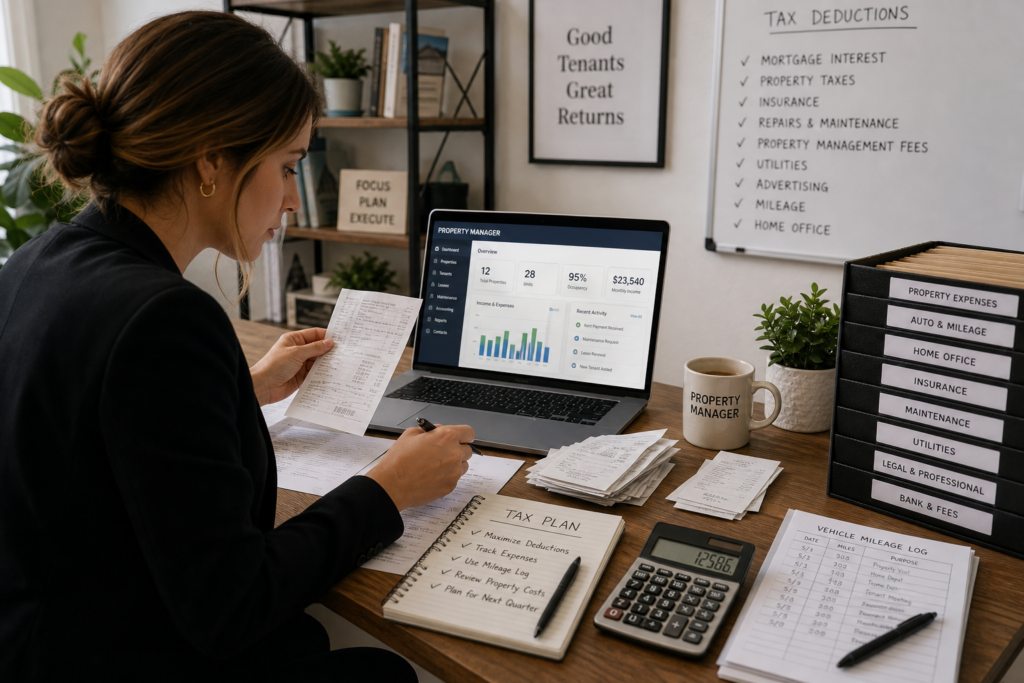
Property Manager Deductions to Maximize for Clients in 2026
For the 2026 tax year, property managers have unprecedented opportunities to reduce tax liability for their clients. Recent legislative changes under the One Big Beautiful Bill Act (OBBBA) have restored immediate expensing for research and development costs and reinstated 100% bonus depreciation. Property managers who act before the July 6, 2026 amendment deadline can recover significant deductions from prior years. This guide outlines the essential property manager deductions to maximize for clients, including repairs, depreciation strategies, technology expenses, vehicle costs, and home office allocations that deliver measurable tax savings.
Table of Contents
- Key Takeaways
- What Are the Most Overlooked Deductions for Property Managers?
- How Does the July 6, 2026 Amendment Deadline Affect Property Managers?
- What Repair and Maintenance Expenses Qualify for Immediate Deduction?
- How Can Property Managers Maximize Depreciation Strategies?
- What Vehicle Expenses Can Property Managers Deduct?
- What Technology and Software Deductions Can Property Managers Claim?
- How Should Property Managers Allocate Home Office Expenses?
- Uncle Kam in Action: Multi-Property Manager Recovers $127,000
- Next Steps
- Frequently Asked Questions
- Related Resources
Key Takeaways
- The July 6, 2026 deadline allows retroactive R&D deduction recovery for 2022-2024 tax years.
- 100% bonus depreciation was restored for qualifying property under the OBBBA Act in 2026.
- Property managers can deduct up to $1 million under Section 179 for equipment purchases.
- Strategic repair classifications save thousands compared to capitalized improvement categorizations.
- Home office deductions using actual expense method maximize savings for qualifying property managers.
What Are the Most Overlooked Deductions for Property Managers?
Quick Answer: Most property managers miss deductions for continuing education, professional licenses, industry association dues, marketing costs, and small tool purchases. These expenses add up to thousands annually.
Property managers frequently focus on major expenses while missing smaller, recurring deductions that compound significantly. Strategic tax planning identifies these gaps early in the year. For the 2026 tax year, understanding which expenses qualify as ordinary and necessary business costs separates effective property manager deductions from missed opportunities.
Professional Development and Education Expenses
Continuing education costs directly related to property management are fully deductible. This includes real estate license renewals, property management certifications, and specialized training courses. According to IRS Publication 535, education expenses that maintain or improve skills required in your current trade are deductible.
In 2026, property managers can deduct expenses for online courses, industry conferences, and certification programs. Travel expenses to educational events, including airfare, lodging, and 50% of meals, qualify as deductions. The key requirement is that education maintains current skills rather than qualifying you for a new profession.
Marketing and Client Acquisition Costs
Marketing expenses represent a significant deduction opportunity. Property managers can deduct costs for website development, online advertising, professional photography of properties, and printed marketing materials. For 2026, digital marketing campaigns through Google Ads or social media platforms are fully deductible business expenses.
Client entertainment expenses changed significantly in recent years. While meals with clients are 50% deductible, traditional entertainment costs generally do not qualify. However, promotional activities and networking events for prospective clients remain deductible marketing expenses.
Professional Services and Insurance Premiums
Property managers can deduct professional liability insurance, errors and omissions coverage, and general business insurance premiums. Legal and accounting fees for business purposes are fully deductible. This includes costs for tax advisory services, contract reviews, and compliance consultations.
Pro Tip: Document all professional development expenses with receipts and maintain a log showing how education relates to current property management activities. The IRS requires clear business purpose documentation for audit protection.
How Does the July 6, 2026 Amendment Deadline Affect Property Managers?
Quick Answer: The July 6, 2026 deadline allows property managers to amend 2022-2024 returns and claim immediate expensing for previously capitalized R&D costs. Missing this deadline forfeits potentially thousands in refund opportunities.
The One Big Beautiful Bill Act, signed July 4, 2025, created a one-year window for businesses to recover research and development deductions. Property managers who invested in process improvements, technology systems, or operational innovations between 2022 and 2024 can now amend returns to claim immediate expensing. According to Accounting Today, this deadline marks the final opportunity for retroactive deduction recovery.
What Qualifies as R&D for Property Managers
Research and development for property managers extends beyond traditional scientific research. Qualifying activities include developing custom software solutions, creating automated tenant screening systems, implementing new maintenance tracking processes, and designing innovative client communication platforms. The IRS defines R&D as activities that create new or improved processes through systematic experimentation.
For 2026, property managers who developed proprietary systems or significantly improved operational workflows may qualify. Examples include building custom CRM integrations, automating rent collection processes, or creating unique property inspection methodologies. The key test is whether the activity involved uncertainty requiring experimentation to resolve.
The Amendment Process Before July 6, 2026
Property managers must file Form 1040-X for individual returns or Form 1120-X for corporate returns to claim retroactive deductions. The amendment requires identifying previously capitalized R&D expenses and recalculating tax liability with immediate expensing applied. This process can generate substantial cash refunds from the IRS.
Timely filers who submitted 2022 returns by April 15, 2023 had until that corresponding 2026 date to amend. However, extension filers have until July 6, 2026 to file amended returns. Working with real estate tax specialists ensures proper classification and maximum deduction recovery.
State Conformity Considerations
Not all states conform to federal R&D expensing rules. California, Delaware, Maryland, New York, Pennsylvania, Rhode Island, Virginia, and the District of Columbia have decoupled to varying degrees. Property managers operating in these jurisdictions must file separate state amendments and may face different deduction treatment. Michigan specifically does not follow the OBBBA on bonus depreciation or R&D expensing.
Pro Tip: Gather documentation for all 2022-2024 technology implementations, process improvements, and system developments before July 6, 2026. Even small innovation projects may qualify for substantial retroactive deductions under R&D rules.
What Repair and Maintenance Expenses Qualify for Immediate Deduction?
Quick Answer: Repairs that restore property to original condition are immediately deductible. Improvements that add value or extend useful life must be capitalized. Proper classification can shift $50,000+ expenses from multi-year depreciation to immediate write-offs.
The distinction between repairs and improvements represents one of the most significant tax planning opportunities for property managers. The IRS Publication 527 provides detailed guidance on residential rental property repairs versus improvements. For 2026, understanding this classification determines whether expenses generate immediate tax savings or spread over decades.
Immediate Repair Deductions
Repairs that keep property in good operating condition qualify for immediate deduction. These expenses maintain current functionality without bettering or restoring the property. Common deductible repairs include:
- Repainting interior or exterior surfaces
- Fixing plumbing leaks and replacing broken fixtures
- Replacing damaged roof shingles or sections
- Repairing broken windows or damaged flooring sections
- Patching drywall and fixing electrical outlets
- HVAC system repairs and filter replacements
- Appliance repairs and minor component replacements
Capitalized Improvements Requiring Depreciation
Improvements must be capitalized and depreciated over time. These expenses add value, prolong useful life, or adapt property to new uses. Capitalized improvements include complete roof replacements, full HVAC system installations, room additions, kitchen remodels, and structural upgrades. These costs depreciate over 27.5 years for residential rental properties.
However, the 2026 restoration of 100% bonus depreciation under OBBBA allows immediate write-offs for qualifying property with recovery periods of 20 years or less. This creates planning opportunities for property managers to accelerate deductions through proper asset classification and cost segregation.
The Safe Harbor for Small Taxpayers
Property managers with total receipts under specified thresholds can elect the safe harbor for small taxpayers. This election allows immediate deduction of amounts paid for repairs, maintenance, and improvements up to the lesser of 2% of the property’s unadjusted basis or $10,000. The election applies per building and can significantly simplify record-keeping while maximizing deductions.
| Expense Type | Treatment | Tax Impact Example |
|---|---|---|
| Roof repair (10 shingles) | Immediate deduction | $2,500 expense = $2,500 year-one deduction |
| Complete roof replacement | Capitalized improvement | $25,000 expense = $909/year over 27.5 years |
| HVAC repair | Immediate deduction | $1,800 expense = $1,800 year-one deduction |
| New HVAC system | Capitalized (but 100% bonus may apply) | $12,000 expense = potential full 2026 deduction with bonus |
How Can Property Managers Maximize Depreciation Strategies?
Quick Answer: Cost segregation studies identify assets with shorter recovery periods. Combined with 100% bonus depreciation restored in 2026, property managers can accelerate $100,000+ in deductions from 27.5-year schedules to immediate write-offs.
Depreciation represents the largest tax deduction for most property managers and their clients. The One Big Beautiful Bill Act’s restoration of 100% bonus depreciation for 2026 creates exceptional planning opportunities. Understanding depreciation strategies allows property managers to deliver substantial tax savings to clients while maintaining compliance with IRS Publication 946 depreciation rules.
Cost Segregation for Accelerated Depreciation
Cost segregation studies reclassify building components into shorter recovery periods. While building structures depreciate over 27.5 years for residential rentals, many components qualify for 5, 7, or 15-year recovery periods. These include carpeting, appliances, lighting fixtures, landscaping, and parking lot improvements. A typical $500,000 rental property might have $150,000 in assets eligible for accelerated depreciation.
For 2026, combining cost segregation with restored 100% bonus depreciation delivers immediate write-offs for qualifying components. Property managers can apply this strategy to recently purchased properties or conduct look-back studies on properties acquired in prior years. The immediate tax savings often justify the $5,000 to $15,000 cost segregation study fees.
Section 179 Expensing for Equipment
Section 179 allows immediate expensing of up to $1 million in qualifying equipment purchases for 2026. Property managers can apply this deduction to vehicles, office furniture, computers, and specialized property management equipment. The deduction phases out dollar-for-dollar once total equipment purchases exceed approximately $2.5 million annually.
Strategic timing of equipment purchases maximizes Section 179 benefits. Property managers should coordinate purchases to fall within years when client income is highest, generating maximum tax savings. Equipment must be placed in service before December 31, 2026 to qualify for 2026 deductions.
Bonus Depreciation Restoration Under OBBBA
The Tax Cuts and Jobs Act phased down bonus depreciation from 100% to 80% in 2023, 60% in 2024, and 40% in 2025. The OBBBA reversed this phase-down, restoring 100% bonus depreciation for qualified property placed in service in 2026. This applies to property with recovery periods of 20 years or less, including most personal property and qualified improvement property.
Property managers should identify all qualifying property acquisitions and ensure proper classification to maximize bonus depreciation. This includes appliances, flooring, lighting systems, and HVAC equipment purchased in 2026. The combination of bonus depreciation and Section 179 creates planning flexibility to optimize deductions based on client tax situations.
| Asset Category | Recovery Period | 2026 Bonus Depreciation |
|---|---|---|
| Appliances | 5 years | 100% eligible |
| Carpeting and flooring | 5 years | 100% eligible |
| Office furniture | 7 years | 100% eligible |
| Landscaping | 15 years | 100% eligible |
| Building structure | 27.5 years | Not eligible |
Pro Tip: Schedule cost segregation studies early in 2026 for properties acquired in 2024 or 2025. Look-back studies can generate amended return refunds while optimizing ongoing depreciation schedules for maximum client benefit.
What Vehicle Expenses Can Property Managers Deduct?
Quick Answer: Property managers can choose between standard mileage rates or actual expense methods. For 2026, maintaining detailed mileage logs and comparing both methods ensures maximum deduction. High-mileage managers often save thousands annually with proper documentation.
Vehicle expenses represent a significant deduction for property managers who regularly travel between properties, meet with clients, and conduct inspections. The IRS requires meticulous documentation but rewards thorough record-keeping with substantial deductions. For 2026, property managers should evaluate both standard mileage and actual expense methods to determine the optimal approach.
Standard Mileage Method
The standard mileage method multiplies business miles by the IRS-approved rate. While the specific 2026 rate awaits final IRS publication, property managers should track all business mileage throughout the year. Qualifying business miles include travel to properties, client meetings, supply purchases, and banking activities related to property management.
Property managers must maintain contemporaneous logs documenting mileage, destinations, and business purposes. Mobile apps like MileIQ or Everlance simplify tracking by automatically recording trips and categorizing business versus personal use. The standard mileage method includes depreciation, so property managers cannot claim additional depreciation deductions when using this method.
Actual Expense Method
The actual expense method deducts the business-use percentage of all vehicle costs. Deductible expenses include gas, oil, insurance, registration fees, repairs, tires, and depreciation. Property managers must determine the business-use percentage by dividing business miles by total annual miles. A vehicle driven 15,000 business miles out of 20,000 total miles has a 75% business-use percentage.
For 2026, vehicles qualify for Section 179 expensing up to $1 million and 100% bonus depreciation if used more than 50% for business. SUVs weighing over 6,000 pounds receive special treatment with up to $28,900 in first-year Section 179 deductions, plus bonus depreciation on the remaining basis. This creates substantial first-year write-offs for qualifying property management vehicles.
Comparing Methods for Maximum Deductions
Property managers should calculate deductions under both methods annually to determine the optimal approach. Generally, high-mileage vehicles with lower operating costs favor the standard mileage method, while luxury vehicles or those requiring significant repairs favor the actual expense method. Once a property manager chooses actual expenses, they cannot switch to standard mileage for that vehicle in future years.
Parking fees and tolls for business purposes are deductible regardless of which method you choose. Property managers should maintain separate records for these expenses. Additionally, interest on vehicle loans is deductible based on business-use percentage when using the actual expense method.
What Technology and Software Deductions Can Property Managers Claim?
Quick Answer: Property management software subscriptions, website hosting, accounting systems, and communication tools are fully deductible. Computer equipment qualifies for Section 179 expensing. Strategic technology investments reduce taxes while improving operational efficiency.
Technology represents both a business necessity and significant tax deduction opportunity for property managers in 2026. From property management platforms to communication systems, business owners can deduct technology expenses that support operations. Understanding the distinction between currently deductible subscriptions and capitalizable software development ensures optimal tax treatment.
Software Subscriptions and SaaS Platforms
Monthly or annual subscriptions for property management software are currently deductible business expenses. This includes platforms like AppFolio, Buildium, Rent Manager, and specialized tenant screening services. Accounting software subscriptions, customer relationship management systems, and communication platforms like Slack or Microsoft Teams qualify as ordinary and necessary business expenses.
For 2026, property managers should aggregate all subscription costs to understand total technology investment. Many managers underestimate these expenses, missing thousands in annual deductions. Email marketing platforms, website hosting, domain registrations, and cloud storage subscriptions all qualify as deductible technology costs. Use our Property Manager Tax Planning Playbook to identify overlooked technology deductions.
Computer Equipment and Hardware
Computers, tablets, smartphones, and peripheral equipment qualify for immediate Section 179 expensing. Property managers can deduct up to $1 million in equipment purchases for 2026, making technology upgrades particularly attractive from a tax perspective. This includes monitors, printers, scanners, external hard drives, and networking equipment.
Smartphones present unique opportunities since many property managers use personal devices for business purposes. The business-use percentage of phone costs, including monthly service fees and device purchases, is deductible. However, maintaining documentation of business versus personal use is essential for audit protection.
Custom Software Development
Property managers who develop custom software or significantly customize existing platforms may qualify for R&D deductions. The OBBBA’s restoration of immediate R&D expensing for 2026 means costs for developing proprietary systems can be deducted immediately rather than amortized over multiple years. This applies to internal development costs and amounts paid to third-party developers.
Website development costs require careful analysis. Simple informational websites are currently deductible, while complex e-commerce or application platforms may require capitalization. However, ongoing website maintenance, content updates, and hosting fees remain currently deductible regardless of initial website complexity.
Pro Tip: Implement technology upgrades in December 2026 to claim full-year deductions while enjoying operational benefits throughout 2027. Section 179 only requires equipment to be placed in service before year-end, not in use for the entire year.
How Should Property Managers Allocate Home Office Expenses?
Quick Answer: Property managers using dedicated home office space can deduct a percentage of mortgage interest, property taxes, insurance, utilities, and repairs. The actual expense method typically generates $8,000 to $15,000 annual deductions for qualifying home offices.
Home office deductions provide substantial tax savings for property managers operating from residential locations. The IRS requires exclusive and regular use of a dedicated space for business purposes. For 2026, property managers must understand both the simplified and actual expense methods to maximize deductions while maintaining compliance with strict IRS requirements outlined in Publication 587.
Meeting the Exclusive and Regular Use Tests
The exclusive use test requires that the home office space is used only for business purposes. A dedicated room or clearly defined area meets this requirement. Property managers cannot claim home office deductions for spaces that serve dual purposes, such as dining rooms used occasionally for business meetings. The regular use test requires ongoing, consistent business use rather than occasional or incidental use.
For 2026, the principal place of business test allows deductions when the home office is used for administrative or management activities with no other fixed location for these activities. Property managers who visit properties daily but perform administrative work exclusively at home qualify for home office deductions under this rule.
Simplified Method Calculation
The simplified method allows a deduction of $5 per square foot up to 300 square feet, generating a maximum $1,500 annual deduction. This method requires no allocation of expenses or depreciation calculations. Property managers simply measure their dedicated office space and multiply by $5. The simplified method works well for small home offices or property managers who prefer minimal record-keeping.
Actual Expense Method for Maximum Deductions
The actual expense method typically generates larger deductions for property managers with substantial home office space. This method deducts the business-use percentage of home expenses, calculated by dividing office square footage by total home square footage. A 300-square-foot office in a 2,000-square-foot home has a 15% business-use percentage.
Deductible expenses under the actual expense method include:
- Mortgage interest (business percentage)
- Property taxes (business percentage)
- Homeowners insurance (business percentage)
- Utilities including electric, gas, water (business percentage)
- Home repairs and maintenance (business percentage)
- Depreciation on home (business percentage)
- Direct office expenses (100% deductible)
Direct expenses that benefit only the home office, such as painting the office or installing office-specific lighting, are 100% deductible regardless of the business-use percentage. This creates additional deduction opportunities beyond the standard allocation formula.
| Method | Calculation | Example Deduction |
|---|---|---|
| Simplified | $5 × square feet (max 300) | 250 sq ft × $5 = $1,250 |
| Actual Expense | Business % × qualified expenses | 15% × $60,000 expenses = $9,000 |
Uncle Kam in Action: Multi-Property Manager Recovers $127,000
Sarah Chen managed 47 residential properties across Atlanta generating $890,000 in annual management fees. Despite profitable operations, Sarah paid excessive taxes due to overlooked deductions and improper expense classifications. She approached Uncle Kam seeking comprehensive tax strategy optimization for the 2026 tax year.
The Challenge
Sarah’s prior tax preparation treated all property improvements as repairs, generating immediate deductions but triggering IRS audit risk. She capitalized technology investments that qualified for R&D expensing. Her vehicle tracking consisted of annual estimates rather than contemporaneous logs. Sarah used the simplified home office method despite operating from a 400-square-foot dedicated office in her 2,800-square-foot home.
The Uncle Kam Solution
Uncle Kam’s tax strategists implemented a comprehensive property manager deduction optimization plan. They reclassified $89,000 in capitalized technology development as immediately deductible R&D expenses under OBBBA provisions. A cost segregation study on Sarah’s business office condo identified $43,000 in accelerated depreciation previously treated as 39-year real property.
The team corrected repair versus improvement classifications, properly documenting $67,000 in immediate repair deductions while establishing compliant improvement capitalization for three major renovations. They switched Sarah to the actual expense home office method, generating $11,200 in deductions versus the $1,500 simplified method limit. Vehicle expense analysis using the actual expense method with Section 179 for her new SUV created $31,000 in first-year deductions.
Most significantly, Uncle Kam identified $52,000 in qualifying R&D expenses from Sarah’s 2022-2024 custom software development projects. They filed amended returns before the July 6, 2026 deadline, recovering $18,200 in federal tax refunds from prior years.
The Results
- 2026 Tax Savings: $108,800 in federal and state tax reductions
- Prior Year Refunds: $18,200 from amended 2022-2024 returns
- Total First-Year Benefit: $127,000
- Uncle Kam Investment: $8,500 in advisory fees
- Return on Investment: 1,494% first-year ROI
Sarah now maintains compliant documentation systems that withstand IRS scrutiny while maximizing every available deduction. Her ongoing relationship with Uncle Kam includes quarterly tax planning sessions and annual strategy updates. The comprehensive approach transformed her tax situation from reactive preparation to proactive optimization. See more success stories at our client results page.
Next Steps
Property managers ready to maximize deductions for clients should take these immediate actions:
- Review 2022-2024 returns for qualifying R&D expenses before the July 6, 2026 amendment deadline
- Implement contemporaneous mileage tracking for all business vehicle use in 2026
- Calculate home office deductions under both simplified and actual expense methods
- Document all technology subscriptions and software expenses for proper deduction classification
- Schedule a tax strategy session to identify property-specific deduction opportunities
- Consider cost segregation studies for recently acquired income properties
Tax professionals working with property managers should explore tax planning software with unlimited assessments to identify client-specific opportunities. Uncle Kam’s MERNA™ framework evaluates the complete tax picture across multiple entities and income sources, ensuring no deduction opportunity is missed.
Frequently Asked Questions
Can property managers deduct client entertainment expenses in 2026?
For 2026, traditional entertainment expenses like concert tickets or golf outings are not deductible. However, business meals with clients remain 50% deductible when discussing business matters. The meal must have a clear business purpose, and property managers should document the business topics discussed. Meals provided during business meetings at the office may qualify for 100% deduction under specific circumstances.
What documentation is required for repair versus improvement classifications?
Property managers should maintain detailed invoices showing the nature and extent of work performed. Include before and after photos, contractor estimates, and written explanations of why expenses qualify as repairs. Documentation should demonstrate that work restored property to original condition rather than bettering or adapting it. For significant expenses, obtain written assessments from contractors explaining repair versus improvement classifications.
How does bonus depreciation interact with Section 179 deductions?
Property managers can use both deductions, but strategic sequencing matters. Section 179 applies first, reducing asset basis before calculating bonus depreciation. For 2026, with 100% bonus depreciation restored, most property managers maximize deductions by claiming Section 179 up to the limit, then applying bonus depreciation to remaining assets. This approach works well when total equipment purchases exceed the Section 179 limit.
What happens if I miss the July 6, 2026 R&D amendment deadline?
Missing the deadline forfeits the opportunity to amend prior year returns for R&D expensing. However, property managers can still claim immediate expensing for R&D costs incurred in 2026 and future years. The retroactive amendment opportunity specifically applies to 2022-2024 tax years and expires permanently after July 6, 2026. Property managers with qualifying prior year expenses should prioritize this deadline.
Can I deduct costs for managing my own rental properties?
Property managers who also own rental properties face special rules. Self-management of personally owned rentals generates deductions on Schedule E, not as business expenses. However, expenses for the property management business operation, including managing third-party properties, qualify as business deductions. Maintain separate record-keeping systems to distinguish between personal rental expenses and property management business costs.
What are the tax implications of receiving property management fees in advance?
For 2026, cash-basis taxpayers report income when received, including advance payments. Accrual-basis taxpayers generally report income when earned, regardless of payment timing. Property managers receiving annual management fees in advance must typically report the full amount as income in the year received. However, specific advance payment deferral rules may apply in limited circumstances. Consult with tax professionals about optimal accounting method selection.
How should property managers handle cybersecurity and data protection costs?
Cybersecurity expenses are fully deductible business costs for 2026. This includes antivirus software, firewall systems, security audits, and data backup services. Property managers handling sensitive tenant information should invest in robust security systems and deduct all related costs. Cybersecurity insurance premiums also qualify as deductible business insurance expenses.
What retirement plan options maximize deductions for property management businesses?
For 2026, self-employed property managers can contribute up to $22,500 to solo 401(k) plans as employee deferrals, plus an additional $7,500 catch-up if age 50 or older. Employer profit-sharing contributions add up to 25% of compensation. SEP IRAs allow contributions up to 25% of net self-employment income. These retirement contributions reduce current taxable income while building tax-deferred retirement savings. Property management businesses with employees should explore Safe Harbor 401(k) plans for maximum contribution flexibility.
Are property management license and bond costs deductible?
Yes, property management license fees, surety bonds, and errors and omissions insurance are fully deductible. For 2026, these costs qualify as ordinary and necessary business expenses. Annual license renewals, continuing education required for license maintenance, and professional association dues all generate current-year deductions. Document these expenses carefully as some jurisdictions require specific license types that may have different tax treatment.
Related Resources
- Comprehensive Tax Strategy Planning for Business Owners
- Real Estate Investor Tax Optimization Strategies
- Entity Structure Selection for Property Management Businesses
- The MERNA™ Method: Systematic Tax Planning Framework
- Free Tax Planning Calculators and Tools
Last updated: June, 2026
This information is current as of 6/21/2026. Tax laws change frequently. Verify updates with the IRS or professional tax advisors if reading this later.

