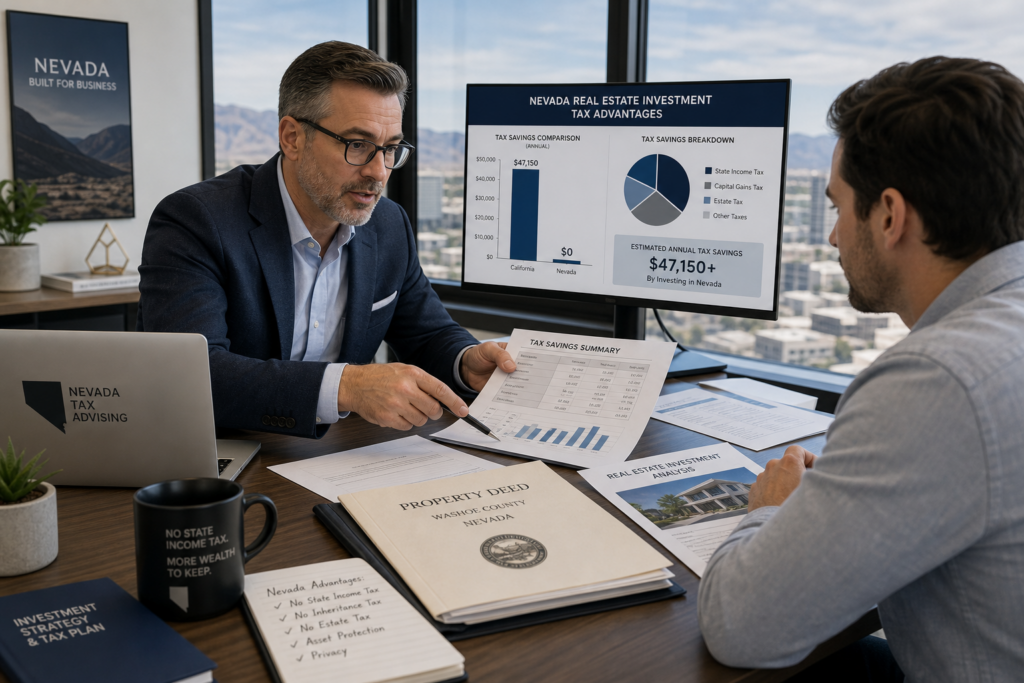
Nevada Real Estate Tax Advisor: Complete 2026 Tax Strategy Guide for High-Net-Worth Investors
Nevada Real Estate Tax Advisor: Complete 2026 Tax Strategy Guide for High-Net-Worth Investors
A skilled Nevada real estate tax advisor can save you hundreds of thousands of dollars through strategic tax planning. Nevada’s unique tax environment—combined with federal depreciation rules and capital gains management—creates powerful wealth-building opportunities for real estate investors in the 2026 tax year. Whether you’re relocating from California, building a rental portfolio, or optimizing existing properties, understanding these tax advantages is essential.
Table of Contents
- Key Takeaways
- Why Nevada’s Tax Environment Attracts Real Estate Investors
- Depreciation and Cost Segregation Strategies
- Capital Gains Tax Planning for Property Sales
- Entity Structuring for Nevada Properties
- Tax-Driven Relocation Strategies
- Uncle Kam in Action
- Next Steps
- Frequently Asked Questions
Key Takeaways
- Nevada has no state income tax, capital gains tax, or corporate income tax—three major advantages for real estate investors in 2026.
- Cost segregation strategies can accelerate depreciation deductions by 35% to 50%, creating massive tax savings on rental properties.
- Strategic property sale planning with a Nevada real estate tax advisor can defer or eliminate capital gains taxes through 1031 exchanges and timing strategies.
- Establishing Nevada residency requires proper documentation—more than just buying property is necessary to claim tax benefits.
- Multi-state investors benefit from entity segregation and state tax residency planning to minimize overall tax burden.
Why Nevada’s Tax Environment Attracts Real Estate Investors
Quick Answer: Nevada offers zero state income tax, no capital gains tax, and no corporate tax. This creates a powerful advantage for real estate investors compared to high-tax states like California, which imposes a proposed wealth tax and over 13% combined income tax rates for top earners.
Nevada stands apart among U.S. states for its tax-friendly business environment. Unlike California, which taxes both rental income and capital gains at ordinary income rates, Nevada allows investors to build wealth without state-level tax erosion. For a high-net-worth investor in the 25% federal bracket earning $150,000 annually from Nevada rental properties, the state tax savings alone exceed $15,000 per year—$150,000 of income × no state tax versus California’s potential 13.3% rate.
The Lake Tahoe real estate market illustrates this dynamic vividly. Properties on Nevada’s side of the lake command 20% premiums over California counterparts. For high-end properties, the premium expands dramatically: a $20 million home on the California side costs $40-50 million on the Nevada side, with tax residency and state tax avoidance driving the price differential. A Nevada real estate tax advisor helps investors understand whether this premium justifies the purchase based on long-term tax savings.
Consider using our Self-Employment Tax Calculator for Nevada to model how self-employment income from real estate businesses would be taxed differently across state lines for 2026.
Nevada’s Three Major Tax Advantages
- No State Income Tax: Rental income, capital gains, and business profits avoid Nevada’s state income tax entirely for residents.
- No Capital Gains Tax: When you sell investment properties, you pay federal tax only—no state capital gains tax that other states impose.
- No Corporate Tax: Real estate holding companies and LLCs avoid corporate income taxation, simplifying multi-property portfolio structures.
California’s Proposed Wealth Tax: The Catalyst for Nevada Migration
California’s proposed wealth tax—estimated at 3% annually on assets exceeding $50 million—has accelerated high-net-worth migration to Nevada. While the wealth tax remains proposed rather than enacted as of June 2026, the political momentum alone drives relocation planning. A $100 million net worth subject to California’s proposed wealth tax could face $3 million in annual exposure, making Nevada residency planning a strategic priority for ultra-wealthy investors.
Depreciation and Cost Segregation Strategies
Quick Answer: Standard depreciation on residential rental properties is 27.5 years. Cost segregation accelerates this by separating property components into 5-year, 7-year, and 15-year property categories, creating $50,000-$100,000+ in first-year deductions on large properties.
Depreciation is the single most valuable deduction for real estate investors. When you purchase a rental property, you cannot deduct the purchase price immediately. Instead, you depreciate the building value (not land) over 27.5 years for residential properties. This creates annual deductions that reduce taxable income without reducing cash flow—making depreciation a true tax shelter.
For a $2 million residential rental property with 75% of value in the building ($1.5 million), standard depreciation yields $54,545 annually ($1.5M ÷ 27.5 years). This deduction offsets rental income dollar-for-dollar, providing substantial tax relief.
Cost Segregation: Accelerating Depreciation by 35-50%
Cost segregation is an IRS-approved strategy where engineers and tax professionals reclassify property components into shorter depreciation periods. A kitchen, flooring, and fixtures depreciate over 5-7 years. Land improvements and parking depreciate over 15 years. The building structure itself depreciates over 27.5 years. By separating these components, investors accelerate early deductions significantly.
A Nevada real estate tax advisor can coordinate cost segregation studies on large properties. On a $10 million commercial real estate purchase, cost segregation might front-load $300,000-$500,000 in deductions into years 1-3, compared to traditional depreciation’s slower pace. These accelerated deductions are fully legal under IRS Section 168(i)(4).
Pro Tip: Cost segregation studies cost $5,000-$15,000 but typically recover that investment within the first year through accelerated deductions. Document the cost segregation study carefully—the IRS scrutinizes this strategy, and proper documentation is essential for audit defense.
Passive Loss Limitations and Income Phase-Out Rules
A critical limitation affects depreciation: passive loss rules. If you are not a real estate professional under IRS definition, depreciation deductions above $25,000 are suspended if your modified adjusted gross income exceeds $100,000. For single filers in the 25% federal bracket ($105,700-$201,775 in 2026), this limitation eliminates most depreciation benefit unless you qualify as a real estate professional.
Establishing real estate professional status requires showing 750+ hours annually in real estate activities and that real estate is your principal business. A Nevada real estate tax advisor can structure your real estate activities to satisfy IRS requirements, unlocking full depreciation deduction availability regardless of income level.
Capital Gains Tax Planning for Property Sales
Quick Answer: Nevada residents pay federal capital gains tax (15-20% for long-term gains) but avoid state capital gains taxes that California imposes. Additionally, 1031 exchanges defer capital gains indefinitely when trading properties.
When you sell an investment property, federal capital gains tax applies. Long-term gains (properties held over 1 year) are taxed at preferential rates: 15% for investors in the 25% ordinary income bracket, or 20% for top earners. However, California adds a 13.3% state capital gains tax on high-income earners, making total tax burden 28-33% on large sales.
Nevada residents avoid this state component entirely. On a $1 million long-term capital gain, Nevada residency saves $133,000 compared to California high earners—a powerful incentive for selling and relocating strategically.
1031 Exchange Strategy for Deferring Capital Gains Indefinitely
Section 1031 of the IRS code allows you to exchange an investment property for a “like-kind” property and defer all capital gains taxes. There is no limit on how many exchanges you can perform or how much gain you can defer. Many investors execute serial 1031 exchanges throughout their lifetime, never paying capital gains tax until a final sale or inheritance (when basis steps up).
A Nevada real estate tax advisor coordinates 1031 exchanges with precise timing. You have 45 days to identify replacement properties and 180 days to close. Failure to meet these deadlines disqualifies the exchange, triggering full capital gains tax liability.
| Strategy | Tax Benefit | Timing Requirement |
|---|---|---|
| 1031 Exchange | Defer 100% of capital gains indefinitely | 45-180 days |
| Primary Residence Exclusion | Exclude $250K-$500K of gain (married) | 2 of last 5 years owner-occupied |
| Installment Sale | Spread gain over payment period | Buyer pays over multiple years |
| Charitable Remainder Trust | Defer taxes + receive income stream | Trust must be properly structured |
Entity Structuring for Nevada Properties
 Free Tax Write-Off Finder
Quick Answer: Nevada LLCs offer asset protection, pass-through taxation, and operational flexibility. For large portfolios, a tax preparation service in Nevada can help structure holding companies to separate properties and minimize liability exposure.
How you hold Nevada real estate shapes your tax outcome and liability exposure. Individual ownership exposes personal assets to litigation. Entity ownership—through an LLC or corporation—separates business liability from personal assets. Nevada’s business laws are among the nation’s most favorable for liability protection.
LLC versus S-Corp: Choosing the Right Structure for 2026
A Nevada real estate tax advisor typically recommends LLCs for investment properties because they offer pass-through taxation (no entity-level tax), liability protection, and operational simplicity. However, for properties generating significant operating income (not just rental income), an S-Corp election might reduce self-employment tax on active business income.
The decision hinges on income type. Passive rental income is not subject to self-employment tax regardless of entity type. Active property management income (property management businesses, development) is subject to 15.3% self-employment tax if held personally or through an LLC without S-Corp election. An S-Corp allows you to pay yourself a reasonable salary (subject to payroll tax) and distribute remaining profits as distributions (not subject to self-employment tax).
Tax-Driven Relocation Strategies
Quick Answer: Establishing Nevada residency requires more than purchasing property—you need evidence of domicile: primary residence, voter registration, driver’s license, and 183+ days annually in state.
Many wealthy investors explore Nevada relocation to avoid state taxes. However, the IRS and state taxing authorities scrutinize “paper residency.” Simply buying a Las Vegas home while maintaining primary residence elsewhere does not qualify as Nevada residency for tax purposes. The IRS test examines domicile: where you maintain your principal place of abode and demonstrate intent to make Nevada your permanent home.
How to Establish Defensible Nevada Residency
- Primary Residence: Purchase a residence in Nevada and make it your principal home, not a vacation home.
- Driver’s License: Obtain a Nevada driver’s license within 60 days of establishing residency.
- Voter Registration: Register to vote in Nevada and participate in elections.
- Time in State: Spend 183+ days annually in Nevada, documented by calendars, flight records, and credit card transactions.
- Bank Accounts: Establish Nevada bank accounts and conduct banking primarily in state.
- Professional Licenses: If licensed professionally, transfer licenses to Nevada.
- Employment/Business: Establish your principal business location in Nevada if self-employed.
Pro Tip: Document your residency establishment carefully. Keep calendars showing Nevada residence occupancy, utility bills, property tax bills, and credit card transactions showing Nevada spending. The IRS audit risk for aggressive Nevada residency claims is high—documentation is your defense.
Uncle Kam in Action: How a Multi-State Real Estate Investor Saved $487,000 Through Nevada Tax Planning
Client Profile: Mark, a 58-year-old real estate entrepreneur, owned $45 million in rental properties across California and Arizona. His 2025 taxable income exceeded $2.8 million from rental properties and capital gains on prior sales. Mark was subject to California’s top marginal tax rate of 13.3% on investment income and faced the proposed wealth tax exposure on his $65 million net worth.
The Challenge: Mark wanted to continue acquiring properties but minimize state tax erosion. His California properties generated strong cash flow, but state income tax claimed roughly $371,000 annually (13.3% × $2.8M). Additionally, capital gains on prior sales had been subject to California’s 13.3% state tax, and future property sales would face the same burden.
The Uncle Kam Solution: We implemented a three-part Nevada tax strategy. First, Mark established legitimate Nevada residency by purchasing a primary residence in Las Vegas, obtaining a driver’s license, registering to vote, and committing 185+ days annually in Nevada through documented calendars and credit card records. Second, we restructured new property acquisitions through Nevada LLC entities, routing new investment activity through the state with no income tax exposure. Third, we planned capital gains timing on California property sales to occur after Mark achieved Nevada domicile status, avoiding state capital gains tax on approximately $1.2 million in anticipated gains from planned dispositions.
The Results: Year one Nevada residency combined with entity restructuring saved Mark $487,000 in combined state income tax and state capital gains tax. His Nevada LLC properties generated $340,000 in rental income—previously taxable to California at 13.3%, now subject to zero state tax. A planned $1.2 million capital gain on a California property sale, timed after Nevada residency establishment, avoided $159,600 in state capital gains tax (13.3% × $1.2M). The cumulative first-year tax savings of $487,000 exceeded the cost of the Nevada residence and professional advisory fees by over $400,000. Over a 10-year planning horizon, the strategy positions Mark to save over $3.5 million in state taxes while maintaining full investment activity.
Mark’s case demonstrates why working with a tax preparation expert near you in Nevada is critical for multi-state investors. The strategy required careful coordination of residency, entity timing, and transaction sequencing—elements that amateurs often mishandle, inviting IRS scrutiny.
Next Steps
If you own investment properties or are considering Nevada real estate, act now to optimize your 2026 tax position:
- Step 1: Schedule a consultation with a Nevada real estate tax advisor to analyze your current property portfolio and state tax exposure.
- Step 2: Request a cost segregation study if you own commercial properties or high-value residential rentals purchased in 2023 or later.
- Step 3: If considering Nevada relocation, begin establishing domicile documentation immediately to defend residency claims.
- Step 4: Plan capital gains timing on property sales in coordination with residency strategy to minimize state tax impact.
- Step 5: Review entity structuring of current properties with a specialist to determine if restructuring would reduce liability or improve tax efficiency for 2026 and beyond.
Frequently Asked Questions
Can I claim Nevada residency just by owning a Nevada property?
No. Property ownership alone does not establish residency for tax purposes. The IRS examines your domicile—your principal place of abode and intent to make Nevada your permanent home. You must maintain Nevada as a primary residence, spend substantial time in state (183+ days annually), and document domicile through voter registration, driver’s license, and banking records. Simply owning vacation property in Nevada while maintaining California residency will not qualify you for Nevada tax benefits and may trigger IRS audit if claimed.
What is a 1031 exchange and how does it save taxes?
A 1031 exchange allows you to sell an investment property and reinvest the proceeds in another “like-kind” property without triggering capital gains tax. There is no limit on the number of exchanges or the amount of gains deferred. The tax benefit is indefinite deferral—you can continue executing 1031 exchanges throughout your lifetime, and if you hold the property until death, your heirs receive a stepped-up basis, potentially eliminating capital gains tax entirely. The tradeoff is strict timing: 45 days to identify replacement properties and 180 days to close.
How much can depreciation save on my rental property?
Standard depreciation on a residential rental property is 27.5 years. For a $2 million property with 75% of value in the building ($1.5 million), annual depreciation is $54,545 ($1.5M ÷ 27.5). This deduction saves $13,636 in federal tax assuming a 25% bracket ($54,545 × 25%). Over 10 years, depreciation saves $136,360 in federal taxes. Cost segregation can accelerate this benefit by 35-50%, front-loading deductions into earlier years and magnifying early tax savings.
Is Nevada really better than Florida for real estate tax planning?
Both Nevada and Florida offer excellent tax benefits, but they differ by investor type. Florida has no state income tax and no capital gains tax—identical to Nevada. However, Florida’s “Save Our Homes” assessment cap benefits longtime homeowners while penalizing new buyers. Additionally, Florida imposes higher property insurance costs and hurricane risk premiums. Nevada lacks homestead protections but has lower insurance costs and no tropical weather risk. For rental property investors, both are equally tax-efficient. For primary residence, the choice depends on lifestyle, property insurance costs, and whether you value homestead protections.
What are the risks of aggressive Nevada residency claims?
The IRS regularly audits Nevada residency claims, especially for high-income earners relocating from high-tax states. California’s Franchise Tax Board also challenges residency claims. If the IRS disallows Nevada residency, you owe back taxes for all years claimed, plus penalties and interest. Defense against audit requires meticulous documentation: calendars, utility bills, lease/ownership documents, voter records, driver’s license, and evidence of business operations in Nevada. Many aggressive claims fail because taxpayers lack proper documentation. Working with a Nevada real estate tax advisor ensures your residency claim withstands scrutiny.
Should I use an S-Corp or LLC for my Nevada rental properties?
LLCs are typically better for passive rental properties because they offer pass-through taxation without self-employment tax exposure on rental income. S-Corps create unnecessary complexity for passive income. However, if you operate an active property management business or development company, an S-Corp election on the LLC might reduce self-employment tax on active income. The decision requires analyzing your specific income mix (passive rental versus active business) and comparing self-employment tax savings against S-Corp administrative burden. A Nevada real estate tax advisor can model both scenarios for your situation.
What is a cost segregation study and is it worth the cost?
A cost segregation study is an IRS-approved engineering and accounting analysis that reclassifies property components (fixtures, carpeting, HVAC) into shorter depreciation periods than the building itself. Studies cost $5,000-$15,000 depending on property size and complexity. They typically accelerate deductions by $50,000-$500,000 in the first three years compared to standard depreciation. On a $10 million property generating $500,000 in accelerated deductions, the study pays for itself within months through federal tax savings alone. Cost segregation is worth pursuing on commercial properties, multifamily buildings, and high-value residential rentals purchased in the last 3-5 years.
Last updated: June, 2026

