
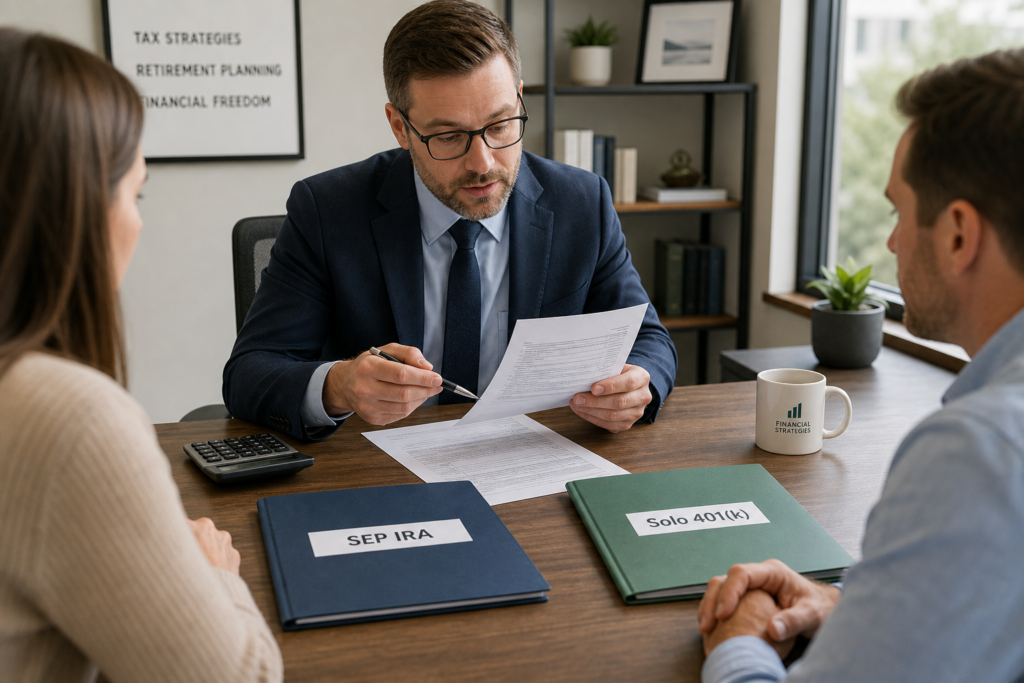
SEP IRA vs Solo 401k: Which Is Better for Clients in 2026?
Choosing between a SEP IRA vs solo 401k for clients is one of the most consequential retirement planning decisions tax professionals make for self-employed individuals and small business owners. For the 2026 tax year, understanding the nuances between these two powerful retirement vehicles can mean the difference between maximizing client savings and leaving thousands of dollars on the table. With SECURE 2.0 credits, state retirement mandates, and evolving contribution strategies, tax advisors need a clear framework to guide clients toward the optimal choice.
Table of Contents
- Key Takeaways
- What Are the Fundamental Differences Between SEP IRAs and Solo 401(k)s?
- How Do Contribution Limits Compare for 2026?
- Which Plan Offers Better Flexibility for Client Scenarios?
- What Are the Administrative Requirements and Costs?
- How Does SECURE 2.0 Impact Your Plan Recommendation?
- What About State Retirement Plan Mandates in 2026?
- Uncle Kam in Action: Atlanta CPA Delivers $22,000 in Tax Savings
- Next Steps
- Frequently Asked Questions
- Related Resources
Key Takeaways
- Solo 401(k)s allow up to $70,000 in total contributions for 2026 (age 50+), while SEP IRAs max out at 25% of compensation
- SEP IRAs require virtually no annual filing requirements, whereas solo 401(k)s trigger Form 5500-EZ above $250,000 in assets
- SECURE 2.0 provides up to $5,000 annually in startup tax credits for both plan types in 2026
- Solo 401(k)s offer loan provisions and Roth contribution options that SEP IRAs do not
- State retirement mandates in 18+ states make offering a qualified plan increasingly valuable for small business owners
What Are the Fundamental Differences Between SEP IRAs and Solo 401(k)s?
Quick Answer: SEP IRAs are employer-only contribution plans with minimal administration, while solo 401(k)s allow both employee deferrals and employer contributions with more flexibility but increased complexity.
Understanding the SEP IRA vs solo 401k comparison starts with recognizing their structural differences. A SEP IRA (Simplified Employee Pension) is funded exclusively through employer contributions. The business owner makes discretionary contributions on behalf of eligible employees, including themselves. There are no employee deferrals allowed.
In contrast, a solo 401(k), also called an individual 401(k), functions as a traditional 401(k) plan designed for business owners with no employees other than a spouse. It allows contributions in two capacities: as an employee making salary deferrals, and as an employer making profit-sharing contributions. This dual-contribution structure is what makes solo 401(k)s particularly powerful for high-income self-employed professionals.
Eligibility Requirements
SEP IRAs are available to any business structure. Sole proprietors, partnerships, S corporations, and C corporations can all establish SEP IRAs. However, if the business has employees, the employer must contribute the same percentage of compensation for all eligible employees as they contribute for themselves.
Solo 401(k)s are strictly limited to self-employed individuals or business owners with no full-time employees other than a spouse. Once a business hires its first W-2 employee who works more than 1,000 hours annually, it can no longer maintain a solo 401(k) and must transition to a traditional 401(k) plan. This is a critical threshold for growing businesses.
Contribution Structure and Timing
SEP IRA contributions can be made anytime up to the business tax return filing deadline, including extensions. This gives tax professionals flexibility when optimizing client tax situations for the prior year. For clients who file their 2026 tax return in early 2027, they can still make SEP contributions for 2026 up until the October 15, 2027 extension deadline.
Solo 401(k) employee deferrals must be made by December 31 of the tax year. However, employer profit-sharing contributions can be made up to the tax filing deadline plus extensions, similar to SEP IRAs. This timing distinction is crucial when advising clients on year-end tax planning strategies.
Pro Tip: For clients who realize late in the year that they need higher deductions, solo 401(k) employee deferrals require December 31 execution, while SEP IRAs offer flexibility through the extension deadline. This timing difference can determine which plan is operationally feasible.
How Do Contribution Limits Compare for 2026?
Quick Answer: For 2026, solo 401(k)s allow up to $70,000 total contribution for those age 50+, while SEP IRAs are limited to 25% of compensation with no catch-up provisions.
The contribution limits reveal the most significant difference when evaluating SEP IRA vs solo 401k options for clients. For tax advisory services focused on maximizing retirement savings, understanding these limits is essential.
Solo 401(k) Contribution Limits for 2026
Solo 401(k)s offer two contribution channels. As an employee, a client can defer up to $23,000 in 2026. If they are age 50 or older by December 31, 2026, they can make an additional $7,500 catch-up contribution, bringing the employee deferral total to $30,500.
As an employer, they can contribute up to 25% of compensation (for S corps and C corps) or 20% of net self-employment income (for sole proprietors and single-member LLCs after accounting for the self-employment tax deduction). The combined total from both employee deferrals and employer contributions cannot exceed $63,500 for those under age 50, or $70,000 for those age 50 and older in 2026.
SEP IRA Contribution Limits for 2026
SEP IRA contributions are capped at the lesser of 25% of compensation or $66,000 for 2026. For self-employed individuals, the effective contribution percentage is approximately 20% of net self-employment income after accounting for the self-employment tax deduction. There are no catch-up contributions for those age 50 or older, which can be a significant disadvantage for older clients.
Tax professionals can use the SEP IRA contribution strategy hub to quickly model 2026 SEP scenarios and integrate them into broader tax plans.
Comparative Analysis: When Solo 401(k)s Win on Contributions
Solo 401(k)s deliver higher total contributions for clients with moderate to high income. Consider a 52-year-old sole proprietor with $150,000 in net self-employment income for 2026. After the self-employment tax deduction, their adjusted net earnings are approximately $140,775.
| Plan Type | Employee Deferral | Employer Contribution | Total 2026 Contribution |
|---|---|---|---|
| Solo 401(k) | $30,500 (with catch-up) | $28,155 (20% of $140,775) | $58,655 |
| SEP IRA | N/A | $28,155 (20% of $140,775) | $28,155 |
The solo 401(k) allows an additional $30,500 in contributions due to the employee deferral component. At the 24% federal tax bracket (which begins at $211,400 for married filing jointly in 2026, per IRS inflation adjustments), this represents over $7,320 in immediate federal tax savings, not including state tax benefits.
Which Plan Offers Better Flexibility for Client Scenarios?
Quick Answer: Solo 401(k)s offer Roth options, loan provisions, and flexible contribution strategies, while SEP IRAs provide unmatched simplicity and employee scalability.
When recommending a plan for self-employed clients, flexibility often matters as much as contribution limits. The SEP IRA vs solo 401k decision should account for lifestyle, business trajectory, and financial planning goals.
Roth Contribution Options
Solo 401(k)s can be designed to accept Roth contributions. Clients can designate all or part of their employee deferrals as Roth, paying taxes now in exchange for tax-free growth and qualified distributions. This is particularly valuable for younger clients in lower tax brackets or those expecting significantly higher income in retirement.
SEP IRAs do not offer a Roth option. All contributions are made pre-tax, meaning future distributions will be taxed as ordinary income. However, clients can execute Roth conversions from SEP IRAs to Roth IRAs in subsequent years, though this requires careful tax planning to manage the conversion tax liability.
Loan Provisions and Emergency Access
Solo 401(k) plans can include loan provisions allowing participants to borrow up to $50,000 or 50% of the vested account balance, whichever is less. While borrowing from retirement accounts is rarely advisable, this feature provides a safety valve for clients facing genuine financial emergencies without triggering taxes and penalties.
SEP IRAs do not permit loans. Any withdrawal before age 59½ is subject to ordinary income tax plus a 10% early withdrawal penalty, unless an exception applies. For risk-averse clients who value liquidity options, this is a meaningful distinction.
Handling Employee Growth
SEP IRAs scale seamlessly as businesses add employees. The employer simply contributes the same percentage for all eligible employees. While this increases cost, it maintains administrative simplicity. Employees are immediately vested in all SEP contributions.
Solo 401(k)s become ineligible once a business hires its first non-spouse employee working more than 1,000 hours annually. At that point, the business must either terminate the solo 401(k) or convert it to a traditional 401(k) plan with significantly higher complexity and cost. For clients planning to hire within the next few years, a SEP IRA may offer better long-term viability.
Pro Tip: For consultants and freelancers with unpredictable income, solo 401(k) employee deferrals can be made from each paycheck throughout the year, providing regular tax-advantaged savings. SEP contributions typically happen once annually, which requires more discipline and cash flow planning.
What Are the Administrative Requirements and Costs?
Quick Answer: SEP IRAs require virtually no annual reporting, while solo 401(k)s trigger Form 5500-EZ once plan assets exceed $250,000.
Administrative burden is a decisive factor when tax professionals evaluate SEP IRA vs solo 401k options for time-constrained clients. The difference in ongoing compliance requirements can influence long-term plan satisfaction and adherence.
SEP IRA Simplicity
SEP IRAs are the simplest retirement plan to administer. There are no annual filing requirements with the IRS, regardless of plan size. The business owner completes a one-page IRS Form 5305-SEP to establish the plan initially, and that document is retained on file, not filed with the IRS.
Record-keeping consists of documenting the annual contribution percentage and ensuring it is applied uniformly to all eligible employees. Most financial institutions that offer SEP IRAs handle account setup and maintenance automatically. The total annual administrative cost for a solo practitioner SEP IRA is typically zero beyond the underlying investment fees.
Solo 401(k) Compliance Requirements
Solo 401(k)s require more rigorous administration. Once the plan’s total assets exceed $250,000 as of the last day of the plan year, the business must file Form 5500-EZ annually. This form requires detailed plan information, including participant counts, asset values, and compliance certifications.
Establishing a solo 401(k) typically requires a formal plan document. Many financial institutions provide prototype documents at no cost, though customized plans prepared by ERISA attorneys can cost $1,500 to $3,000. Annual administration fees from third-party providers range from $200 to $800 depending on plan complexity and assets.
Setup Timeline Considerations
SEP IRAs can be established and funded retroactively up to the tax filing deadline plus extensions. A client can decide in September 2027 to set up a SEP IRA for the 2026 tax year, complete the paperwork, and make the contribution all at once.
Solo 401(k)s must be established by December 31 of the year for which contributions are desired. While employer profit-sharing contributions can be made after year-end, the plan itself must exist before December 31, 2026 to accept 2026 employee deferrals. This requires more proactive planning.
| Administrative Factor | SEP IRA | Solo 401(k) |
|---|---|---|
| Annual IRS Filing | None | Form 5500-EZ if assets > $250,000 |
| Plan Document Required | Simple one-page form | Formal adoption agreement |
| Setup Deadline | Tax filing deadline + extensions | December 31 of plan year |
| Typical Annual Admin Cost | $0 | $200–$800 |
How Does SECURE 2.0 Impact Your Plan Recommendation?
Quick Answer: SECURE 2.0 provides up to $5,000 annually in startup tax credits for three years for both SEP IRAs and solo 401(k)s, making the economic case for establishing qualified plans stronger than ever in 2026.
The SECURE 2.0 Act, passed in late 2022, introduced substantial tax incentives for small businesses establishing retirement plans. For tax professionals guiding business owner clients, these credits can offset or eliminate the cost of plan setup and administration.
Startup Tax Credit Details for 2026
Small businesses with 50 or fewer employees can claim a tax credit for qualified startup costs when establishing a SEP IRA, solo 401(k), SIMPLE IRA, or traditional 401(k). The credit equals 100% of qualified startup costs for businesses with 1 to 50 employees, up to the greater of $500 or $250 per non-highly compensated employee, with a maximum credit of $5,000 per year.
This credit is available for the first three years of the plan. Additionally, businesses with 1 to 50 employees can claim an additional credit for employer contributions equal to 100% of the first $1,000 contributed per employee in years one and two, phasing to 75% in year three, 50% in year four, and 25% in year five.
For a solo practitioner establishing a solo 401(k) in 2026, the startup credit can cover professional fees, custodian setup costs, and educational materials. Since solo 401(k) administrative costs typically run $200 to $800 annually, the $5,000 credit effectively pays for years of compliance costs in advance.
Economic Advantage in 2026
Prior to SECURE 2.0, the administrative cost difference between SEP IRAs and solo 401(k)s was a legitimate concern. A SEP IRA with zero ongoing costs was economically superior for clients with modest account balances. However, the SECURE 2.0 startup credits eliminate this cost barrier entirely for the first three years, shifting the economic calculus toward solo 401(k)s for clients who can maximize the higher contribution limits.
For clients establishing plans in 2026, tax professionals should model both scenarios, comparing the immediate tax savings from higher contributions against the administrative costs over time, now with the credits factored in. In most cases involving self-employed professionals earning over $100,000 annually, the solo 401(k) with SECURE 2.0 credits becomes the optimal choice.
Pro Tip: The SECURE 2.0 credits must be claimed on Form 8881. Many tax professionals overlook this form when preparing returns, leaving thousands of dollars in credits unclaimed. Add Form 8881 review to your 2026 return preparation checklist for any client who established a new retirement plan in the past three years.
What About State Retirement Plan Mandates in 2026?
Quick Answer: By year-end 2026, 18 or more states require small businesses to offer retirement plans or enroll in state-run auto-IRA programs, making private plans like SEP IRAs and solo 401(k)s increasingly valuable compliance strategies.
State retirement plan mandates are rapidly expanding across the United States. These laws require businesses above certain employee thresholds to either offer a qualified retirement plan or automatically enroll employees in state-administered Roth IRA programs. For tax professionals advising small businesses, understanding these mandates is critical when evaluating SEP IRA vs solo 401k options.
States with Active Mandates in 2026
As of June 2026, 18 states have implemented or are rolling out retirement plan mandates, including California, Oregon, Illinois, New York, New Jersey, Connecticut, Maryland, Virginia, Colorado, and Washington. Hawaii and Washington State are launching auto-IRA programs in the second half of 2026. Cities including New York City, Seattle, and Philadelphia have also enacted local mandates.
New York’s Secure Choice Savings Program, for example, requires private-sector employers with 10 or more employees to offer retirement benefits. Businesses with 30 or more employees faced a March 18, 2026 deadline, while those with 10 to 14 employees have until July 15, 2026. Non-compliance penalties start at $250 per employee for first offenses and escalate to $1,000 or more per employee for repeat violations.
Why Private Plans Trump State Programs
State-run programs are typically Roth IRA-based with contribution limits capped at the annual IRA maximum. They offer no employer matching and limited investment options. In contrast, a SEP IRA or solo 401(k) provides vastly higher contribution limits, full control over investment choices, and eligibility for SECURE 2.0 tax credits.
For a small business owner in a mandate state, establishing a SEP IRA or solo 401(k) satisfies the compliance requirement while delivering superior retirement savings capacity. Tax professionals should proactively reach out to clients in mandate states to position tax strategy and retirement planning as a compliance solution with significant upside.
Advisory Opportunity for Tax Professionals
State mandates create a natural client touchpoint. Business owners receiving mandate compliance notices are often confused and looking for guidance. By offering a comprehensive comparison of state auto-IRA programs versus SEP IRAs and solo 401(k)s—complete with contribution limit analysis, SECURE 2.0 credit calculations, and multi-year tax projections—tax professionals can convert a compliance headache into a high-value advisory engagement.
This is precisely the type of layered, strategic planning that justifies premium advisory fees rather than commodity tax preparation pricing. Clients facing state mandate deadlines have an immediate problem. Tax professionals who deliver a turnkey solution—plan selection, setup coordination, and ongoing compliance—create sticky, recurring client relationships.
Uncle Kam in Action: Atlanta CPA Delivers $22,000 in Tax Savings
Client Snapshot: Sarah, a 48-year-old fractional CFO operating as a solo LLC in Atlanta, Georgia, earning $185,000 in net self-employment income for 2026.
The Challenge: Sarah had been contributing to a SEP IRA for years but was frustrated by the contribution limits. As her income grew, she wanted to maximize retirement savings while reducing her tax burden. Her previous CPA had simply renewed the SEP IRA annually without exploring alternatives. Sarah was also concerned about Georgia not yet having a state retirement mandate but wanted to future-proof her planning.
The Uncle Kam Solution: Sarah’s new tax advisor, trained through the Uncle Kam platform, conducted a comprehensive SEP IRA vs solo 401k analysis. The advisor modeled her 2026 tax situation under both plans. With the SEP IRA, Sarah could contribute approximately $34,550 (roughly 20% of adjusted net self-employment income). With a solo 401(k), she could contribute $23,000 in employee deferrals plus $34,550 in employer profit-sharing, totaling $57,550.
The advisor walked Sarah through the administrative requirements, explaining that her solo 401(k) would require Form 5500-EZ filing once assets exceeded $250,000, likely in 3 to 4 years at her contribution rate. However, the SECURE 2.0 startup credit would provide up to $5,000 in the first year to offset professional setup and custodian fees. The advisor also designed a Roth solo 401(k) structure, allowing Sarah to designate a portion of employee deferrals as Roth for tax diversification.
The Results:
- Additional Contribution: $23,000 beyond what the SEP IRA allowed
- Federal Tax Savings: $5,520 in year one (at 24% federal bracket), plus ongoing state tax savings
- SECURE 2.0 Credit: $5,000 claimed on Form 8881, covering all setup and first-year admin costs
- Advisory Fee: $2,500 for comprehensive plan design and implementation
- First-Year ROI: 324% return on advisory investment ($8,020 in combined tax savings and credits versus $2,500 fee)
Over five years, assuming consistent income and contributions, Sarah is projected to save an additional $27,600 in federal taxes compared to staying with her SEP IRA, while building a larger retirement nest egg. The advisor also structured ongoing annual reviews at $1,200 per year to optimize contribution timing, monitor Form 5500-EZ requirements, and adjust the Roth versus traditional deferral mix based on Sarah’s evolving tax situation.
Sarah’s case demonstrates how tax professionals who leverage platforms like Uncle Kam’s tax planning software can deliver measurable value that justifies premium pricing. The software’s scenario modeling allowed the advisor to present side-by-side comparisons showing exact contribution limits, tax savings, and administrative costs, turning a complex SEP IRA vs solo 401k decision into a clear, data-driven recommendation. For additional SEP modeling depth, explore our dedicated SEP IRA advisory resource center.
Next Steps
For tax professionals evaluating SEP IRA vs solo 401k options for clients in 2026, the path forward is action-oriented:
- Review the self-employed client roster and identify candidates with income above $100,000 who could benefit from solo 401(k) contributions
- Model contribution scenarios using actual 2026 income projections and verify SECURE 2.0 credit eligibility for new plan setups
- Audit existing SEP IRA clients age 50+ to determine if solo 401(k) conversions would yield material tax savings with catch-up contributions
- Check state retirement mandate deadlines for business owner clients and position private plan setup as a compliance strategy with upside
- Schedule strategy sessions with high-value clients to discuss retirement plan optimization using comprehensive tax modeling
Uncle Kam provides a dedicated SEP IRA strategy toolkit for tax pros that integrates plan analysis, contribution modeling, and client-ready reports into a cohesive advisory workflow.
Frequently Asked Questions
Can a client have both a SEP IRA and a solo 401(k) in the same year?
Not for the same business. If a taxpayer maintains both plans, the annual contribution limits are combined, not stacked. The total across both plans cannot exceed $63,500 for those under age 50 ($70,000 for age 50+), for 2026. However, if a client has two separate businesses with distinct EINs, they could theoretically maintain separate plans for each business, though this requires careful coordination to avoid exceeding overall IRC Section 415 limits.
What happens to a solo 401(k) when the business hires its first employee?
Once a non-spouse employee who works more than 1,000 hours annually is hired, the business can no longer contribute to a solo 401(k). It has three options: terminate the plan and roll assets to an IRA, freeze the plan while establishing a SEP IRA for ongoing contributions, or convert the solo 401(k) to a traditional 401(k) plan with full ERISA compliance. Most small businesses choose option two (freeze solo 401(k), start SEP IRA) to minimize complexity and cost.
Is a SEP IRA better than a solo 401(k) for clients with volatile income?
Not necessarily. While SEP IRAs offer discretionary contributions (0% to 25% in any given year), solo 401(k) employee deferrals are also optional and can be stopped mid-year if income drops. The key advantage of solo 401(k)s for volatile income is the ability to make employee deferrals from each paycheck when cash flow permits, rather than waiting until year-end. For clients with unpredictable revenue, this monthly contribution flexibility can be valuable.
Do solo 401(k) contributions reduce self-employment tax?
No. Solo 401(k) employee deferrals reduce income tax but not self-employment tax. Self-employment tax is calculated on net self-employment income before any retirement plan contributions. This is a common misconception that tax professionals should clarify with clients. However, the income tax savings alone, especially in higher brackets, make solo 401(k)s highly valuable.
Can clients over age 50 make larger SEP IRA contributions?
No. SEP IRAs do not have catch-up contribution provisions. The 25% of compensation limit applies regardless of age. This is a significant disadvantage compared to solo 401(k)s, which allow an additional $7,500 catch-up contribution for those age 50 or older in 2026. For older clients, this catch-up difference alone often justifies choosing a solo 401(k) over a SEP IRA.
How long does it take to set up a solo 401(k) versus a SEP IRA?
SEP IRAs can be set up in under an hour. Most financial institutions offer online account opening with instant approval. Solo 401(k) setup typically takes 1 to 2 weeks, depending on whether a prototype plan from a brokerage firm is used or an ERISA attorney drafts a customized plan. Because solo 401(k)s must be established by December 31 to accept that year’s employee deferrals, clients should start the process no later than mid-November to ensure timely completion.
Are SECURE 2.0 startup credits available for plans established in prior years?
The startup credit is only available for the first three years after establishing a new plan. However, if a client established a plan in 2024 or 2025, they may still be eligible for remaining credit years in 2026. Many tax professionals overlook this credit for existing plans. Reviewing Form 8881 for any client who started a retirement plan within the past three years can reveal unclaimed credits.
Related Resources
- Entity Structuring for Tax Optimization
- Tax Preparation and Filing Services
- The MERNA Method for Strategic Tax Planning
- Free Tax Planning Calculators
- LLC vs S-Corp Tax Calculator for Atlanta small-business clients
Last updated: June, 2026
This information is current as of 6/26/2026. Tax laws change frequently. Verify updates with the IRS or consult a qualified tax professional if reading this later.
Ready to package SEP vs solo 401(k) analysis as a premium advisory offer rather than a one-off client question? Learn how the Uncle Kam marketplace helps tax pros transition to advisory, with MERNA certification, AI-driven strategy workflows, and a steady stream of pre-qualified business-owner leads.
To see how this fits a specific firm, Book a Free Strategy Session with an Uncle Kam growth strategist and get a personalized roadmap for turning retirement-plan consulting into recurring, year-round revenue.

