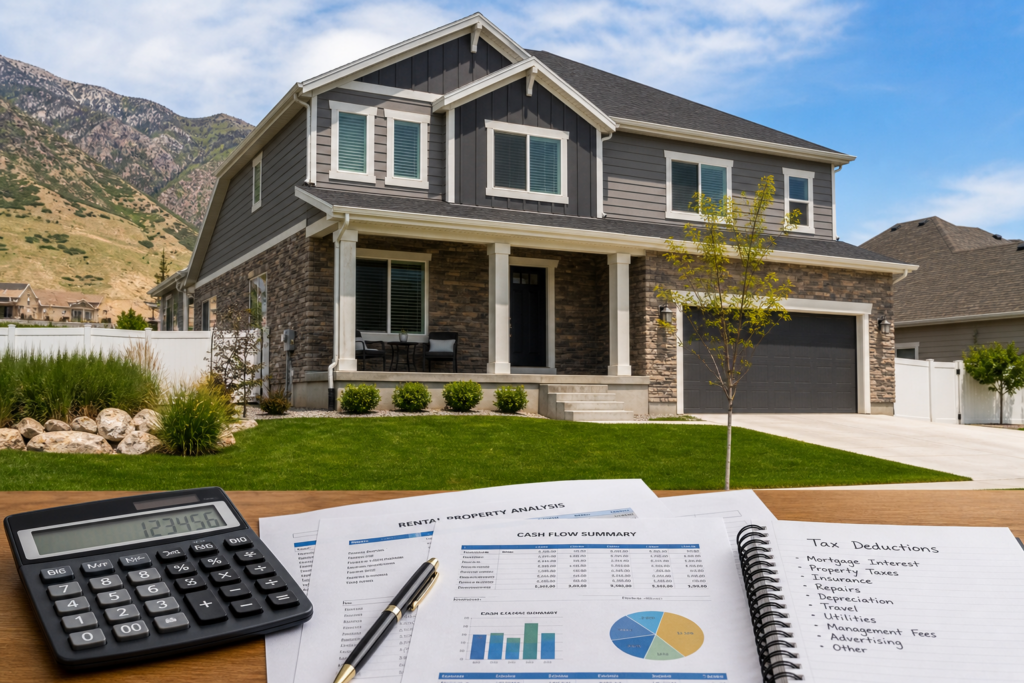
Out-of-State Rental Income in Ogden, Utah: Your 2026 Federal & State Tax Guide for Nonresident Investors
Out-of-State Rental Income in Ogden, Utah: Your 2026 Federal & State Tax Guide for Nonresident Investors
If you own rental properties in Ogden, Utah and live out of state, managing your tax obligations requires careful attention to both federal and state requirements. For the 2026 tax year, nonresident investors must understand how out-of-state rental income in Ogden is reported, which deductions apply, and whether Utah’s favorable tax environment actually benefits your situation. This guide covers everything you need to know about federal Schedule E reporting, depreciation strategies, deductible expenses, and how to optimize your position before the 2026 tax deadline.
Table of Contents
- Key Takeaways
- Do Nonresidents Owe Utah State Income Tax?
- Schedule E Filing Requirements for 2026
- Maximizing Depreciation and Deductions
- What Entity Structure Works Best?
- Estimated Tax Payments for Nonresidents
- Uncle Kam in Action
- Next Steps
- Frequently Asked Questions
Key Takeaways
- Utah does not tax nonresident rental income—you only pay federal taxes for 2026.
- Schedule E reporting is mandatory; rental income is taxed at federal rates up to 37% for 2026.
- Depreciation deductions can shelter significant income for 15+ years on rental properties.
- LLC or S-Corp election may reduce self-employment tax and offer liability protection.
- Quarterly estimated tax payments avoid penalties if you owe over $1,000 in taxes for 2026.
Do Nonresidents Owe Utah State Income Tax?
Quick Answer: No. Utah does not impose state income tax on nonresident rental income sourced within the state. You only owe federal income tax on net rental income for the 2026 tax year.
One of the biggest advantages of owning rental property in Ogden and other Utah locations is that the state has no income tax. This means business owners and real estate investors earning rental income as nonresidents avoid state-level taxation entirely. For 2026, if you own a rental property in Ogden but live in California, New York, Colorado, or any other state, Utah will not tax that rental income.
However, this does not mean you escape taxation. The federal government taxes all U.S. citizens and resident aliens on worldwide income, including rental property income sourced in Utah. Your Ogden out-of-state rental income is fully subject to federal income tax at 2026 rates, which range from 10% to 37% depending on your tax bracket.
Federal vs. State Tax Obligation Comparison
| Tax Jurisdiction | Utah Nonresident Rental Income Obligation |
|---|---|
| Federal Income Tax | Required. File Form 1040 with Schedule E. Taxed at 2026 federal rates (10%-37%). |
| Utah State Income Tax | Not required. Utah has no state income tax on any resident or nonresident income. |
| Your Home State Tax | May be required. Many states tax resident citizens on worldwide income including Utah rentals. |
| Self-Employment Tax | Generally not applicable. Passive rental income does not trigger SE tax (15.3% rate for 2026). |
If you reside in a high-tax state like New York, California, or Illinois, your home state likely taxes your Utah rental income as a resident. Check with your state tax authority to understand whether your nonresident rental income is subject to state-level taxation where you live.
Schedule E Filing Requirements for 2026
Quick Answer: You must file Schedule E with Form 1040 for any rental income or loss from your Ogden property, regardless of how much income you earned or whether you’re out of state.
Schedule E (Part I) is the IRS form used to report rental real estate income and losses for individual taxpayers. For your Ogden out-of-state rental income in 2026, you’ll report the property address, monthly rental income, operating expenses, depreciation, and whether you have a loss.
What Goes on Schedule E for Your Ogden Rental?
- Rental income: All rents received or accrued for 2026 tax year.
- Operating expenses: Property taxes, insurance, repairs, utilities, HOA fees, advertising, property management fees.
- Depreciation: Building depreciation (not land) using Modified Accelerated Cost Recovery System (MACRS).
- Mortgage interest: Deductible on Schedule E; principal payments are not deductible.
- Travel and meals: If you traveled to manage the property or make repairs for 2026.
- Losses: Passive losses may be limited to $25,000 under the passive activity loss rules.
The deadline to file your 2026 tax return with Schedule E is April 15, 2027 (or October 15, 2027 if you file an extension). Late filing incurs penalties of 5% per month of unpaid tax, capped at 25%.
Passive Activity Loss Limitations
Rental properties are generally classified as “passive” activities, meaning losses from the property are subject to passive activity loss (PAL) limitations. For the 2026 tax year, you can typically deduct up to $25,000 in passive losses against nonpassive income if you actively participate in managing the property and your modified adjusted gross income (MAGI) is below $150,000 (single filer).
Pro Tip: If you qualify as a real estate professional under 2026 IRS rules, you may bypass passive activity loss limitations entirely. Consult a tax advisor to determine if this classification benefits your situation.
Maximizing Depreciation and Deductions for Your 2026 Rental
 Free Tax Write-Off Finder
Quick Answer: Depreciation is a noncash deduction allowing you to recover the property’s cost over 27.5 years. Combined with operating expense deductions, depreciation often shelters years of rental income from taxation.
One of the most powerful tax strategies for out-of-state rental property owners is leveraging depreciation. For your Ogden rental, the building (not the land) can be depreciated over 27.5 years using the Modified Accelerated Cost Recovery System (MACRS). This creates a deduction that reduces taxable income without any out-of-pocket expense.
How to Calculate Depreciation on Your Rental
If you purchased your Ogden rental for $400,000 with the land value estimated at $100,000, the depreciable basis is $300,000. Dividing by 27.5 years equals approximately $10,909 in annual depreciation deduction for 2026 and beyond.
- Determine building value by appraisal or assessor’s records (separate from land).
- Divide building value by 27.5 years to find annual depreciation.
- Include depreciation on Form 4562 attached to Schedule E for 2026.
- Accumulate depreciation in a reserve; you’ll recapture this at sale (25% tax rate applies).
Deductible Operating Expenses for Ogden Rentals
Beyond depreciation, you can deduct all ordinary and necessary expenses paid in 2026 to generate rental income. These reduce your net rental income dollar-for-dollar, lowering your taxable income.
| Expense Category | 2026 Deductibility | Example |
|---|---|---|
| Property Taxes | Fully deductible | Utah county property taxes on Ogden rental |
| Insurance | Fully deductible | Landlord’s liability and property insurance premiums |
| Repairs & Maintenance | Fully deductible | Fixing roof leaks, replacing faucets, painting rooms |
| Property Management | Fully deductible | Fee to professional property manager: typically 8-12% |
| Utilities (if landlord-paid) | Fully deductible | Electric, water, gas for common areas |
| Mortgage Interest | Fully deductible | Interest portion of mortgage payments (not principal) |
| Advertising Costs | Fully deductible | Online listing fees, signs, tenant screening services |
| HOA Fees | Fully deductible | Homeowners association monthly or annual fees |
Capital improvements (replacements that add value or prolong asset life) must be depreciated rather than expensed. For example, a new roof costing $15,000 is depreciated over 27.5 years, not deducted immediately in 2026.
What Entity Structure Works Best for Rental Property Ownership?
Quick Answer: For most nonresident rental property owners, an LLC taxed as an S Corp can reduce self-employment tax and provide liability protection. However, individual ownership or a pass-through LLC also works for passive rental income.
How you title and structure your Ogden rental property affects your 2026 tax liability, liability protection, and administrative complexity. Rental income is typically passive (not subject to self-employment tax), so S-Corp election provides limited SE tax savings unless you’re materially involved in operations. Still, using our LLC vs S-Corp Tax Calculator can help model your specific situation.
Entity Structure Comparison for 2026 Rentals
- Individual Ownership (Schedule E): Simplest approach. No entity required. File Schedule E with Form 1040. Limited liability protection.
- LLC (default taxation): Provides liability shield. Income flows to personal return; taxed like sole proprietorship. No self-employment tax on rental income.
- LLC taxed as S Corp: LLC elects S-Corp tax treatment. Can reduce self-employment tax by paying reasonable salary. Adds administrative burden (payroll, Form 1120-S).
- C Corporation: Rare for rentals. Creates double taxation (entity + shareholder). Not recommended unless specific circumstances apply.
For passive out-of-state rental income in Ogden, real estate investors typically benefit most from a simple LLC (taxed as partnership) or individual ownership. The savings from S-Corp election rarely offset the added bookkeeping and tax form complexity for a single rental property.
Estimated Tax Payments for Nonresidents in 2026
Quick Answer: If your 2026 rental income and tax liability exceed your withheld taxes by over $1,000, you must make quarterly estimated tax payments to the IRS to avoid penalties.
Rental income is not subject to tax withholding. If you expect to owe more than $1,000 in federal income tax on your 2026 Ogden rental income (after accounting for other income sources and withholding), the IRS requires quarterly estimated tax payments using Form 1040-ES.
2026 Estimated Tax Payment Dates
- Q1 (Jan-Mar 2026): Due April 15, 2026
- Q2 (Apr-Jun 2026): Due June 15, 2026
- Q3 (Jul-Sep 2026): Due September 15, 2026
- Q4 (Oct-Dec 2026): Due January 18, 2027
Underpayment penalties apply if you fail to pay quarterly estimates or pay too little. For 2026, the underpayment rate is tied to the federal short-term interest rate. Penalties compound quarterly, so timely payment is critical.
Pro Tip: Use safe-harbor rules: pay 100% of your 2025 tax liability (or 90% of 2026 estimated tax) to avoid penalties, even if your final 2026 liability is higher.

Uncle Kam in Action: Colorado Investor Saves $18,500 on Out-of-State Rental Taxes
Sarah, a Denver-based software engineer, purchased a duplex in Ogden for $500,000 in January 2024. She allocated $375,000 to the building and $125,000 to the land. By early 2026, Sarah was earning $48,000 in annual rental income but failing to leverage depreciation or structure her expenses properly.
Her original Schedule E showed $48,000 income minus $8,000 in expenses, leaving $40,000 of taxable income. At Sarah’s 24% marginal bracket, she owed approximately $9,600 in federal tax plus Colorado state tax of roughly $2,200—over $11,800 total for 2026.
After meeting with Uncle Kam tax strategists, Sarah implemented a comprehensive rental property tax plan for 2026. She claimed $13,636 in building depreciation (27.5-year life), increased deductible expenses from $8,000 to $15,200 by tracking repairs, property management fees, and insurance more carefully, and set up quarterly estimated tax payments.
Her revised 2026 Schedule E showed: $48,000 income minus $15,200 in expenses minus $13,636 in depreciation equals $19,164 in taxable income. At her 24% bracket, federal tax dropped to $4,599. Colorado taxes on the reduced income totaled roughly $1,100. Sarah’s total 2026 tax liability for the rental fell to $5,699.
Results: Sarah saved $6,101 in federal and state taxes for 2026, with a first-year return on tax planning fees of over 18:1. Over the 27.5-year depreciation period, her total tax savings on this single rental will exceed $185,000. Visit our client results page for more case studies.
Next Steps
- Gather all 2026 rental income documentation (1099s, lease agreements, tenant payment records) and expense receipts for your Ogden property.
- Calculate your property’s depreciable basis using a professional appraisal or cost-segregation study to maximize depreciation.
- Evaluate whether your home state taxes nonresident rental income and plan for additional state filing/payment obligations.
- Consider working with a tax preparation professional in Utah or your home state to optimize 2026 Schedule E filing.
- Schedule quarterly estimated tax payments before April 15, 2026 to avoid IRS penalties on your 2026 liability.
Frequently Asked Questions
Can I deduct travel expenses to Ogden for rental property management in 2026?
Yes, but only if the trip is primarily for rental business purposes. Deductible expenses include airfare, lodging, meals (50% deductible), and local transportation. Your vacation or personal time is not deductible. Keep detailed records, receipts, and a travel log showing the business purpose and dates spent on rental activities in Ogden.
Is rental income from my Ogden property subject to self-employment tax for 2026?
No, passive rental income is not subject to the 15.3% self-employment tax rate for 2026. You pay ordinary federal income tax (10%-37% brackets) but avoid Social Security and Medicare self-employment taxes. An exception applies if you’re classified as a real estate professional under IRS rules.
What records must I keep for my 2026 Ogden rental property Schedule E filing?
Keep all receipts, invoices, bank statements, and proof of payment for rental income and expenses. The IRS recommends retaining records for at least three years (six years if you underreported gross income by 25%+). Document all rental income deposits, repair receipts, property management invoices, insurance policies, mortgage statements, and depreciation calculations for your 2026 Schedule E.
If I sell my Ogden rental in 2026, how is the gain taxed?
Gain on the sale is taxed as follows: accumulated depreciation is recaptured at 25% tax rate (minimum), remaining gain taxed as long-term capital gain (0%, 15%, or 20% for 2026 depending on income) or short-term capital gain (ordinary income rates up to 37%) if held under one year.
Can I use a 1031 exchange to defer taxes if I sell my Ogden rental in 2026?
Yes. A 1031 exchange (like-kind exchange) allows you to defer capital gains tax indefinitely if you sell your Ogden rental and buy another qualified investment property within strict timelines: 45 days to identify replacement property and 180 days to close. Consult a 1031 intermediary and tax advisor to ensure compliance with 2026 rules.
Does the passive activity loss limitation of $25,000 apply to my Ogden rental for 2026?
The $25,000 annual deduction (for 2026) applies if: you actively participate in rental decisions, you’re not a limited partner, and your modified adjusted gross income (MAGI) is below $150,000 (single) or $200,000 (married filing jointly). Above those thresholds, the limit phases out. Losses above $25,000 carry forward to future years or until the property is sold.
What is depreciation recapture, and will it affect my 2026 taxes?
Depreciation recapture is a tax that applies when you sell a rental property. All accumulated depreciation (deductions taken over the years) is “recaptured” and taxed at 25% minimum, regardless of your ordinary income tax bracket. For example, if you deducted $40,000 in depreciation and sold in 2026, you’d owe at least $10,000 in recapture tax. You do not pay recapture until sale; it does not affect your 2026 return if you still own the property.
This information is current as of June 1, 2026. Tax laws change frequently. Verify updates with the IRS or your tax advisor if reading this later.
Last updated: June, 2026

