Is Rental Property Depreciation Tax Deductible? 2026 Investor Guide
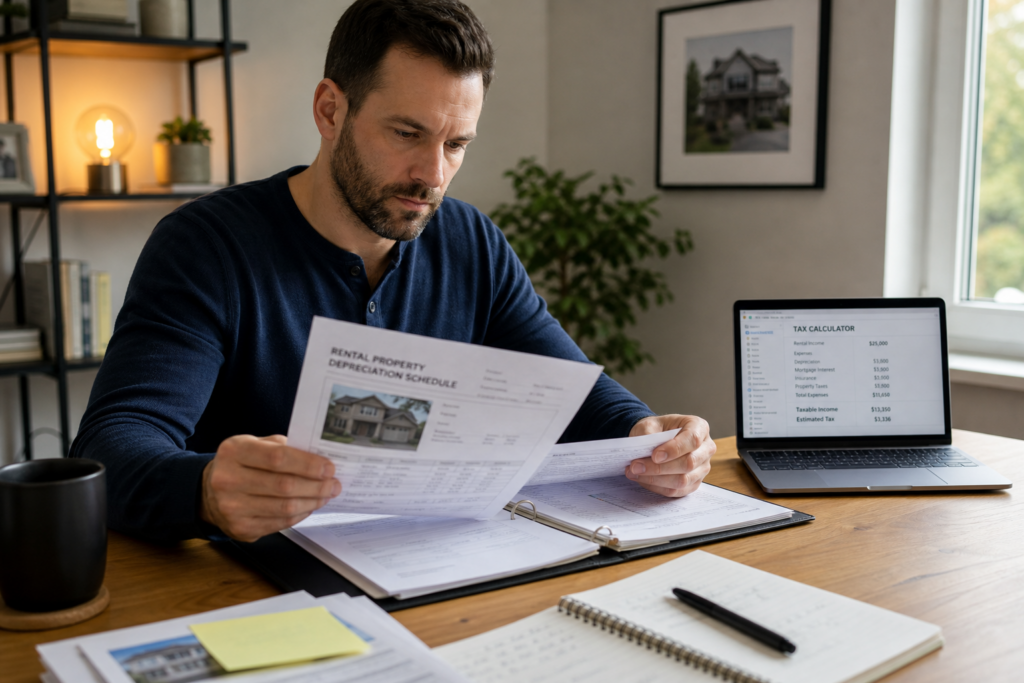
So, is rental property depreciation tax deductible in 2026? Yes, and it remains one of the most powerful write-offs available to property owners. The IRS lets you deduct the cost of a rental building over time. As a result, you can shelter rental income and reduce your taxable profit each year. This guide breaks down the 2026 rules, schedules, and smart strategies.
Table of Contents
- Key Takeaways
- Is Rental Property Depreciation Tax Deductible in 2026?
- How Does Rental Property Depreciation Work in 2026?
- How Do You Calculate Rental Property Depreciation?
- How Much Can You Save With Rental Property Depreciation in 2026?
- What Is Depreciation Recapture When You Sell?
- What Mistakes Should Investors Avoid?
- Uncle Kam in Action
- Next Steps
- Related Resources
- Frequently Asked Questions
Key Takeaways
- Yes, rental property depreciation is tax deductible in 2026.
- Residential rentals depreciate over 27.5 years using straight-line MACRS.
- Land value cannot be depreciated, only the building.
- Depreciation recapture is taxed up to 25% when you sell.
- Cost segregation can accelerate deductions for bigger early savings.
Is Rental Property Depreciation Tax Deductible in 2026?
Quick Answer: Yes. In 2026, the IRS allows you to deduct depreciation on a rental building each year. This reduces taxable rental income.
Depreciation reflects the wear and tear of a building over time. Therefore, the IRS lets you recover the cost as an annual deduction. This makes the question “is rental property depreciation tax deductible” a resounding yes for 2026 investors. Moreover, it is a non-cash deduction, so you save money without spending it. The IRS Publication 527 confirms these rules for residential rental property.
Real estate investors gain a major advantage here. As a result, many profitable properties show a tax loss on paper. Consequently, you can shelter income while your property appreciates. Smart tax planning for real estate investors builds around this benefit.
Who Qualifies for the Deduction?
To claim depreciation, you must own the property and use it to produce income. In addition, the property must have a determinable useful life. Furthermore, you must expect it to last more than one year.
- You own the rental property outright or through an entity.
- You use the property in a rental business or income activity.
- The property has a useful life beyond one year.
Federal vs. State Rules
These depreciation rules apply to federal income tax. However, some states follow different depreciation methods. Therefore, always confirm your state’s treatment before filing. A proactive rental property tax strategy considers both levels.
Pro Tip: Depreciation is not optional. The IRS assumes you took it, even if you did not claim it.
How Does Rental Property Depreciation Work in 2026?
Quick Answer: Residential rentals depreciate over 27.5 years. Commercial properties use a 39-year schedule under MACRS.
The IRS uses the Modified Accelerated Cost Recovery System, or MACRS. For residential rental property, you spread the deduction across 27.5 years. Meanwhile, commercial property uses 39 years. As a result, you deduct a slice of the building’s cost each year. The IRS Publication 946 details how to depreciate property.
Importantly, you can only depreciate the building, not the land. Therefore, you must split the purchase price between land and structure. Working with experienced Tax Strategists in Delaware can help you allocate this correctly and defensibly.
Recovery Periods by Property Type
| Property Type | Recovery Period (2026) | Method |
|---|---|---|
| Residential rental building | 27.5 years | Straight-line |
| Commercial rental building | 39 years | Straight-line |
| Appliances and carpeting | 5 years | MACRS accelerated |
| Land improvements (fences, paving) | 15 years | MACRS accelerated |
When Depreciation Begins
You start depreciating when the property is “placed in service.” This means it is ready and available for rent. Therefore, you do not need a tenant yet. However, the property must be listed and rentable. This distinction matters for first-year investors and their annual tax filing and reporting.
Pro Tip: Use a mid-month convention for real estate. It affects your first-year and final-year deductions.
How Do You Calculate Rental Property Depreciation?
Quick Answer: Divide the building’s cost basis by 27.5 years. This gives your annual residential depreciation deduction.
The formula is simple once you know your cost basis. First, subtract the land value from the purchase price. Then, add closing costs and improvements. Finally, divide by 27.5 for residential property. As a result, you get your yearly deduction.
Step-by-Step Example
Imagine you buy a rental home for $400,000 in 2026. Assume the land is worth $80,000. Therefore, your building basis is $320,000. Here is the calculation:
- Purchase price: $400,000
- Less land value: $80,000
- Building cost basis: $320,000
- Annual depreciation: $320,000 ÷ 27.5 = $11,636
Consequently, you deduct roughly $11,636 each year. This deduction directly offsets your rental income. Over time, it can save thousands in federal taxes.
Accelerating With Cost Segregation
Advanced investors use cost segregation studies. This method reclassifies parts of the building into shorter recovery periods. As a result, appliances and fixtures depreciate over 5 or 15 years. Therefore, you front-load deductions into the early years. Many advanced strategies for high-net-worth investors rely on this technique.
Did You Know? A cost segregation study can shift tens of thousands into your first year of deductions.
You report depreciation on IRS Form 4562 and Schedule E. Accurate records here protect you during any audit.
How Much Can You Save With Rental Property Depreciation in 2026?
Quick Answer: Savings depend on your tax bracket. A $11,636 deduction at 32% saves roughly $3,723 yearly.
Your actual savings depend on your marginal tax rate. Furthermore, passive activity loss rules under Section 469 may limit deductions. However, active participants can often deduct up to $25,000 in losses. This special allowance phases out between $100,000 and $150,000 in modified adjusted gross income.
Fort Smith business owners comparing rental entity structures can use our LLC vs S-Corp Tax Calculator for Fort Smith to estimate 2026 tax savings.
Savings by Tax Bracket
| Marginal Rate (2026) | Annual Deduction | Estimated Tax Saved |
|---|---|---|
| 22% | $11,636 | $2,560 |
| 24% | $11,636 | $2,793 |
| 32% | $11,636 | $3,723 |
| 37% | $11,636 | $4,305 |
Combining With Other Deductions
Depreciation stacks with other rental write-offs. For example, you also deduct mortgage interest, insurance, and repairs. In 2026, new business interest rules use EBITDA calculations. As a result, larger portfolios may claim higher mortgage interest deductions. Meanwhile, the permanent Section 179 limit sits at $2.5 million. A strong tax plan for property business owners coordinates all these deductions.
Pro Tip: Real estate professionals can bypass passive loss limits entirely under IRS rules.
What Is Depreciation Recapture When You Sell?
 Free Tax Write-Off Finder
Quick Answer: When you sell, the IRS recaptures depreciation. It is taxed up to 25% as unrecaptured Section 1250 gain.
Depreciation lowers your basis over time. Therefore, it increases your taxable gain when you sell. The IRS then taxes the depreciation you claimed. This process is called depreciation recapture. Importantly, the recaptured amount is capped at a 25% rate.
However, any profit above your depreciation is taxed at capital gains rates. As a result, recapture only applies to the deductions you took. The IRS capital gains guidance explains these rates in detail.
Recapture Example
Suppose you claimed $60,000 in depreciation over several years. When you sell, that $60,000 faces recapture. At the 25% rate, you would owe up to $15,000. Nevertheless, you still kept the earlier tax savings during ownership.
Deferring Recapture With a 1031 Exchange
You can defer recapture using a 1031 like-kind exchange. This lets you roll proceeds into a new property. Consequently, you postpone both capital gains and recapture taxes. Many investors chain these exchanges for decades. A well-designed entity structure for real estate holdings supports this strategy.
Did You Know? Heirs often receive a stepped-up basis, which can erase deferred recapture entirely.
What Mistakes Should Investors Avoid?
Quick Answer: The biggest mistakes are skipping depreciation, depreciating land, and mislabeling repairs versus improvements.
Many landlords lose money through simple errors. First, some skip depreciation entirely. However, the IRS still recaptures it as if you claimed it. Therefore, always take the deduction you are entitled to.
Common Depreciation Errors
- Depreciating land, which is never allowed.
- Using the wrong recovery period for the property type.
- Expensing improvements that should be capitalized.
- Forgetting to depreciate appliances separately.
Repairs vs. Improvements
This distinction confuses many owners. Repairs are deducted fully in the current year. In contrast, improvements must be depreciated over time. For example, fixing a leak is a repair. However, replacing the roof is an improvement. Guidance from the Nolo legal resource center can help you classify these correctly.
If you also earn freelance or side income, coordinate your rental strategy with your self-employed tax planning approach. Before you finalize your 2026 return, review your allocations with the help of qualified Delaware tax strategists who understand real estate.
Pro Tip: Keep detailed records of every improvement. They increase your basis and reduce future gains.
Uncle Kam in Action: How a Landlord Cut Taxes by $28,000
Client Snapshot: Maria owns a small portfolio of four residential rentals. She works full-time as a marketing consultant. In addition, she manages her properties on evenings and weekends.
Financial Profile: Her rentals generate about $180,000 in gross annual rent. Her combined household income reaches roughly $310,000 for 2026.
The Challenge: Maria took basic straight-line depreciation on all four buildings. However, she never used cost segregation. Furthermore, she misclassified several improvements as repairs. As a result, she overpaid taxes and risked an audit adjustment. She wanted a cleaner, more aggressive but compliant approach.
The Uncle Kam Solution: Our team ordered cost segregation studies on two higher-value properties. Consequently, we reclassified appliances, flooring, and land improvements into 5-year and 15-year buckets. Next, we corrected her repair-versus-improvement classifications. Then, we restructured her entity to strengthen her real estate activity records. Finally, we built a multi-year plan to manage future recapture.
The Results: The accelerated depreciation front-loaded major deductions into 2026. As a result, Maria reduced her taxable income significantly.
- Tax Savings: $28,000 in the first year.
- Investment: $7,500 in Uncle Kam fees and study costs.
- Return on Investment: roughly 3.7x in year one.
Therefore, Maria kept more cash to reinvest. Moreover, she now files with confidence and clean records. You can explore similar outcomes on our documented client results page.
Next Steps
Ready to maximize your 2026 rental deductions? Take these concrete steps now. In addition, connect with a specialist through our real estate tax advisory service.
- Confirm your cost basis and land allocation for each property.
- Evaluate cost segregation for higher-value buildings.
- Review repairs versus improvements from the past year.
- Plan ahead for future depreciation recapture.
- Schedule a 2026 strategy session with our team.
This information is current as of 8/6/2026. Tax laws change frequently. Verify updates with the IRS if reading this later.
Related Resources
- Free Tax Planning Calculators
- Tax Strategy Blog for Investors
- In-Depth Tax Guides Library
- The MERNA Tax Method
Frequently Asked Questions
Is rental property depreciation tax deductible if the property is vacant?
Yes, as long as it stays available for rent. The property must be placed in service. Therefore, a temporary vacancy does not stop depreciation. However, personal use can reduce your deduction.
Can I skip depreciation to avoid recapture later?
No, this is a costly mistake. The IRS recaptures depreciation “allowed or allowable.” Consequently, you owe recapture even if you never claimed it. Therefore, always take the deduction.
How long does residential rental depreciation last in 2026?
It lasts 27.5 years for residential rental property. Commercial property uses 39 years instead. After that, the building is fully depreciated. However, improvements start their own schedules.
What is the depreciation recapture tax rate for 2026?
The recapture rate is capped at 25%. This applies as unrecaptured Section 1250 gain. Meanwhile, gains above depreciation use capital gains rates. A 1031 exchange can defer this tax.
Do passive activity loss rules limit my depreciation?
Sometimes, yes. Passive losses may be limited under Section 469. However, active participants can deduct up to $25,000. This allowance phases out between $100,000 and $150,000 in MAGI.
Is a cost segregation study worth it in 2026?
Often, yes, for higher-value properties. It front-loads deductions into early years. As a result, you improve near-term cash flow. However, the cost must justify the tax benefit.
Last updated: August, 2026