AI Tax Software: 2026 Guide for Tax Professionals
AI tax software is transforming how tax professionals deliver advisory services in 2026. As the IRS commits to a digital-first model and automation becomes essential, tax pros who master AI tools position themselves for higher revenue and better client outcomes. This guide covers everything you need to know.
Table of Contents
Used by 2,400+ tax professionals
- Key Takeaways
- What Is AI Tax Software and Why Does It Matter in 2026?
- How Does AI Tax Software Improve Accuracy and Reduce Errors?
- What Are the Compliance Requirements for AI Tax Software in 2026?
- How Can Tax Professionals Transition to AI-Powered Advisory Services?
- What Are the Cost-Benefit Considerations for AI Tax Software?
- How Does the IRS Digital-First Model Affect Tax Practitioners?
- What Should Tax Pros Look for When Selecting AI Tax Software?
- Uncle Kam in Action: Chicago CPA Firm Transforms Practice with AI Integration
- Next Steps
- Frequently Asked Questions
- Related Resources
Key Takeaways
- AI tax software achieves up to 98% accuracy rates in 2026, significantly reducing manual data entry errors
- The IRS digital-first model requires practitioners to adapt to automated enforcement and streamlined procedures
- Tax professionals using AI tools report 31% time savings, enabling higher-value advisory work
- Circular 230 requires independent verification of all AI-generated tax advice before IRS submission
- Strategic AI implementation transforms compliance practices into profitable advisory relationships
What Is AI Tax Software and Why Does It Matter in 2026?
Quick Answer: AI tax software uses machine learning and automation to process tax returns, identify deductions, and generate client-ready deliverables. In 2026, it has become essential as the IRS shifts to digital-first enforcement and practitioners face increasing pressure to deliver strategic advisory services.
The tax profession is experiencing a fundamental transformation. As of June 2026, the Internal Revenue Service has reduced its workforce from 102,000 employees in early 2025 to approximately 74,000—a 27% reduction concentrated in experienced enforcement and technical staff. According to the National Taxpayer Advocate’s 2025 Annual Report to Congress, this shift has forced the agency to rely more heavily on automation and AI-powered enforcement tools.
For tax advisory professionals, this creates both challenges and opportunities. IRS CEO Frank Bisignano told the Senate Finance Committee on April 15, 2026, that the agency met its filing season targets with “less people and better results” by committing to a digital-first model. Shortly after, the House Appropriations Committee expanded the IRS’s use of AI and data analytics for enforcement.
The Evolution from Compliance to Advisory
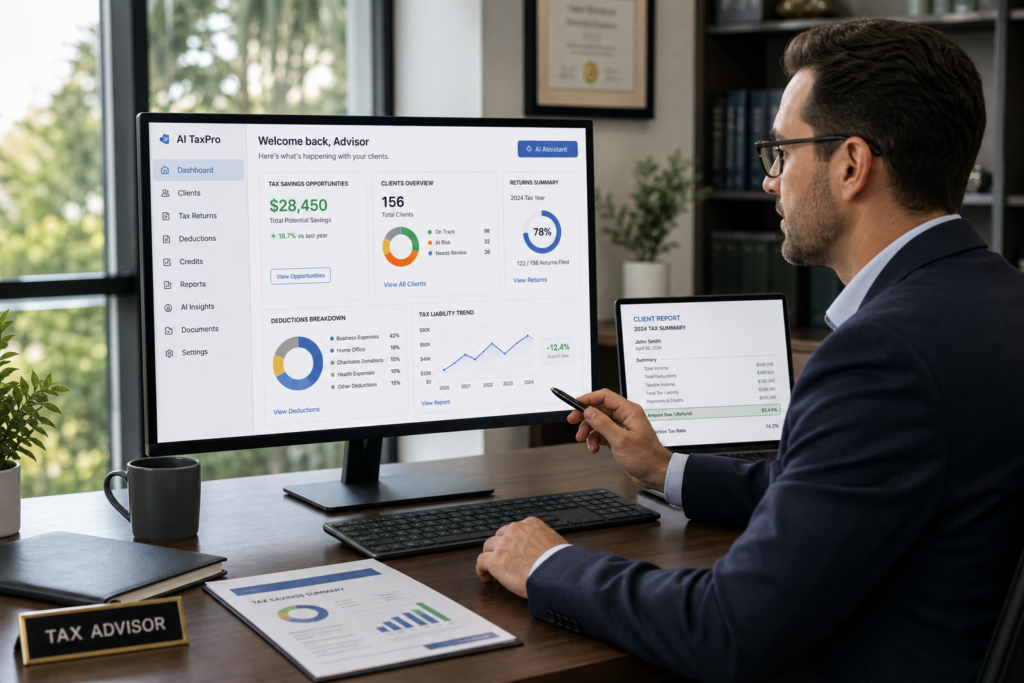
Traditional tax software focused on data entry and form completion. In contrast, AI tax software in 2026 handles the entire workflow from document ingestion to client-ready tax plan generation. This shift allows practitioners to move from transactional compliance work to high-value tax planning and advisory services.
Consider the typical progression. A tax professional historically spent 180 hours during tax season manually preparing returns. With AI automation deployed in 2026, that same professional now spends approximately 15 hours on data verification while the software handles document processing, data extraction, and form population. The freed time redirects to client consultations, strategic planning, and year-round advisory engagements.
Key Capabilities of 2026 AI Tax Software
Modern AI tax software platforms offer several core capabilities that distinguish them from traditional preparation tools:
- Automated document ingestion and optical character recognition for client records
- Intelligent data extraction from non-standardized formats including bank statements and invoices
- Real-time tax law updates reflecting 2026 legislation including OBBBA provisions
- Multi-entity scenario modeling for business owners and real estate investors
- Automated deduction identification based on industry-specific rules and patterns
- Client-ready deliverable generation with strategic summaries and implementation roadmaps
Pro Tip: The most successful AI implementations focus on automating repetitive compliance tasks first, then gradually expanding into advisory workflow automation. This phased approach minimizes disruption while demonstrating ROI quickly.
Legislative Context: The One Big Beautiful Bill Act
The One Big Beautiful Bill Act (OBBBA), signed into law on July 4, 2025, significantly impacts tax planning in 2026. Key provisions include immediate expensing for domestic R&D costs, restoration of 100% bonus depreciation, and the shift from GILTI to Net CFC Tested Income (NCTI) for international structures. AI tax software with current 2026 tax law updates automatically accounts for these changes when calculating provisions and generating recommendations.
For business owners navigating these changes, AI-powered scenario modeling can compare pre- and post-OBBBA strategies instantly. This capability proves particularly valuable for practices serving clients with R&D activities or international operations.
How Does AI Tax Software Improve Accuracy and Reduce Errors?
Quick Answer: AI tax software reduces manual data entry errors from 10-15% to under 2% through automated data extraction, intelligent validation rules, and continuous learning from practitioner corrections. Real-world implementations in 2026 report accuracy rates up to 98%.
Manual tax preparation historically suffers from a 10-15% error rate in data entry alone. These errors range from simple transposition mistakes to misclassified income or overlooked deductions. Each error creates risk—from IRS notices to malpractice claims. Furthermore, error correction consumes significant time during review cycles.
A 2026 case study from accounting firm Thrive Holdings demonstrates the accuracy improvement. During the most recent tax season, they processed 7,000 tax returns directly through AI tax software. The platform achieved 98% accuracy in data entry, compared to the industry standard 85-90% accuracy rate for manual processing. Moreover, the 31% average time savings allowed staff to focus on quality review rather than data entry.
How AI Reduces Common Preparation Errors
AI tax software addresses the most common preparation errors through several mechanisms:
- Optical character recognition eliminates manual transcription from source documents
- Intelligent validation flags inconsistencies across multiple forms and schedules
- Real-time cross-referencing against IRS databases catches common filing mistakes
- Automated calculation verification prevents math errors in complex scenarios
- Pattern recognition identifies missing deductions based on client profile and industry
Self-Learning Systems and Continuous Improvement
The most advanced AI tax software platforms employ machine learning models that improve with use. When a practitioner corrects an error or provides feedback, the system updates its algorithms. OpenAI engineers working with tax software providers now automate this improvement process. Over a single weekend, their Codex system can iterate and test hundreds of different solutions for document parsing challenges.
This continuous improvement capability proves particularly valuable for non-standardized documents. Small business clients often provide bank statements, invoices, and receipts in widely varying formats. An AI system that previously struggled with a specific bank’s statement format can learn the pattern and handle similar documents flawlessly in subsequent processing.
Accuracy Comparison: AI vs. Manual Processing
| Processing Method | Accuracy Rate | Average Time per Return | Review Cycle Time |
|---|---|---|---|
| Manual Data Entry | 85-90% | 4-6 hours | 2-3 hours |
| Traditional Software | 92-95% | 2-4 hours | 1-2 hours |
| AI Tax Software (2026) | 96-98% | 1-2 hours | 30-45 minutes |
Pro Tip: Track your firm’s error rates before and after AI implementation. Document the reduction in IRS notices and client corrections. These metrics become powerful marketing tools when positioning your practice as technology-forward and quality-focused.
What Are the Compliance Requirements for AI Tax Software in 2026?
Quick Answer: Circular 230 Section 10.22 requires practitioners to independently verify all AI-generated tax advice before submitting to the IRS. E-file providers must meet citizenship, age, and licensing requirements. Practitioners cannot rely solely on AI output without exercising due diligence.
The regulatory environment for AI tax software has intensified in 2026. On May 18, 2026, the House passed H.R. 6506, the Taxpayer Due Process Enhancement Act, which strengthens compliance procedures and expands judicial review of tax liability claims. Simultaneously, courts have begun imposing significant sanctions for AI-related errors in legal filings.
AI-related sanctions across U.S. courts totaled approximately $145,000 in the first quarter of 2026 alone. Oregon courts now assess $500 per fabricated citation. In the landmark case Whiting v. City of Athens, Sixth Circuit counsel faced sanctions exceeding $30,000 for fake AI-generated citations. Significantly, approximately 61.6% of federal judges now use AI tools themselves, meaning they can readily identify AI hallucinations and fabrications.
Circular 230 Due Diligence Requirements
Circular 230 Section 10.22 imposes specific due diligence obligations on tax practitioners. These requirements apply regardless of whether the practitioner uses AI tools. When AI software generates a citation, procedural recommendation, or legal analysis, that output constitutes a representation the practitioner intends to rely on. Submitting it to the IRS without independent verification constitutes a Section 10.22 failure.
Section 10.22(b) proves even more pointed. Practitioners may rely on another’s work only by exercising reasonable care in engaging, supervising, training, and evaluating that work. The Office of Professional Responsibility has stated for years this represents an affirmative duty. Willful blindness does not satisfy it. Therefore, practitioners must treat AI tools as junior staff requiring supervision and verification.
E-File Provider Requirements
The Treasury Inspector General for Tax Administration released a report in June 2026 highlighting inadequate vetting of e-file providers. According to the report, several providers received Electronic Filing Identification Numbers (EFINs) despite potentially failing eligibility criteria. The IRS has since tightened requirements.
Responsible officials associated with e-file applications must meet these requirements:
- Be a United States citizen or alien lawfully admitted for permanent residence
- Be at least 18 years of age
- Meet state and local licensing or bonding requirements for tax return preparation
- Submit to fingerprinting if not certified or licensed, ensuring no disqualifying criminal history
- Enroll in FBI continuous monitoring service for ongoing suitability verification
Practitioner Liability for AI Errors
In tax practice, a fabricated authority used to support a return position or representation to the IRS triggers IRC Section 6694 preparer penalties. Additionally, Circular 230 Section 10.51(a)(13) addresses false opinions through gross incompetence. The National Taxpayer Advocate has explicitly warned practitioners not to rely solely on AI-generated tax advice.
The IRS has added misleading AI-generated information to its compliance enforcement focus areas for 2026. Practitioners who submit returns containing AI hallucinations or fabricated citations face potential penalties, sanctions, and professional discipline. Therefore, verification protocols become essential components of any AI implementation.
Pro Tip: Create a documented verification checklist for all AI-generated content. Include specific items like citation verification, calculation review, and current law confirmation. This documentation demonstrates due diligence and protects against potential sanctions.
How Can Tax Professionals Transition to AI-Powered Advisory Services?
Quick Answer: Successful transition requires phased implementation starting with compliance automation, followed by strategic staff training, client communication about enhanced services, and gradual expansion into year-round advisory engagements supported by AI planning tools.
The shift from compliance-focused tax preparation to advisory services represents the most significant opportunity for practitioners in 2026. However, this transition requires careful planning and execution. Firms that attempt wholesale transformation overnight typically encounter staff resistance, client confusion, and operational disruption.
A better approach follows a phased implementation model. Start by automating the most time-consuming compliance tasks. Use the freed capacity to introduce advisory conversations with existing clients. Gradually expand service offerings as staff develops comfort with both the technology and the advisory mindset. Tax strategy planning becomes the foundation for these higher-value engagements.
Phase 1: Compliance Automation Foundation
Begin with the highest-volume, lowest-complexity compliance work. Personal tax returns for W-2 employees represent an ideal starting point. The AI handles document ingestion, data extraction, and form population. Staff focuses on review and quality control. This phase typically runs for one full tax season.
During this period, track specific metrics including time per return, error rates, and client satisfaction scores. Document the time savings and accuracy improvements. These metrics become crucial for both internal buy-in and client communication about enhanced services.
Phase 2: Advisory Conversation Introduction
Once compliance automation stabilizes, redirect saved time to strategic client conversations. Start with existing clients who have complex situations—business owners, real estate investors, or high-income professionals. Use AI-powered scenario modeling to demonstrate potential tax savings opportunities.
For example, a business owner considering S-Corp election can see instant comparisons of salary versus distribution strategies. A real estate investor can model cost segregation benefits against current depreciation schedules. These visual, quantified demonstrations prove far more compelling than abstract advice.
Phase 3: Year-Round Advisory Expansion
The final phase transitions select clients from annual compliance engagements to ongoing advisory relationships. Monthly or quarterly planning sessions replace once-yearly tax preparation meetings. AI tools facilitate this by enabling rapid scenario analysis and plan updates as client circumstances change throughout the year.
This model generates more stable, predictable revenue streams. Instead of seasonal cash flow spikes, firms develop recurring monthly revenue. Moreover, advisory fees typically exceed compliance fees by 2-3 times or more, significantly improving profitability.
Staff Training and Change Management
Staff concerns about AI replacing jobs represent the most common implementation barrier. Address this directly through transparent communication. One accounting director who implemented AI in 2026 held a meeting with junior staff to discuss their concerns. When asked if AI would eliminate their jobs, she explained that AI handles tedious data entry while staff focuses on client relationships and strategic advice.
The results validated this approach. One team member who spent 180 hours on tax returns the previous year spent only 15 hours in 2026. She used the freed time to call clients, discuss planning opportunities, and develop deeper relationships. Her job satisfaction increased significantly, and the firm generated more revenue from her efforts.
Pro Tip: Consider Uncle Kam’s tax planning software with unlimited assessments as your advisory operating system. Unlike competitors that cap usage or charge per analysis, Uncle Kam provides unlimited, free, client-ready tax assessments at every tier, enabling you to demonstrate value to every prospect before engagement.
What Are the Cost-Benefit Considerations for AI Tax Software?
Quick Answer: AI tax software typically costs $200-$500 per user monthly but generates 2-5x ROI through time savings, reduced errors, and advisory service expansion. Firms report 31% average time savings enabling $50,000-$150,000 additional annual revenue per practitioner.
The financial case for AI tax software in 2026 extends beyond simple cost-per-seat analysis. While subscription fees represent the obvious expense, the real value emerges from capacity expansion, error reduction, and advisory revenue opportunities. Forward-thinking firms evaluate AI investments using the same framework they apply to hiring decisions.
Direct Cost Savings Analysis
Consider a mid-size firm with five tax professionals preparing 1,000 returns annually. At an average 4 hours per return using traditional methods, that represents 4,000 billable hours. With 31% time savings from AI automation, the firm recovers 1,240 hours annually—equivalent to 0.6 full-time employees.
That recovered capacity generates value in multiple ways. The firm can serve more clients without additional headcount, expanding revenue without proportional cost increases. Alternatively, practitioners redirect that time to advisory services commanding higher billing rates. A compliance project billing at $150/hour converts to advisory work billing at $250-$350/hour.
Error Reduction and Risk Mitigation
Manual preparation errors cost firms in multiple ways. Direct costs include unpaid time correcting mistakes, responding to IRS notices, and managing client dissatisfaction. Indirect costs encompass reputation damage, lost referrals, and increased malpractice insurance premiums.
By reducing error rates from 10-15% to under 2%, AI software eliminates most of these costs. A firm processing 1,000 returns at a 12% error rate addresses 120 errors annually. At 2 hours per error resolution and $150 billable rate, that represents $36,000 in uncompensated time. AI software eliminating 80% of those errors saves $28,800 annually.
Advisory Revenue Expansion
The most significant financial impact comes from advisory service growth. Firms successfully implementing AI-powered advisory models report dramatic revenue increases. A typical progression follows this pattern:
| Service Model | Average Client Fee | Clients per Practitioner | Annual Revenue per Practitioner |
|---|---|---|---|
| Traditional Compliance Only | $850 | 200 | $170,000 |
| Compliance + Occasional Advisory | $1,450 | 180 | $261,000 |
| Year-Round Advisory Model | $3,200 | 120 | $384,000 |
The advisory model serves fewer total clients but generates significantly higher revenue per practitioner. Moreover, advisory work typically yields higher profit margins because it leverages practitioner expertise rather than time-intensive compliance tasks.
Pro Tip: Calculate your firm’s current effective hourly rate by dividing total revenue by total billable hours. Then compare this to potential rates for advisory services in your market. The gap represents your AI implementation opportunity.
How Does the IRS Digital-First Model Affect Tax Practitioners?
Quick Answer: The IRS digital-first model means faster automated enforcement, enhanced identity theft filters, and increased reliance on data analytics. Practitioners must adapt by implementing stronger verification procedures and leveraging technology to match the agency’s capabilities.
The IRS transformation in 2026 fundamentally changes the practitioner-agency relationship. With workforce reductions concentrating in experienced staff, the agency relies increasingly on automation for both taxpayer service and enforcement. IRS CEO Frank Bisignano’s commitment to a digital-first model signals this shift will accelerate, not reverse.
Enhanced Automated Enforcement
On May 18, 2026, the IRS announced improved identity-theft filters as part of its automation expansion. These filters represent just one component of broader enforcement modernization. The agency now deploys AI and data analytics to identify filing patterns, detect potential fraud, and flag inconsistencies faster than human auditors could accomplish.
For practitioners, this means submissions receive instant automated scrutiny. Returns that deviate from expected patterns trigger immediate review flags. Therefore, documentation quality and supporting evidence become even more critical. The days of relying on low audit rates to protect questionable positions have ended.
Appeals Process Changes
The Independent Office of Appeals lost more than a quarter of its staff during the 2025 workforce reduction. The National Taxpayer Advocate’s Fiscal Year 2026 Objectives Report warns that compliance-oriented performance pressures threaten to turn Appeals into an extension of examination rather than an independent review body.
Practitioners should expect the IRS to bypass Appeals more frequently by issuing statutory notices of deficiency directly. This pushes taxpayers into Tax Court rather than administrative resolution. Therefore, initial filing accuracy becomes paramount. Correcting issues in Tax Court proves far more expensive and time-consuming than getting it right initially.
Congressional Response and Procedural Protections
Congress responded to these changes by passing H.R. 6506 on May 18, 2026. The Taxpayer Due Process Enhancement Act strengthens collection due process protections, safeguards refunds, and expands judicial review of tax liability claims. While the Senate has not yet acted, the legislation signals congressional concern about automated enforcement without adequate procedural protections.
The practical implication for practitioners involves navigating increased automation at the front end while leveraging enhanced procedural rights at the back end. Controversy practitioners sit in the middle of this dynamic, requiring both technological sophistication and deep procedural knowledge.
Pro Tip: Develop a technology stack that matches or exceeds IRS capabilities. If the agency uses AI for enforcement, you need AI for compliance verification. Technology parity becomes a competitive necessity, not a luxury.
What Should Tax Pros Look for When Selecting AI Tax Software?
Quick Answer: Evaluate AI tax software on current 2026 tax law coverage, entity-aware architecture, unlimited assessment capabilities, professional deliverable quality, training and support infrastructure, and built-in practice growth tools including lead generation.
Not all AI tax software delivers equal value. The market in 2026 includes solutions ranging from basic compliance automation to comprehensive advisory operating systems. The right choice depends on your practice goals, client base, and growth strategy. However, certain core capabilities separate professional-grade solutions from consumer-focused tools.
Current 2026 Tax Law Integration
Tax law changes constantly, and 2026 brings particularly significant updates through OBBBA provisions. Your AI software must reflect current law, not outdated rules. Verify that the platform includes immediate R&D expensing, 100% bonus depreciation restoration, and the GILTI to NCTI transition for international planning.
Additionally, confirm regular update cycles. Software that requires manual updates or delays implementation of new rules creates compliance risk. Leading platforms push automatic updates reflecting IRS guidance releases and legislative changes within days of enactment.
Entity-Aware Architecture and Scenario Modeling
Most real estate investors and business owners operate multiple entities. Your software should evaluate the entire portfolio across 1040s, 1120-Ss, and K-1s simultaneously. This entity-aware architecture enables comprehensive planning rather than siloed entity-by-entity analysis.
Robust scenario modeling capabilities prove equally important. Clients want to see side-by-side comparisons of different strategies. The software should generate instant scenarios comparing entity structures, timing strategies, and planning alternatives with complete accuracy.
Unlimited Assessment Capability
Many platforms cap the number of assessments you can run or charge per analysis. This creates a perverse incentive—you hesitate to demonstrate value to prospects because each assessment consumes a costly credit. Look for platforms offering unlimited free assessments.
This capability transforms your sales process. You can run comprehensive assessments for every prospect to prove value before engagement signing. During tax season, you can offer free assessments as value-adds that convert compliance clients to advisory relationships. The economic model aligns with practice growth rather than constraining it.
Professional Deliverable Quality
Clients pay for clarity and professionalism, not spreadsheets. Evaluate the quality of client-facing deliverables the software generates. Do they include strategic summaries explaining recommendations in plain language? Do they provide implementation roadmaps with specific action steps and timelines? Do they assess risk factors and compliance requirements?
The best platforms convert complex scenario modeling into structured, branded deliverables. These documents position you as a strategic advisor rather than a compliance technician. They also justify advisory fees that exceed traditional compliance pricing.
Training and Practice Growth Support
Software alone does not build an advisory practice. You need training on the business of advisory—how to sell, price, market, and scale. Platforms that include structured training and coaching deliver far more value than those providing only software access.
Additionally, consider lead generation capabilities. Some platforms include built-in marketplaces that route pre-qualified advisory opportunities directly to practitioners. This integrated approach addresses the complete practice growth challenge rather than leaving you to figure out marketing independently.
| Feature | Why It Matters | What to Verify |
|---|---|---|
| Unlimited Assessments | Run unlimited prospect demos without per-use costs constraining your growth | No per-assessment fees or usage caps at any tier |
| MERNA Framework | Structured methodology ensures comprehensive planning covering all strategy categories | Software follows repeatable framework, not ad-hoc analysis |
| Entity-Aware Architecture | Evaluates entire client portfolio across multiple entities simultaneously | Handles 1040, 1120-S, and K-1 integration automatically |
| Built-In Marketplace | Solves client acquisition challenge with pre-qualified advisory leads | Platform includes lead routing, not just software tools |
| Advisory Training | Teaches the business of advisory, not just tax strategies | Live coaching on pricing, selling, and scaling included |
Pro Tip: Test the software with your own tax scenario before committing. The best platforms offer trial periods or demo accounts. Run a complete analysis and evaluate both the process and the deliverable quality against your standards.
Uncle Kam in Action: Chicago CPA Firm Transforms Practice with AI Integration
Client Profile: Mitchell & Associates, a 12-person CPA firm in Chicago serving primarily small business owners and real estate investors, had plateaued at $1.8 million in annual revenue. The firm’s partners recognized they were trapped in a compliance cycle—busy during tax season but struggling to generate revenue during the rest of the year. They needed to transition to year-round advisory services but lacked the tools and framework to make it happen.
The Challenge: Partner Sarah Mitchell explained their situation: “We were working 70-hour weeks during tax season and then scrambling for work in summer. Our clients saw us as once-a-year tax preparers, not strategic advisors. We knew advisory was the future, but we didn’t know how to make the transition without disrupting our existing practice or losing clients.”
The firm faced specific obstacles including staff concerns about AI replacing jobs, client hesitation about paying advisory fees, and lack of structured processes for delivering advisory services. Additionally, they struggled with inconsistent service delivery—different staff members provided different advice for similar client situations.
The Uncle Kam Solution: Mitchell & Associates implemented Uncle Kam’s advisory operating system in September 2025, giving them a full year to transform their practice before the 2026 tax season. The firm started with Phase 1 compliance automation for their highest-volume individual returns. By January 2026, they had freed approximately 400 hours of staff time through AI-powered data processing.
During Phase 2, the firm used Uncle Kam’s unlimited assessment capability to run free tax analyses for existing business clients. These assessments identified an average of $18,500 in potential annual tax savings per client. The firm positioned these findings as the foundation for year-round advisory engagements at $3,500 per client annually.
The MERNA framework provided the structure they previously lacked. Every client received consistent, comprehensive planning covering Maximize deductions, Entity structure, Retirement planning, Niche strategies, and Advanced techniques. Staff no longer relied on individual knowledge—the system guided them through complete analysis every time.
The Results: By June 2026, Mitchell & Associates had transformed their practice model and financial performance:
- Tax Savings Delivered: $847,000 in total client tax savings across 47 advisory clients
- Advisory Revenue: $164,500 in new advisory fees (47 clients × $3,500 average)
- Investment: $24,000 in Uncle Kam software and training fees
- First-Year ROI: 585% ($164,500 revenue on $24,000 investment)
- Staff Satisfaction: Zero turnover during the transition, up from 25% annual turnover previously
Sarah Mitchell summarized the transformation: “Uncle Kam didn’t just give us software—they gave us a complete business model for advisory services. The unlimited assessments let us prove value to every prospect. The structured framework ensured consistent quality. And the training taught us how to price, sell, and deliver advisory services profitably. Our practice is now positioned for sustainable growth, not just seasonal chaos.”
The firm’s success attracted attention from other practitioners. Mitchell & Associates now mentors other firms through the advisory transition, further establishing their market authority. They project reaching $2.4 million in revenue by year-end 2026—a 33% increase driven entirely by advisory service expansion.
For more transformational stories like this, visit Uncle Kam’s client results page to see how tax professionals across the country are building more profitable, sustainable practices through strategic advisory services.
Next Steps
Ready to transform your tax practice with AI-powered advisory services? Follow these action steps:
- Audit your current practice model to identify time spent on compliance versus advisory work
- Calculate your potential revenue increase using the advisory model financial projections above
- Research AI tax software options focusing on the evaluation criteria covered in this guide
- Book a strategy session at Uncle Kam’s strategy session portal to discuss your specific practice transformation goals
- Review entity structuring strategies to understand how AI tools enhance this high-value service
Frequently Asked Questions
Will AI tax software replace tax professionals?
No, AI tax software replaces tedious data entry and compliance tasks, not professional judgment and client relationships. The technology handles document processing and form population, freeing practitioners to focus on strategic advisory services. In 2026, successful firms use AI to enhance their capabilities and deliver higher-value services, not as a replacement for professional expertise. The human element—understanding client goals, explaining complex strategies, and providing trusted guidance—remains essential and irreplaceable.
How long does AI tax software implementation typically take?
Most firms achieve basic operational status within 30-60 days, but full advisory transformation typically requires 6-12 months. The phased approach allows gradual adoption starting with simple compliance automation, then expanding to advisory services. Firms that implement in fall have the entire off-season to build competency before the following tax season. Therefore, September through November represents the ideal implementation window for most practices.
What happens if the AI generates incorrect tax advice?
Practitioners remain professionally responsible for all advice provided to clients regardless of AI involvement. Circular 230 requires independent verification of AI-generated content before submission to the IRS. Consequently, firms should implement verification checklists covering citation validation, calculation review, and current law confirmation. Document this verification process to demonstrate due diligence. Leading AI platforms achieve 98% accuracy, but the remaining 2% requires professional oversight. Think of AI as a highly capable junior staff member who still needs supervision.
Can AI tax software handle complex multi-entity structures?
Advanced AI tax software with entity-aware architecture can evaluate complex structures including multiple LLCs, S-Corps, partnerships, and holding companies. The software should automatically calculate K-1 distributions, consolidated scenarios, and entity-level planning strategies. However, not all platforms offer this capability. When evaluating software, specifically test multi-entity scenarios representative of your client base. Request demonstrations showing how the platform handles real estate investors with multiple rental properties or business owners operating through holding company structures.
How do I justify advisory fees to compliance-only clients?
Use AI-powered assessments to demonstrate quantifiable value. Run a comprehensive tax plan showing specific dollar savings opportunities. For example, show a business owner how S-Corp election could save $12,000 annually in self-employment taxes. Then position your $3,500 advisory fee as generating 3.4x ROI in year one alone. The key involves moving from abstract advice to concrete, quantified recommendations. Clients readily pay advisory fees when you demonstrate multiple times return on investment. Platforms offering unlimited free assessments enable you to prove this value before asking for engagement commitments.
What training do staff members need for AI tax software?
Staff need technical training on the software itself plus business training on advisory service delivery. Technical training covers software navigation, data input procedures, and quality control processes. Business training addresses client communication, advisory sales conversations, and engagement management. The most successful implementations provide both types of training. Additionally, address staff concerns about job security directly and transparently. Explain how AI handles tedious work while staff focuses on higher-value client interactions. Firms report that once staff experience the benefits firsthand, resistance typically transforms into enthusiasm.
Does AI tax software stay current with changing tax laws?
Professional-grade AI tax software includes automatic updates reflecting IRS guidance and legislative changes. For 2026, this means immediate incorporation of OBBBA provisions including R&D expensing changes and bonus depreciation restoration. However, update frequency varies by provider. Leading platforms push updates within days of new guidance releases. Others may lag by weeks or months, creating compliance risk. When evaluating software, ask specifically about the 2026 OBBBA updates and verify the platform correctly implements Net CFC Tested Income calculations and Foreign-Derived Deduction Eligible Income provisions.
How does AI tax software integrate with existing practice management systems?
Integration capabilities vary significantly across platforms. Some offer native integrations with popular practice management systems, enabling seamless data flow between applications. Others require manual data transfer or custom API development. Evaluate integration requirements during software selection based on your existing technology stack. Additionally, consider whether AI tax software can serve as your primary planning platform, potentially reducing the total number of systems you maintain. Comprehensive platforms combining tax planning, client communication, and deliverable generation may simplify your technology environment rather than adding complexity.
Related Resources
- Advanced Tax Strategy Planning for 2026
- The MERNA Method: Structured Tax Planning Framework
- Tax Preparation and Filing Best Practices
- Business Automation and Financial Systems
- Self-Employed Tax Strategies and Planning
Last updated: June, 2026
This information is current as of 6/5/2026. Tax laws change frequently. Verify updates with the IRS or relevant tax authorities if reading this later.
Ready to plug into the complete AI-powered advisory system?
Uncle Kam equips tax professionals with MERNA-certified training, AI planning software, and a built-in marketplace of pre-qualified advisory clients. Instead of stitching together tools and hoping they work, practitioners step into a proven blueprint for scaling advisory.
Learn how the Uncle Kam marketplace helps tax pros transition to advisory using AI-driven tax strategy, client-ready deliverables, and a repeatable planning framework.
To map this directly onto your own firm, Book a Free Strategy Session with an Uncle Kam growth strategist. Get a customized roadmap for implementing AI tax software, packaging advisory services, and building predictable, year-round revenue.