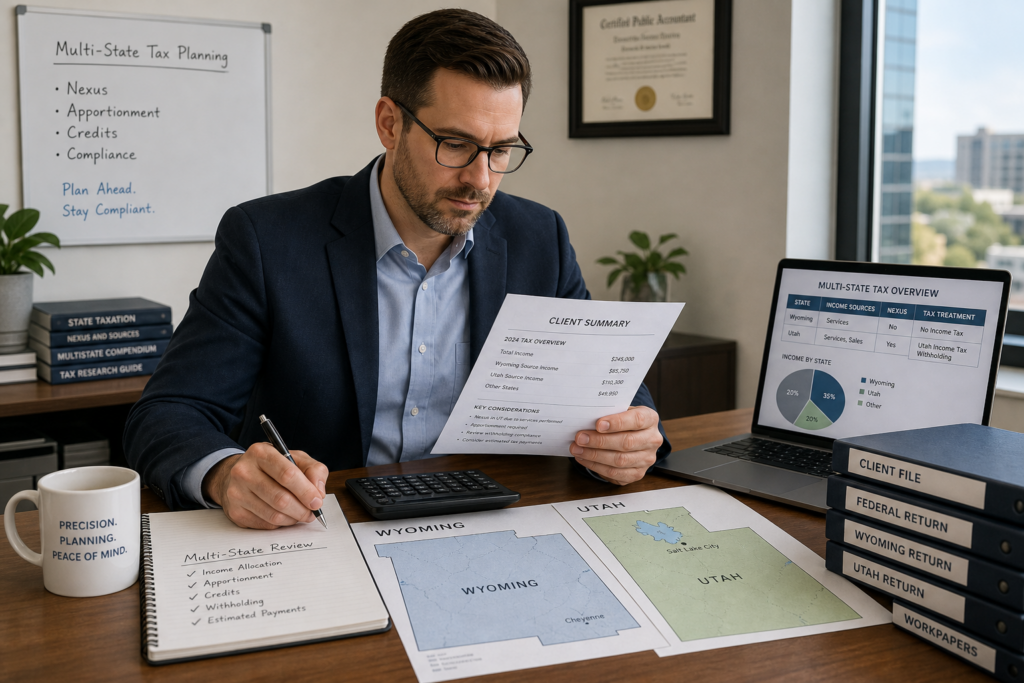
Working in Wyoming, Living in Utah: 2026 Tax Strategy Guide for Multi-State Earners
Working in Wyoming, Living in Utah: 2026 Tax Strategy Guide for Multi-State Earners
When you work in Wyoming but live in Utah, tax planning becomes critical. Wyoming’s lack of state income tax creates a unique advantage, but Utah’s residency rules mean you cannot ignore your home state’s filing obligations. Whether you’re a remote worker, business owner, or employee earning income from a Wyoming source while maintaining a Utah residence, understanding how these two states tax your income is essential. Our tax preparation services in Wyoming specialize in multi-state scenarios exactly like yours, helping business owners and self-employed professionals structure their income to take full advantage of both states’ tax rules.
Table of Contents
- Key Takeaways
- Understanding Multi-State Tax Residency
- How Do Multi-State Income Rules Apply to Wyoming-Utah Workers?
- What Are Your 2026 Utah Filing Requirements?
- Can You Claim Multi-State Deductions and Credits?
- Uncle Kam in Action
- Next Steps
- Frequently Asked Questions
Key Takeaways
- Wyoming has zero state income tax, but Utah taxes residents on all income sources, including Wyoming wages.
- Your residency status determines which state can tax your earnings; proper documentation of Utah residency is critical.
- For 2026, Utah filers use federal standard deductions and can claim additional state credits unavailable in Wyoming.
- Multi-state workers may qualify for tax credits, retirement savings incentives, and deductions that significantly reduce liability.
- Filing deadlines, estimated payment schedules, and quarterly requirements differ between states and federal obligations.
Understanding Multi-State Tax Residency: Wyoming vs. Utah
Quick Answer: If you live in Utah and work in Wyoming, Utah will tax your Wyoming income. Wyoming cannot tax it because Wyoming has no income tax. You must file both federal and Utah state returns.
Residency is the foundation of multi-state taxation. When working in Wyoming but living in Utah, your home state status matters most. Utah considers you a resident if you maintain a permanent home in the state, regardless of where your income originates. This means your Wyoming employment income is subject to Utah state income tax.
Wyoming’s Zero Income Tax Advantage
Wyoming stands alone as one of nine states with no individual income tax. This is a permanent feature of Wyoming tax law, not subject to change. For workers earning income in Wyoming, this creates a direct benefit. However, that benefit only applies if you are actually a Wyoming resident. If you live in Utah, even though you work in Wyoming, the income is sourced to Wyoming but taxed by Utah. Understanding source income versus residency is critical for multi-state workers.
How Utah Determines Your Residency Status
Utah uses a “permanent home” test. If you maintain a permanent home in Utah where you live, even if you work elsewhere, you are presumed to be a Utah resident. The Utah State Tax Commission considers factors like where you own or rent property, where your family lives, where you maintain a driver’s license, and where you register vehicles. These factors collectively determine residency. For the 2026 tax year, if you meet Utah’s residency criteria, you must file a Utah state tax return reporting all income earned in Wyoming.
How Do Multi-State Income Rules Apply to Wyoming-Utah Workers?
Quick Answer: Wyoming cannot tax your income because it has no income tax. Utah taxes you as a resident on all income. Use our small business tax calculator to estimate your 2026 combined federal and Utah state liability based on your Wyoming earnings.
Multi-state taxation operates on two key principles: source and residency. Income is sourced to the location where you perform the work or where services are rendered. Residency determines which state has the right to tax all your income. When working in Wyoming but living in Utah, you face a unique situation. Wyoming has no income tax, so it cannot tax your wages, self-employment income, or business profits earned there. Utah, as your state of residency, can tax that same income because you live in the state.
Source Income vs. Residency for Wyoming Workers
This distinction is crucial for tax planning. All income earned in Wyoming (W-2 wages, 1099 contractor payments, self-employment income from a Wyoming business) is source income to Wyoming. However, because Wyoming has no income tax, that source income escapes Wyoming taxation entirely. Simultaneously, because you reside in Utah, the Utah State Tax Commission asserts the right to tax that same income. You are not double-taxed; instead, you pay Utah tax on Wyoming-sourced income while Wyoming collects nothing.
For 2026, this means your federal tax obligations remain unchanged—you pay federal income tax on all worldwide income regardless of source or residency. Your Utah tax obligation covers all income, including wages earned in Wyoming. The benefit comes from avoiding Wyoming income tax entirely, which is a meaningful advantage compared to workers earning the same income in Utah.
Self-Employment and Business Income Rules
If you operate a self-employed business or independent contractor practice in Wyoming while living in Utah, multi-state rules apply differently than W-2 employment. Business income is typically sourced to where the business is located and where management decisions are made. A Wyoming business earns Wyoming-source income. As a Utah resident, you report that income on your Utah return but receive credit for Wyoming taxes paid—except Wyoming imposes zero taxes. This creates a pure Utah tax liability on your business income from Wyoming sources.
Pro Tip: Self-employed workers earning Wyoming-source income benefit from filing Form 1040-ES for federal estimated taxes and tracking Utah estimated payment schedules separately. Quarterly payments typically align but must be calculated using each jurisdiction’s applicable rates and methods for 2026.
What Are Your 2026 Utah Filing Requirements?
 Free Tax Write-Off Finder
Quick Answer: If you’re a Utah resident in 2026 with Wyoming income exceeding Utah’s filing threshold, you must file both federal Form 1040 and Utah’s income tax return by April 15, 2027.
For the 2026 tax year, Utah requires residents to file state income tax returns if their gross income exceeds specific thresholds. Your Utah filing obligation applies to all income—federal, state, and local sources combined. Wyoming-sourced income counts toward Utah’s filing threshold. If your total 2026 income from all sources (W-2, 1099, self-employment, investment income) exceeds Utah’s minimum threshold, you must file a Utah state return even if federal filing requirements might suggest otherwise.
Utah Filing Deadlines and Extension Options
Utah income tax returns for 2026 are due April 15, 2027, matching the federal deadline. If you file a federal extension (Form 4868), your Utah return is automatically extended to October 15, 2027. Estimated payment deadlines for 2026 occur quarterly: April 15, June 15, September 15, and January 15, 2027. These dates are fixed regardless of weekends or holidays. For workers with variable income from Wyoming sources, tracking estimated tax payments becomes complex. Many multi-state earners underpay estimated taxes early in the year, then scramble to catch up later when earnings increase.
Required Forms and Documentation for 2026
Utah requires specific forms for multi-state filers. You will receive a W-2 from your Wyoming employer reporting your wages and withholdings. You must file Utah Form TC-40, Utah’s individual income tax return. If you are self-employed, you also file Schedule C with your federal return and report self-employment tax on Schedule SE. Utah’s Form TC-40 line items align closely with federal Form 1040, making the process straightforward for most taxpayers. However, multi-state workers often overlook Utah credits, deductions, or requirements specific to their situation.
Can You Claim Multi-State Deductions and Credits?
Quick Answer: Yes. Utah-specific deductions, retirement savings credits, and family-based credits can reduce your 2026 Utah tax liability on Wyoming income. Wyoming offers no state credits because it has no income tax.
Multi-state workers often leave money on the table by missing state-specific deductions and credits. Utah offers several opportunities for workers earning income from Wyoming sources. Understanding what you can claim on your 2026 Utah return is essential to tax optimization for this scenario.
Retirement Savings Contributions and Education-Related Credits
If you contribute to a traditional IRA or 401(k), you can deduct those contributions on your federal return. For 2026, the 401(k) employee deferral limit is $24,500, with an additional $8,000 catch-up contribution allowed for participants age 50 and older. These deductions reduce your federal taxable income and often reduce your state taxable income as well. Utah recognizes federal above-the-line deductions for IRA and retirement plan contributions, so claiming the maximum retirement savings reduces both your federal and Utah tax liability. Multi-state workers with Wyoming income should maximize retirement contributions because they reduce Utah taxes on that same income.
Utah also offers education-related credits and deductions for families with college students or those pursuing higher education. If you have dependent children in college or trade schools, Utah 529 education savings plan contributions may provide additional benefits when coordinated with federal plan benefits. These state-level benefits apply to all income, including Wyoming-source earnings.
Child, Dependent, and Family Tax Benefits
The federal Child Tax Credit and Earned Income Tax Credit apply to all income-earning parents, regardless of state. Utah also recognizes these federal credits on its state return. If you earn Wyoming income as a single parent or head of household with dependents, both federal and Utah tax liability decrease based on your dependent status and income level. For 2026, claiming each qualifying child reduces your federal liability by $2,000 per child and may provide state-level benefits as well.
| Tax Benefit | 2026 Status | Impact on Wyoming-Utah Filers |
|---|---|---|
| Federal 401(k) Deferral Limit | $24,500 (+ $8,000 catch-up, age 50+) | Reduces federal and Utah income; available to all workers with W-2 or self-employment income |
| Federal Child Tax Credit | $2,000 per qualifying child | Applies to all families with dependents; recognized by Utah on state returns |
| Earned Income Tax Credit (EITC) | Up to $3,995 (varies by filing status and income) | Federal credit; Utah recognizes federal EITC on state returns for eligible workers |
| Utah Standard Deduction (Federal Base) | Varies by filing status (2026 amounts pending IRS announcement) | Utah uses federal standard deduction; reduces taxable income in both jurisdictions |
Did You Know? Multi-state workers filing in Wyoming and Utah can claim the same federal deductions and credits on both returns. The difference is that Wyoming has zero tax, so claims there are moot. Utah, however, applies those same claims to reduce your state liability, making tax optimization more valuable than for purely Utah-based workers.

Uncle Kam in Action: Wyoming-to-Utah Multi-State Tax Savings
Client Profile: Sarah is a 38-year-old marketing consultant living in Salt Lake City, Utah. She operates a sole proprietorship registered in Cheyenne, Wyoming, where she bills clients and performs most of her project management. Her Wyoming business generates $180,000 in annual revenue. Sarah maintains a home in Utah where she lives with her two school-age children. She has been filing both federal and Utah state returns but was unsure whether she was optimizing her multi-state situation.
The Challenge: Sarah reported her Wyoming business income on her Utah return but was not claiming all available deductions and credits specific to Utah’s tax code. She was contributing to a SEP-IRA but not maximizing her retirement savings strategy given her business structure. Additionally, she was making estimated tax payments but not timing them optimally across federal and state requirements. Her annual federal and state combined tax liability was approximately $38,000, but she suspected she was paying more than necessary.
The Uncle Kam Solution: We restructured Sarah’s retirement strategy by recommending she establish a Solo 401(k) instead of a SEP-IRA. For 2026, she can now contribute $24,500 as an employee plus approximately $35,000-$40,000 as an employer (based on her business profit), totaling roughly $60,000 in retirement savings annually. This deduction directly reduces her federal taxable income and her Utah taxable income proportionally. Additionally, we identified Utah education credits for her two children pursuing post-secondary education, worth approximately $2,400 in combined credits. We also optimized her estimated tax payment schedule to avoid underpayment penalties while reducing her overall 2026 liability.
The Results: By optimizing retirement contributions (tax savings: $14,400 from increased deductions), claiming applicable Utah education and dependent credits (tax savings: $2,400), and structuring estimated payments correctly (eliminating $600 in underpayment penalties), Sarah’s annual combined federal and state tax liability dropped from $38,000 to $20,600—a first-year return on investment of 457% on our planning fee. More importantly, her optimized structure will save her an estimated $17,400 annually going forward.
Visit our client results page to see more case studies of multi-state tax optimization.
Next Steps for Wyoming-Utah Multi-State Filers
If you work in Wyoming but live in Utah, take these immediate actions to optimize your 2026 tax situation:
- Confirm your Utah residency status with documentation. Gather proof of permanent home, driver’s license, vehicle registration, and family residence to ensure proper filing status.
- Review your current retirement structure. If you’re self-employed, evaluate whether a Solo 401(k) or other strategy offers more savings than your current plan.
- Identify all available credits and deductions for Utah. Family credits, education benefits, and dependent claims should all be verified on your 2026 return.
- Schedule quarterly estimated payments correctly for both federal and Utah obligations. Our tax strategy team can help align payment schedules and avoid penalties.
- Consult with a multi-state tax specialist. Multi-state taxation is complex, and errors cost money. Professional guidance typically pays for itself many times over.
For personalized guidance on your specific Wyoming-to-Utah tax situation, connect with our tax advisory team today. We specialize in helping business owners and self-employed professionals navigate multi-state tax obligations while maximizing their after-tax income.
Frequently Asked Questions
Do I have to file a Wyoming tax return if I work in Wyoming but live in Utah?
No. Wyoming has no individual income tax, so there is no Wyoming tax return to file regardless of whether you work there. You file only federal and Utah returns (if your income exceeds Utah’s filing threshold). Wyoming will never send you a tax bill, and you have no obligation to the state for income tax purposes.
Can I claim any Wyoming tax credits or deductions?
Wyoming offers no individual income tax credits or deductions because it imposes no income tax. All tax planning benefits come from federal deductions and credits, plus Utah state-specific benefits available to Utah residents. Multi-state workers benefit from avoiding Wyoming taxes entirely and then optimizing their Utah liability through strategic use of deductions and credits.
What if I move from Utah to Wyoming mid-year in 2026?
If you change residency during 2026, you become a part-year resident of both states. You must file as a Utah part-year resident for the portion of the year you lived there. Your Wyoming-source income earned while you were a Utah resident is taxed by Utah. Income earned after you become a Wyoming resident escapes income tax entirely (since Wyoming has no income tax). This actually makes the late-year transition to Wyoming very beneficial from a tax perspective.
Are estimated tax payments required for Wyoming-Utah multi-state workers in 2026?
Yes. You must make federal estimated tax payments (Form 1040-ES) quarterly on April 15, June 15, September 15, and January 15. Utah also requires estimated payments if you anticipate owing more than a certain threshold. Most W-2 employees avoid estimated payments if their employer withholds correctly, but self-employed workers earning Wyoming-source income must pay estimated taxes to both federal and Utah authorities. Underpayment penalties apply if you miss deadlines.
Can I reduce my Utah tax by claiming Wyoming taxes paid?
No, because Wyoming imposes zero income tax. You cannot claim taxes you did not pay. Utah’s tax credit system allows residents to claim taxes paid to other states, but this benefit only applies if the other state actually imposed and collected a tax. Since Wyoming collected nothing on your income, there is no credit to claim. This unique situation—earning income in a no-income-tax state while residing in a tax state—means you pay the full Utah tax with no offset.
What documentation do I need to prove I’m a Utah resident for tax purposes?
The Utah State Tax Commission uses objective tests: a Utah driver’s license or ID, vehicle registration in Utah, ownership or rental of a permanent home in the state, and evidence of family residence in Utah. Gather these documents before filing your 2026 return. If the tax commission ever questions your residency claim, these documents support your position. Multi-state workers should maintain clear proof of their home state residency, especially if they spend significant time working in other states.
This information is current as of 6/1/2026. Tax laws change frequently. Verify updates with the IRS and Utah State Tax Commission if reading this after mid-2026.
Related Resources
- Tax Preparation Services in Wyoming
- Tax Strategies for Business Owners
- Self-Employed Tax Planning and Filing
- Multi-State Entity Structuring Solutions
- 2026 Tax Deadline Calendar
Last updated: June, 2026

