
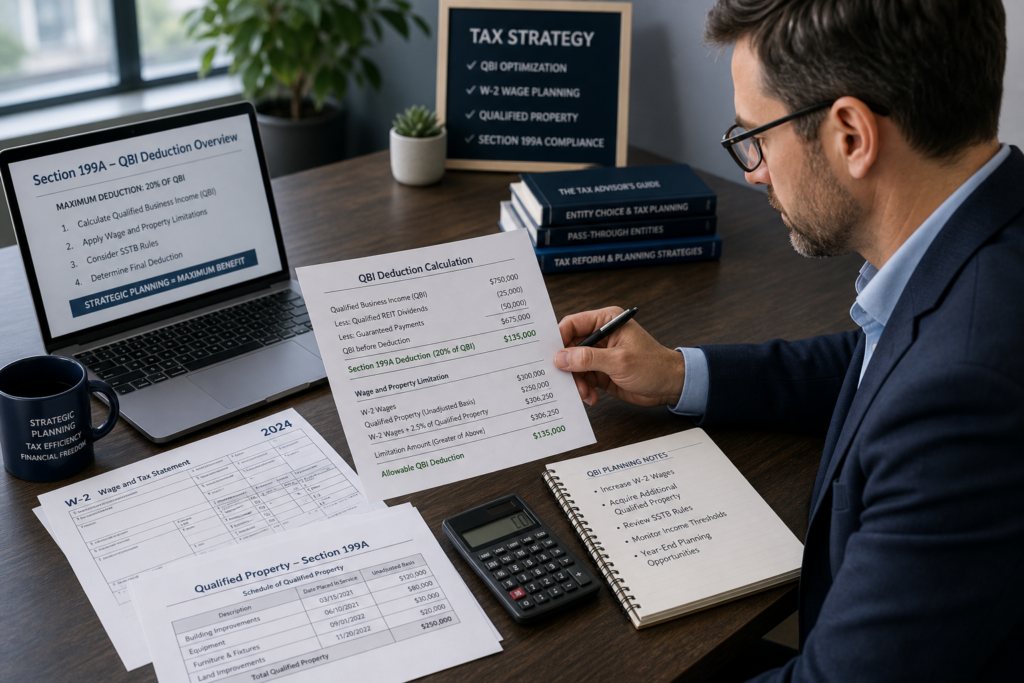
QBI W-2 Wage Limitation Planning for 2026
For the 2026 tax year, strategic tax planning around the QBI deduction W-2 wage limitation requires technical precision. Business owners depend on tax professionals to navigate Section 199A’s complex phase-in ranges and wage-based limitations. Understanding how W-2 wages impact the 20% qualified business income deduction is essential for delivering measurable client value.
Table of Contents
Used by 2,400+ tax professionals
- Key Takeaways
- What Is the QBI W-2 Wage Limitation?
- When Does the W-2 Wage Limitation Apply to Your Clients?
- How Do Tax Professionals Calculate the W-2 Wage Limitation?
- What Planning Strategies Maximize the QBI Deduction Despite Wage Limits?
- How Does Entity Structure Affect W-2 Wage Limitations?
- What Are Common Mistakes Tax Professionals Must Avoid?
- Uncle Kam in Action: Manufacturing Client Saves $47,000
- Next Steps
- Frequently Asked Questions
- Related Resources
Key Takeaways
- QBI deduction W-2 wage limitation planning affects high-income business owners above threshold amounts
- Tax professionals use two calculation methods: 50% of W-2 wages or 25% plus 2.5% of property basis
- Proactive year-end wage adjustments and entity restructuring preserve deduction value for 2026
- Documentation of W-2 wages and unadjusted basis of qualified property is mandatory for IRS compliance
- Specified Service Trade or Business (SSTB) limitations create additional complexity requiring specialized planning
What Is the QBI W-2 Wage Limitation?
Quick Answer: The W-2 wage limitation under Section 199A caps the QBI deduction for high-income taxpayers. It limits the deduction to the greater of 50% of W-2 wages or 25% of W-2 wages plus 2.5% of qualified property basis.
The qualified business income deduction, established under Section 199A of the Internal Revenue Code, allows eligible business owners to deduct up to 20% of their qualified business income. However, for taxpayers whose income exceeds certain thresholds, the QBI deduction W-2 wage limitation planning becomes essential.
Congress designed this limitation to ensure the deduction benefits businesses that generate employment and make capital investments. Therefore, businesses with higher W-2 wage payments or substantial qualified property basis receive more favorable treatment than those operating with minimal payroll or assets.
The Mechanics of Section 199A
For 2026, the baseline QBI deduction equals 20% of qualified business income from a domestic trade or business. This includes income from sole proprietorships, partnerships, S corporations, and certain trusts. The deduction reduces taxable income but not self-employment tax or adjusted gross income.
When taxpayers exceed income thresholds, two limitations apply simultaneously. First, the W-2 wage limitation restricts the deduction based on employee compensation paid. Second, for specified service trades or businesses, the deduction phases out entirely above threshold amounts.
Why W-2 Wages Matter
W-2 wages represent the total compensation paid to employees reported on Form W-2. For QBI deduction purposes, this includes salaries, bonuses, commissions, and taxable fringe benefits. Importantly, guaranteed payments to partners and reasonable compensation to S corporation shareholders both count as W-2 wages for limitation calculations.
Pro Tip: Many business owners overlook that only wages properly reported on Form W-2 qualify. Independent contractor payments reported on Form 1099-NEC do not count toward the wage limitation calculation.
When Does the W-2 Wage Limitation Apply to Your Clients?
Quick Answer: The wage limitation applies when taxable income exceeds threshold amounts. For 2026, verify current thresholds at IRS.gov as these amounts adjust annually for inflation.
Understanding when QBI deduction W-2 wage limitation planning becomes necessary requires analyzing three distinct income ranges. Tax professionals must determine where their clients fall within the phase-in structure to calculate the appropriate limitation.
Below Threshold: Full Deduction Available
Taxpayers with taxable income below the threshold amount receive the full 20% QBI deduction without any wage limitation. At this income level, the deduction equals the lesser of 20% of QBI or 20% of taxable income minus net capital gains. No W-2 wage analysis is required.
This creates planning opportunities for taxpayers near the threshold. Strategic income deferrals or accelerated deductions can keep taxable income below the limitation threshold, preserving the full deduction benefit.
Phase-In Range: Partial Limitation
When taxable income falls within the phase-in range, the wage limitation applies gradually. The IRS uses a complex fraction to determine what percentage of the limitation applies. This creates significant planning complexity because small changes in taxable income can produce meaningful shifts in deduction value.
For tax professionals serving business owners, this phase-in range represents the highest-value planning opportunity. Careful year-end projections and strategic adjustments can maximize deduction benefits by managing where clients land within this range.
Above Phase-In: Full Limitation Applies
Once taxable income exceeds the top of the phase-in range, the W-2 wage limitation applies in full. At this income level, sophisticated QBI deduction W-2 wage limitation planning becomes mandatory. Businesses must either increase W-2 wages or acquire qualified property to maximize their deduction.
| Income Level | Wage Limitation Status | Planning Focus |
|---|---|---|
| Below Threshold | No limitation applies | Income management to stay below threshold |
| Phase-In Range | Partial limitation | Strategic positioning within range |
| Above Phase-In | Full limitation | Wage and property basis optimization |
How Do Tax Professionals Calculate the W-2 Wage Limitation?
Quick Answer: Tax professionals calculate two amounts and use the greater: 50% of W-2 wages, or 25% of W-2 wages plus 2.5% of the unadjusted basis of qualified property. The QBI deduction cannot exceed this limitation.
Mastering QBI deduction W-2 wage limitation planning requires understanding both calculation methods. Tax professionals must run both formulas and select the method that produces the higher deduction for their clients. Use our QBI Deduction Calculator to model different scenarios for 2026.
Method 1: The 50% Wage Test
The simpler calculation limits the QBI deduction to 50% of W-2 wages paid by the business. This method favors businesses with high payroll relative to income. Service businesses with significant employee costs often benefit most from this approach.
For example, consider a consulting firm that pays $400,000 in W-2 wages and generates $600,000 in QBI. Under the 50% wage test, the maximum deduction equals $200,000 (50% of $400,000). This exceeds the baseline 20% QBI deduction of $120,000, so the wage limitation does not reduce the deduction.
Method 2: The Combined Wage and Property Test
The alternative calculation combines 25% of W-2 wages with 2.5% of the unadjusted basis of qualified property. This method benefits capital-intensive businesses with substantial property holdings. Manufacturing, real estate, and equipment-heavy operations typically fare better under this approach.
Qualified property includes tangible depreciable property owned by the business and used to produce qualified business income. The unadjusted basis means the original cost without reduction for depreciation. Property must still be within its depreciable period to qualify.
Real-World Calculation Example
ABC Manufacturing generates $800,000 in qualified business income. The company pays $300,000 in W-2 wages and owns $2,000,000 in qualified property (unadjusted basis). Taxable income exceeds the phase-in range, so the full wage limitation applies.
Method 1 (50% wages): $300,000 × 50% = $150,000
Method 2 (25% wages + 2.5% property): ($300,000 × 25%) + ($2,000,000 × 2.5%) = $75,000 + $50,000 = $125,000
The baseline deduction would be $160,000 (20% of $800,000 QBI). However, the wage limitation restricts this to $150,000 using Method 1. The company loses $10,000 in deduction value due to the limitation.
Pro Tip: Always calculate both methods. Software often defaults to one approach, but manual verification ensures clients receive the maximum allowable deduction.
What Qualifies as W-2 Wages?
For QBI deduction W-2 wage limitation planning purposes, W-2 wages include the total shown in Box 1 of Form W-2. This encompasses salaries, bonuses, tips, commissions, and other compensation. Additionally, tax professionals must include elective deferrals to retirement plans and amounts deferred under Section 125 cafeteria plans.
Wages must meet three requirements. First, the business must report them on Form W-2. Second, the business must pay them to employees or officers performing services. Third, the wages must be paid during the calendar year, not the business’s fiscal year if different.
What Planning Strategies Maximize the QBI Deduction Despite Wage Limits?
Quick Answer: Tax professionals use year-end bonus payments, accelerated equipment purchases, and entity restructuring to increase W-2 wages or qualified property basis. These strategies preserve more deduction value for high-income clients.
Successful QBI deduction W-2 wage limitation planning requires proactive strategies implemented throughout the year. Waiting until December limits your options and reduces effectiveness. The most sophisticated tax advisory practices integrate these strategies into quarterly planning sessions.
Strategy 1: Year-End Wage Acceleration
Paying year-end bonuses in December instead of January increases current-year W-2 wages. This simple timing adjustment can preserve thousands of dollars in QBI deduction value. However, businesses must actually pay the wages by December 31, not merely accrue them.
Consider accelerating January payroll into late December. While this increases current-year payroll tax deposits, the QBI deduction savings often exceeds the cash flow cost. Run projections to determine the optimal amount.
Strategy 2: Equipment Purchase Timing
Acquiring qualified property before year-end increases the unadjusted basis component of the wage limitation calculation. This particularly benefits businesses using Method 2 (25% wages plus 2.5% property). Equipment purchases planned for early next year should be evaluated for acceleration.
The property must be placed in service during the tax year to count. Merely ordering equipment does not suffice. Additionally, the unadjusted basis includes the full purchase price, regardless of whether Section 179 expensing or bonus depreciation is claimed.
Strategy 3: Reasonable Compensation Adjustments
S corporation shareholders can adjust their reasonable compensation to optimize the wage limitation. Increasing shareholder W-2 wages reduces QBI but increases the wage limitation threshold. This creates a mathematical optimization problem that requires careful modeling.
Tax professionals must balance three competing factors. Higher wages increase payroll taxes but reduce self-employment tax exposure. Simultaneously, increased wages raise the wage limitation but reduce qualified business income. The optimal wage level depends on the client’s specific tax situation.
Pro Tip: Document reasonable compensation decisions thoroughly. The IRS scrutinizes S corporation wages, and inadequate documentation can trigger audits that cost far more than any tax savings.
Strategy 4: Multi-Entity Structuring
Sophisticated clients benefit from entity structuring that separates high-wage and low-wage activities. This allows each business to optimize its own wage limitation calculation. However, aggregation rules may require combining related businesses, limiting this strategy’s effectiveness.
Operating businesses can lease equipment from related entities. The operating entity pays rent, creating a deduction, while the equipment-owning entity generates qualified business income with substantial property basis. This shifts income to an entity better positioned for QBI deduction W-2 wage limitation planning.
| Strategy | Best For | Timing | Complexity |
|---|---|---|---|
| Year-end wage acceleration | Service businesses | Q4 implementation | Low |
| Equipment purchases | Capital-intensive businesses | By December 31 | Low |
| Compensation adjustments | S corporations | Year-round | Medium |
| Multi-entity structuring | High-income businesses | Annual planning | High |
How Does Entity Structure Affect W-2 Wage Limitations?

Quick Answer: S corporations and partnerships calculate W-2 wages differently. S corporation shareholder wages count, while partnership guaranteed payments do not. Entity choice significantly impacts QBI deduction availability.
Entity selection represents one of the most impactful decisions in QBI deduction W-2 wage limitation planning. The choice between sole proprietorship, partnership, S corporation, or C corporation fundamentally alters how the wage limitation operates.
Sole Proprietorships: Zero W-2 Wages
Sole proprietors operating as Schedule C businesses pay themselves through draws, not wages. Therefore, they report zero W-2 wages for QBI limitation purposes. Once taxable income exceeds the threshold, sole proprietors face severe deduction limitations unless they own substantial qualified property.
This creates a powerful incentive for high-income sole proprietors to hire employees or elect S corporation status. Converting to an S corporation allows the owner to pay themselves reasonable compensation reported on Form W-2, creating wage limitation relief.
S Corporations: Shareholder Wages Count
S corporations must pay shareholder-employees reasonable compensation for services performed. This requirement creates W-2 wages that count toward the limitation calculation. For QBI purposes, this provides significant flexibility because shareholders can adjust their wages to optimize the deduction.
However, the IRS requires compensation to be reasonable based on industry standards and services provided. Tax professionals cannot simply set wages at levels that maximize the QBI deduction without economic justification. Documentation supporting reasonableness is essential.
Partnerships: Guaranteed Payments Excluded
Partnerships present unique challenges for QBI deduction W-2 wage limitation planning. Guaranteed payments to partners do not count as W-2 wages. Only amounts paid to actual employees appear on Form W-2 and qualify for the limitation calculation.
This disadvantages partnerships compared to S corporations. Two partners operating identical businesses face different QBI limitations solely due to entity choice. For this reason, many professional service partnerships convert to S corporations when income exceeds the threshold amounts.
C Corporations: No QBI Deduction
C corporations do not qualify for the QBI deduction because the deduction applies only to qualified business income passed through to individual taxpayers. C corporation income is taxed at the entity level at a flat 21% rate, making wage limitation planning irrelevant.
However, some high-income businesses benefit from C corporation status despite losing the QBI deduction. The 21% corporate rate may produce lower overall taxes than the highest individual rates, even without a deduction. This requires comprehensive modeling of both scenarios.
What Are Common Mistakes Tax Professionals Must Avoid?
Quick Answer: Common errors include miscalculating qualified property basis, missing aggregation opportunities, and failing to document reasonable compensation decisions. These mistakes cost clients thousands in lost deductions.
Even experienced practitioners make errors in QBI deduction W-2 wage limitation planning. The complexity of Section 199A creates numerous compliance traps. Understanding these pitfalls helps tax professionals deliver error-free returns and maximize client benefits.
Mistake 1: Using Adjusted Basis Instead of Unadjusted Basis
The most frequent calculation error involves using adjusted basis (cost minus accumulated depreciation) rather than unadjusted basis (original cost) for qualified property. This significantly understates the limitation and costs clients substantial deduction value.
Tax software sometimes defaults to adjusted basis for other calculations. Tax professionals must verify that QBI worksheets use the correct unadjusted basis figure. This requires reviewing fixed asset schedules and ensuring proper data entry.
Mistake 2: Missing the Aggregation Election
Taxpayers can elect to aggregate multiple qualified trades or businesses for QBI purposes. This allows combining W-2 wages and property basis across all aggregated businesses. Failing to consider aggregation leaves money on the table.
According to IRS Notice 2018-64, businesses must meet specific requirements to aggregate. They must have common ownership and satisfy at least two of five factors: same products or services, shared facilities, shared support services, or interdependent operations. Documentation is crucial.
Mistake 3: Ignoring SSTB Phase-Out Rules
Specified service trades or businesses face complete phase-out of the QBI deduction above threshold amounts. Tax professionals sometimes focus solely on wage limitations while overlooking that their client’s business may not qualify at all.
SSTBs include health, law, accounting, consulting, financial services, and businesses where the principal asset is the reputation or skill of employees. For 2026, determining SSTB status requires careful analysis of business activities and revenue sources.
Mistake 4: Insufficient Documentation
QBI deduction W-2 wage limitation planning requires extensive documentation. Tax professionals must maintain records supporting W-2 wage calculations, qualified property basis determinations, and reasonable compensation decisions. The IRS is actively auditing QBI deductions.
Create a permanent file for each client containing Forms W-2, W-3, fixed asset schedules, aggregation election statements, and reasonable compensation analyses. This documentation protects both the client and the practitioner in the event of an examination.
Pro Tip: Use engagement letters specifically addressing QBI deduction planning. Clearly outline what analysis you will perform and what documentation clients must provide. This manages expectations and reduces liability exposure.
Uncle Kam in Action: Manufacturing Client Saves $47,000 Through Strategic Wage Planning
A regional manufacturing company operating as an S corporation approached Uncle Kam in October 2025 facing significant QBI deduction limitations. The business generated $1.2 million in qualified business income but paid only $180,000 in W-2 wages to its three shareholder-employees. The company owned $2.8 million in manufacturing equipment (unadjusted basis).
With taxable income well above the phase-in range, the wage limitation applied in full. Under Method 1 (50% of wages), the limitation was $90,000. Under Method 2 (25% wages plus 2.5% property), the limitation was $115,000. Both fell significantly short of the baseline 20% deduction of $240,000, creating a potential deduction loss of $125,000.
Uncle Kam’s tax advisory team implemented a three-part QBI deduction W-2 wage limitation planning strategy. First, we increased shareholder reasonable compensation by $100,000 total, bringing W-2 wages to $280,000. This was supported by industry compensation surveys and properly documented. Second, we accelerated a planned equipment purchase of $500,000 from January into December, increasing qualified property basis to $3.3 million. Third, we restructured the company’s bonus program to pay year-end bonuses in December rather than March.
The revised calculations showed dramatic improvement. Method 1 now produced $140,000 (50% of $280,000 wages). Method 2 generated $152,500 (25% of $280,000 plus 2.5% of $3.3 million). The company’s QBI deduction increased from $90,000 to $152,500—an improvement of $62,500.
At the client’s 37% marginal federal rate plus 5% state rate, this deduction increase saved $26,250 in federal taxes and $3,125 in state taxes. The total first-year tax savings of $29,375, combined with depreciation benefits from the accelerated equipment purchase, produced total benefits exceeding $47,000. The client’s investment in Uncle Kam’s tax advisory services was $4,500, delivering a 10.4x first-year return on investment.
This case demonstrates how sophisticated QBI deduction W-2 wage limitation planning delivers measurable value. By combining wage adjustments, equipment timing, and compensation restructuring, tax professionals can preserve substantial deduction benefits for high-income business clients.
Next Steps
Effective QBI deduction W-2 wage limitation planning requires year-round attention and proactive implementation. Take these steps to maximize deduction benefits for your clients in 2026:
- Review all business client returns to identify those whose taxable income exceeds QBI threshold amounts
- Calculate both wage limitation methods quarterly to track deduction exposure throughout the year
- Model reasonable compensation adjustments for S corporation shareholders before year-end
- Document all equipment purchases with qualified property basis schedules for limitation calculations
- Book a strategy session at unclekam.com/book-strategy-session to implement advanced planning techniques
Tax professionals who master these strategies differentiate themselves from competitors and deliver measurable ROI. Your clients depend on your expertise to navigate Section 199A’s complexity and preserve valuable deduction benefits.
Frequently Asked Questions
Can I increase W-2 wages by hiring family members to improve the wage limitation?
Yes, hiring family members creates legitimate W-2 wages that count toward the limitation calculation. However, compensation must be reasonable for services actually performed. The IRS scrutinizes family employment arrangements, requiring documentation of duties, hours worked, and market-rate compensation. Children under 18 working for parents’ sole proprietorships or partnerships do not qualify because their wages are exempt from FICA taxes.
What happens if I pay December wages in early January instead?
Wages count toward the QBI limitation based on when they are actually paid, not when they are earned or accrued. December wages paid in January count toward the following year’s limitation calculation. This timing rule creates planning opportunities for accelerating year-end bonuses. The opposite strategy—deferring wages to the following year—reduces current-year W-2 wages and may decrease the deduction.
Do retirement plan contributions count as W-2 wages for QBI purposes?
Yes, elective deferrals to retirement plans appear in Box 12 of Form W-2 and count as W-2 wages for the limitation calculation. This includes 401(k) deferrals, 403(b) contributions, and SIMPLE IRA deferrals. Employer matching contributions also count because they represent compensation to employees. This makes retirement plan contributions particularly valuable for QBI deduction W-2 wage limitation planning.
How does the wage limitation work for businesses with multiple owners?
Each owner calculates their own QBI deduction based on their share of business income, W-2 wages, and qualified property. Partnerships and S corporations report these amounts to owners on Schedule K-1. The entity-level W-2 wages and property basis flow through proportionally to each owner. Therefore, all owners benefit when the business increases wages or acquires property.
What qualifies as “unadjusted basis” for the property calculation?
Unadjusted basis means the original cost of property without reduction for depreciation. For purchased property, this equals the purchase price plus improvements. For property acquired through exchange, it equals the carryover basis. Property must be tangible, depreciable, and used in producing qualified business income. Land does not qualify because it is not depreciable. The property must still be within its depreciable period—fully depreciated property no longer counts.
Can I claim the QBI deduction if my business shows a loss?
Businesses with qualified business losses cannot claim the QBI deduction for that year. The loss carries forward to reduce qualified business income in future years. This loss carryforward reduces future QBI deductions dollar-for-dollar. Proper planning may involve deferring losses to years with lower income or accelerating income into loss years to offset the losses.
How do I verify 2026 income thresholds for the wage limitation?
The IRS publishes annual inflation adjustments for QBI thresholds in Revenue Procedures released each fall for the following tax year. For 2026, consult the most recent IRS Revenue Procedure or inflation adjustment announcement. These thresholds typically increase annually based on inflation indices. Tax software providers also update threshold amounts when the IRS publishes official figures.
| Planning Element | Deadline | Key Action |
|---|---|---|
| Income threshold analysis | January 2026 | Identify clients affected by limitations |
| Quarterly wage projections | March, June, September | Calculate estimated limitation exposure |
| Equipment purchase timing | November 2026 | Evaluate acceleration opportunities |
| Year-end wage adjustments | December 15, 2026 | Implement bonus payments and payroll timing |
| Final limitation calculations | December 31, 2026 | Lock in wages and property basis for year |
Related Resources
- Tax Strategy Services for Business Owners
- Entity Structuring for QBI Optimization
- The MERNA™ Method for Comprehensive Tax Planning
- Complete Tax Planning Guides
- Tax Planning Software with Unlimited Assessments
This information is current as of 6/11/2026. Tax laws change frequently. Verify updates with the IRS or a qualified tax professional if reading this later.
Last updated: June, 2026

