Moving from Indiana to Texas Taxes: Complete 2026 Tax Savings Guide
Moving from Indiana to Texas Taxes: Complete 2026 Tax Savings Guide
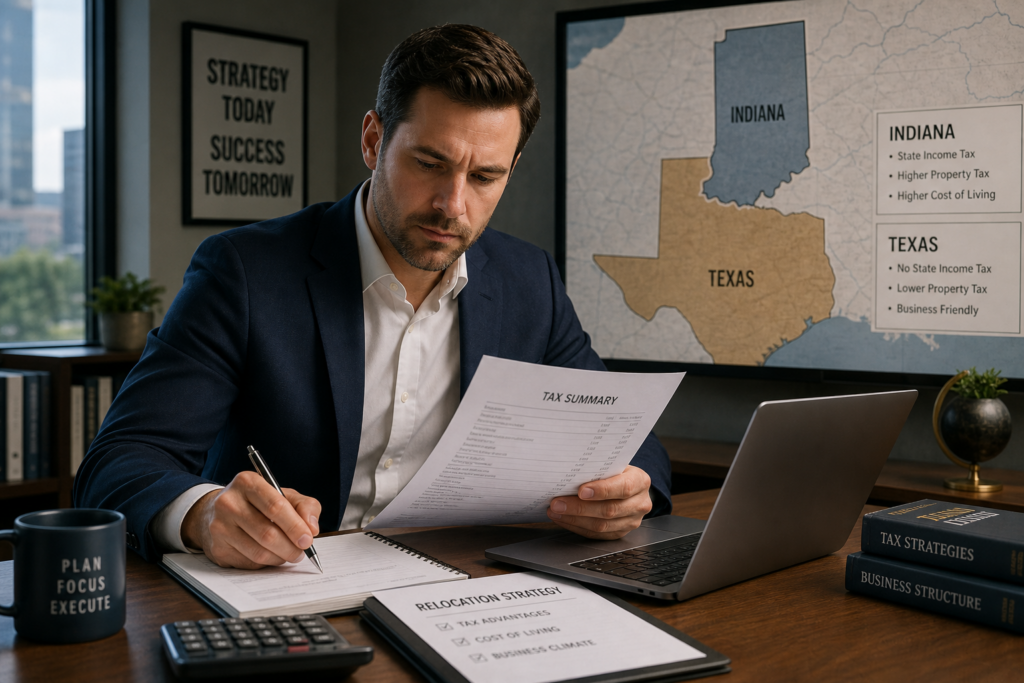
For 2026, moving from Indiana to Texas offers substantial tax advantages that can transform your financial situation. With Indiana’s 3.23% state income tax and Texas’s zero state income tax, relocating professionals, business owners, and self-employed workers can capture immediate savings. This comprehensive guide to moving from Indiana to Texas taxes explores actual 2026 tax figures, filing requirements, and strategic considerations for making your relocation decision with confidence.
Table of Contents
- Key Takeaways
- Quick Snapshot: How Your Taxes Change
- Indiana vs. Texas Tax Breakdown
- Real-World Examples: How Much You Could Save
- Special Cases: Who Benefits Most
- Legal and Filing Considerations
- Step-by-Step: Tax Checklist Before You Move
- Frequently Asked Questions
- Related Resources
Key Takeaways
- Texas has zero state income tax, eliminating Indiana’s 3.23% flat tax burden for 2026.
- A self-employed individual earning $100,000 saves $3,230 annually in state income tax.
- Establishing proper residency requires documentation and intent to make Texas your primary home.
- Property taxes vary by Texas location but often remain competitive compared to Indiana.
- Part-year residents must file returns in both states and claim proper tax credits.
Quick Snapshot: How Your Taxes Change When You Move from Indiana to Texas
Quick Answer: For the 2026 tax year, moving to Texas eliminates your Indiana state income tax of 3.23%. This is the single biggest tax advantage. Federal taxes remain identical. Property tax savings vary by specific location.
The fundamental difference between Indiana and Texas for 2026 is straightforward: Indiana charges a 3.23% flat state income tax on all residents, while Texas charges zero. This alone creates immediate, substantial savings. However, the complete financial picture requires examining property taxes, sales taxes, and your specific income level to understand total tax burden changes.
Consider this baseline: Indiana residents pay 3.23% of income to the state. A person earning $75,000 pays $2,423 annually. That same income in Texas results in zero state income tax. This creates the foundation for all other tax planning considerations.
2026 Tax Comparison Table: Indiana vs. Texas
| Tax Type | Indiana | Texas |
|---|---|---|
| State Income Tax | 3.23% flat rate | 0% (No tax) |
| Sales Tax (State) | 7% base rate | 6.25% base rate |
| Property Tax (varies) | 0.50-0.85% of value | 0.60-1.80% of value |
| Federal Income Tax | Same brackets for 2026 | Same brackets for 2026 |
Indiana and Texas differ significantly on income tax but offer competing advantages in other areas. Indiana’s base sales tax of 7% exceeds Texas’s 6.25%, creating additional savings for Texas residents. Property taxes require careful analysis by location, as they vary substantially within each state.
Indiana vs. Texas Tax Breakdown: Where You Actually Save Money
Quick Answer: State income tax savings of 3.23% on all earnings is the primary advantage. Secondary savings come from lower sales taxes. Property tax differences vary by specific location and home value.
State Income Tax: How Much You Actually Save
For 2026, Indiana’s income tax rate of 3.23% applies to all residents regardless of income level. This flat structure means higher earners pay the same percentage as lower-income residents. Texas eliminates this entirely. The savings scale directly with income: someone earning $150,000 saves $4,845 annually in state income tax alone.
This is the cornerstone of the financial advantage. Unlike graduated tax systems, Indiana’s flat rate eliminates complexity but also eliminates opportunity for tax-bracket planning. For business owners, self-employed professionals, and executives earning above $100,000, state income tax elimination becomes a primary relocation motivation.
Pro Tip: Tax savings from relocation compound over time. A $4,000 annual state income tax savings over 10 years represents $40,000 available for investment or business growth.
Sales Taxes: The Secondary Advantage
Texas charges 6.25% state sales tax compared to Indiana’s 7% base rate. This 0.75% difference adds up across all taxable purchases. While not as impactful as income tax elimination, sales tax savings benefit everyone—employees, business owners, and retirees alike.
For someone spending $60,000 annually on taxable goods, this translates to approximately $450 in annual savings. When combined with income tax savings, the cumulative effect becomes significant for household budgeting and long-term financial planning.
Property Taxes: Location Matters
Property tax rates vary substantially within each state. Indiana typically ranges from 0.50% to 0.85% of home value annually. Texas varies more widely, from 0.60% to 1.80% depending on location, school district, and local government services.
The absence of state income tax in Texas often compensates for higher property tax rates in desirable areas. A homeowner purchasing a $300,000 property in Austin might pay higher property taxes than in Indianapolis, but state income tax elimination typically creates net savings for working professionals and business owners.
Real-World Examples: How Much Could You Save in 2026?
Quick Answer: State income tax savings range from $1,615 for a $50,000 earner to $8,075 for a $250,000 earner, making relocation financially compelling for higher-income professionals.
Example Scenario 1: W-2 Employee Earning $75,000
Jennifer earns $75,000 annually as a healthcare administrator in Indianapolis. For 2026, her Indiana state income tax is $2,423. Moving to Dallas, Texas, she eliminates this payment entirely while maintaining her salary. She also benefits from 0.75% lower sales tax on household purchases.
Federal income tax remains identical at both locations. Her 2026 tax savings equal approximately $2,423 in state income tax plus an estimated $450 in sales tax savings, totaling $2,873 annually. Over her 15-year career in Texas, this creates $43,095 in additional after-tax income.
Example Scenario 2: Self-Employed Professional Earning $150,000
Marcus runs a consulting business from Fort Wayne, Indiana, with annual gross revenue of $150,000. His Indiana state income tax for 2026 totals $4,845. He also pays self-employment tax (not affected by state location). Relocating to Houston, he eliminates state income tax entirely.
Marcus’s annual state income tax savings equal $4,845. For tax planning purposes, he uses our Self-Employment Tax Calculator for Fort Wayne to estimate his complete tax position and plan for quarterly estimated payments in Texas for 2026.
Example Scenario 3: Small Business Owner Earning $300,000
David owns an LLC generating $300,000 in annual net business income in Indianapolis. His Indiana state income tax equals $9,690 for 2026. Moving to San Antonio, Texas, he eliminates this entirely while maintaining business operations. Combined with sales tax savings and business-friendly Texas policies, his annual state tax savings exceed $10,000.
| Annual Income | Indiana Tax (2026) | Texas Tax (2026) | Annual Savings |
|---|---|---|---|
| $50,000 | $1,615 | $0 | $1,615 |
| $100,000 | $3,230 | $0 | $3,230 |
| $150,000 | $4,845 | $0 | $4,845 |
| $200,000 | $6,460 | $0 | $6,460 |
| $250,000 | $8,075 | $0 | $8,075 |
These examples demonstrate that higher earners benefit proportionally more from relocation. Business owners and self-employed professionals experience the largest absolute savings, making Texas particularly attractive for entrepreneurs.
Special Cases: Who Benefits Most from Moving to Texas?
 Free Tax Write-Off Finder
Quick Answer: Self-employed professionals, business owners, and remote workers realize maximum benefits. W-2 employees gain meaningful savings. Retirees benefit if moving before claiming significant income.
Self-Employed and Freelancers: Maximum Tax Benefits
Self-employed professionals experience the most substantial savings. Unlike W-2 employees whose withholding adjusts automatically, self-employed workers control their income and tax planning. Eliminating 3.23% of business income on top of self-employment tax savings creates compelling financial incentives.
A freelance consultant earning $200,000 saves $6,460 in Indiana state income tax plus potential business-friendly Texas policies. This creates flexibility for business investment, equipment purchases, and growth capital.
Remote Workers Employed Out-of-State
Remote workers present a special case. If you work for an Indiana employer while living in Texas, Indiana may still claim income tax authority over wages earned while an Indiana resident. Tax residency matters. Your location on the date you earn income determines which state can tax that income.
Establishing clear Texas residency before earning income ensures you avoid double taxation. Documentation of intent matters: driver’s license, voter registration, and housing lease all support your residency claim.
Retirees and Fixed-Income Households
Retirees benefit from Texas’s income tax structure, particularly those drawing pensions or investment income. However, timing matters. Social Security income and qualified retirement distributions have different tax treatment. Moving after claiming Social Security requires careful planning to avoid unintended double taxation during transition years.
Retirees drawing $75,000 in pension income save $2,423 in state income tax annually. Over a 20-year retirement, this totals $48,460 in tax savings available for healthcare, travel, or legacy planning.
Legal and Filing Considerations for Your Move
Quick Answer: Residency requires establishing intent, changing documentation, and filing part-year returns. Indiana may claim continuing tax authority during your transition year.
Establishing Tax Residency in Texas
Tax residency requires more than physical presence. States look for intent to establish permanent residence. Documentation includes obtaining a Texas driver’s license, registering to vote, leasing or purchasing property, and opening bank accounts in your new state. These establish the “badges of residency” that determine tax filing status.
The IRS and state tax authorities examine where you spend most of your time, where your family resides, where you maintain a home, and where your economic interests center. Establishing Texas residency before earning significant income in 2026 ensures clean tax treatment.
Part-Year Return Requirements
If you move mid-year, you typically file a part-year resident return with Indiana and a part-year resident return with Texas. Each state taxes only income earned while you were a resident. This prevents double taxation but requires detailed income allocation by date of residency change.
Moving June 15, 2026, means allocating half-year income to Indiana (subject to 3.23% tax) and half-year income to Texas (no state tax). You’ll file both returns and claim the Indiana tax credit on your Texas return to avoid double taxation.
Pro Tip: Time your move strategically. Moving January 1 maximizes 2026 Texas tax benefits. Moving December 31 captures the full Indiana tax year. Consult a tax professional about optimal timing for your situation.
Indiana’s Continuing Tax Authority
Indiana may assert tax authority over your 2026 income if you worked there while a resident, even after relocating. Indiana law taxes income earned by Indiana residents regardless of where the work occurred. This creates potential for double taxation during your move year if not handled properly.
The solution: file part-year resident returns, allocate income by residence dates, and claim the Indiana tax credit on your Texas return. Professional tax preparation ensures compliance with both states’ requirements.
Step-by-Step: Tax Checklist Before You Move
Quick Answer: Complete residency documentation, estimate income allocation, gather prior tax returns, and coordinate move timing with your tax calendar.
Your Moving Checklist: Before You Relocate
- Consult a tax professional to analyze your specific 2026 tax situation and estimate savings.
- Document your current Indiana residence with utility bills, property records, and insurance policies.
- Obtain a Texas driver’s license and register to vote in your new state.
- Estimate your 2026 income to calculate potential state tax savings.
- Plan your move date strategically (ideally January 1 or after major income events).
- Gather prior-year Indiana tax returns for your tax professional’s records.
- Set up estimated tax payment schedule for 2026 based on your Texas income.
- Notify employers and businesses of address change and tax residency status change.
Uncle Kam in Action: Sarah’s $16,000 Tax Savings
Sarah is a 42-year-old marketing director living in Indianapolis earning $120,000 annually. She manages a small team and generates side consulting income totaling $80,000, making her combined 2026 income $200,000. Her Indiana state income tax burden is $6,460 annually.
Moving to Austin, Texas, Sarah establishes residency January 1, 2026. Consulting her tax preparation services in Indiana, she structures her consulting business as an LLC, takes advantage of Texas’s zero state income tax, and maintains her employer W-2 income. Her 2026 tax situation transforms dramatically.
First-year savings: $6,460 in state income tax elimination. Secondary savings: $1,500 in sales tax reductions across the year (0.75% on $200,000 in personal spending). Total 2026 savings: $7,960. Over 5 years of Texas residence, this totals approximately $40,000 in tax savings—funds that Sarah reinvests in her consulting business and retirement accounts.
Beyond the financial impact, Sarah gains strategic advantages. Texas’s business-friendly environment enables her to scale her consulting operation. No state income tax means higher after-tax income for reinvestment. After five years, her compounded savings and business growth position her to hire full-time employees and expand into new markets.
Next Steps: Take Action on Your 2026 Relocation
Moving from Indiana to Texas offers quantifiable financial benefits for 2026. The next step is determining whether relocation aligns with your personal and professional goals. These action items move you forward:
- Schedule a consultation with a tax professional to model your specific 2026 situation.
- Identify your target Texas city and research property taxes, cost of living, and business environment.
- Visit potential relocation cities and establish whether Texas truly aligns with your lifestyle.
- Calculate your multi-year savings projection beyond 2026 to justify relocation costs.
- Explore our tax preparation services for Indiana residents planning relocation to ensure proper 2026 filing.
Frequently Asked Questions
Does Texas really have zero state income tax in 2026?
Yes. Texas has maintained zero state income tax for decades. For the 2026 tax year, there is no state income tax on wages, self-employment income, investment income, or any other income source. This fundamental difference makes Texas uniquely attractive compared to Indiana and other high-tax states.
What’s Indiana’s state income tax rate for 2026?
Indiana charges a flat 3.23% state income tax on all residents for the 2026 tax year. This applies equally to all income levels, making Indiana’s tax burden straightforward but also unchanging regardless of how much you earn. Moving to Texas eliminates this 3.23% entirely.
Will I pay more in Texas property taxes than I did in Indiana?
Property tax rates vary significantly within both states. Indiana typically ranges from 0.50% to 0.85% of home value. Texas typically ranges from 0.60% to 1.80% depending on location. In many cases, Texas property taxes are higher per dollar of home value, but state income tax elimination often more than compensates. Calculate your specific property’s impact before deciding.
Can Indiana still tax me after I move to Texas?
Indiana can tax income earned while you were an Indiana resident. If you move mid-year, Indiana taxes income earned before your move date. You file a part-year resident return in Indiana and a part-year resident return in Texas, with each state taxing only income earned during your residence period. This prevents double taxation when properly reported.
What documentation proves I’m a Texas resident for tax purposes?
Primary documentation includes Texas driver’s license, voter registration, home lease or property deed, and bank accounts. Secondary documentation includes utility bills, insurance policies, and employment location. States examine the totality of circumstances to determine residency. Establishing clear badges of residency before earning significant 2026 income prevents audit risk.
How much will I save by moving to Texas in 2026?
Annual savings equal 3.23% of your income in state income tax, plus approximately $450 to $1,000 in sales tax savings depending on spending habits. Someone earning $150,000 saves approximately $5,300 annually. Someone earning $250,000 saves approximately $8,100 annually. Calculate your specific income to determine your personal savings.
Should I move January 1, 2026, or mid-year?
January 1 moves maximize 2026 tax benefits but may not align with your career or personal timeline. Mid-year moves create part-year return complexity but may be necessary for employment or family reasons. Consult your tax professional about optimal timing based on your income schedule and move timeline.
What if I work remotely for an Indiana employer while living in Texas?
If you establish clear Texas residency before earning income remotely, Texas has exclusive tax authority. Your employer may continue withholding Indiana taxes initially—request an updated W-4 to stop Indiana withholding once you establish Texas residency. File part-year returns for your move year and claim any excess Indiana withholding as a credit on your Texas return.
Related Resources
- Tax Preparation Near Me in Indiana
- Tax Strategies for Business Owners
- Self-Employment Tax Planning Guide
- Comprehensive Tax Strategy Solutions
- Real Estate Investor Tax Guide
Last updated: June, 2026
This information is current as of 6/8/2026. Tax laws change frequently. Verify updates with the IRS or relevant state tax authorities if reading this later in 2026 or beyond.