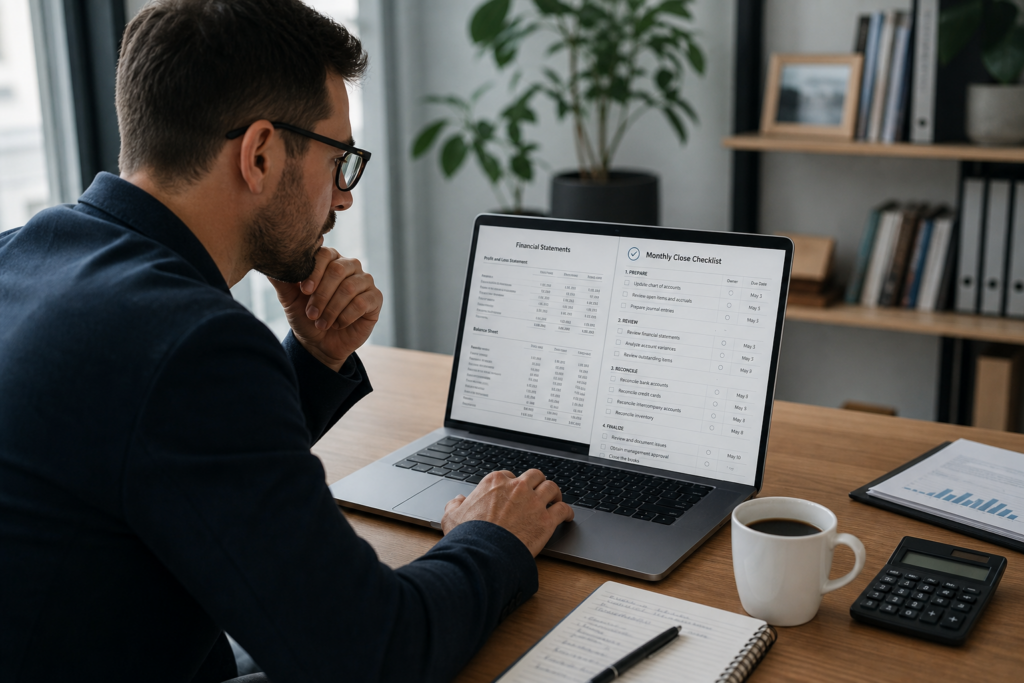
Monthly Close Checklist: 2026 Guide for Business Owners
Monthly Close Checklist: 2026 Guide for Business Owners
A solid monthly close checklist is the backbone of smart business finances. For the 2026 tax year, new legislation — including the One Big Beautiful Bill Act (OBBBA) — has added fresh compliance steps that every business owner needs to track. Use this step-by-step guide to close your books with confidence each month and catch tax opportunities before year-end.
Table of Contents
- Key Takeaways
- What Is a Monthly Close Checklist and Why Does It Matter?
- What Should Your Monthly Bookkeeping Steps Include?
- How Does 2026 Tax Law Change Your Monthly Close?
- When Are Estimated Tax Payments Due in 2026?
- What Payroll Items Must You Review Each Month?
- How Do You Track Digital Assets in Monthly Close for 2026?
- What Tax Strategy Steps Belong in Your Monthly Close?
- Uncle Kam in Action: Restaurant Owner Saves $31,200
- Next Steps
- Related Resources
- Frequently Asked Questions
Key Takeaways
- A monthly close checklist keeps books current and prevents costly year-end surprises.
- For 2026, the OBBBA introduced new deductions and compliance requirements that affect monthly tracking.
- Your Q2 2026 estimated tax payment is due June 15, 2026 — plan your cash flow now.
- IRS Form 1099-DA now requires monthly tracking of digital asset transactions.
- Business owners in 2026 benefit from enhanced bonus depreciation under the OBBBA.
What Is a Monthly Close Checklist and Why Does It Matter?
Quick Answer: A monthly close checklist is a structured set of accounting and tax steps you complete at the end of each month. It keeps your financial records accurate, your taxes current, and your business audit-ready.
Most business owners treat closing the books as a once-a-year chore. However, that approach creates serious risks. Errors pile up. Tax opportunities disappear. Estimated payments get miscalculated. A monthly close checklist solves all of these problems by breaking the process into manageable, recurring tasks.
The 2026 tax environment makes this discipline even more critical. The One Big Beautiful Bill Act (OBBBA), signed on July 4, 2025, introduced new deductions, updated reporting rules, and created fresh compliance traps. Business owners who fail to track these monthly will face reconciliation nightmares at tax time. Our tax strategy team sees this every year — and it is entirely preventable.
The Cost of Skipping Monthly Close
Skipping monthly close does more than create accounting headaches. It costs real money. When books are not current, you may:
- Miss deductions that expired or have dollar caps
- Underpay estimated taxes and face IRS penalties
- Fail to catch payroll errors before they compound
- Miss Employee Retention Credit refund claim deadlines — some two-year windows expire in 2026
- Trigger penalties for unreported digital asset transactions
According to the IRS Small Business and Self-Employed Tax Center, accurate and timely recordkeeping is the single most effective way to reduce audit risk and maximize deductions. A well-run monthly close checklist puts you on the right side of that equation every single month.
Who Benefits Most from a Monthly Close Process?
Any business benefits from monthly close. However, the process is especially valuable for:
- S Corps and LLCs making quarterly estimated payments
- Businesses with employees or contractors on payroll
- Companies accepting or holding digital assets
- Hospitality and service businesses navigating new 2026 OBBBA tip deduction rules
- Importers and retailers facing the new 1% excise tax on overseas remittances in 2026
Pro Tip: Schedule your monthly close for the 5th business day after month-end. This gives time for bank statements to clear while keeping books fresh.
What Should Your Monthly Bookkeeping Steps Include?
Quick Answer: Your core monthly close checklist should cover bank reconciliation, accounts receivable aging, accounts payable review, expense categorization, and financial statement preparation. Every step must be completed before moving to the next.
Strong bookkeeping is the foundation of every other item on your monthly close checklist. Without clean books, estimated tax calculations are guesswork. Deduction tracking becomes unreliable. Your tax advisor cannot give you accurate guidance. Here is what your monthly bookkeeping steps must include for 2026.
Step 1: Bank and Credit Card Reconciliation
Reconcile every bank account and credit card statement against your accounting software. Look for:
- Duplicate transactions that inflated expenses
- Missing deposits or unrecorded income
- Bank fees that belong in specific expense categories
- Personal charges accidentally run through the business account
Mixing personal and business expenses is one of the most common errors the IRS flags in audits. In 2026, the IRS has proposed increased use of optical character recognition and bar code scanning for returns. This means discrepancies between reported income and bank deposits get flagged faster than ever. Keep all accounts clean at the monthly level.
Step 2: Accounts Receivable and Accounts Payable Review
Review your aging receivables report each month. Identify invoices 30, 60, and 90+ days past due. Follow up promptly. Uncollected revenue that sits too long may require a bad debt adjustment at year-end, which can complicate your tax picture.
On the payables side, confirm all vendor bills are entered and properly categorized. This is especially important in 2026 because the OBBBA created new floors on certain itemized deductions for charitable contributions. If you donate monthly, make sure those amounts are logged in the right category each month — not lumped together at year-end.
Step 3: Expense Categorization and Deduction Readiness
Categorize every expense line correctly. For 2026, pay special attention to:
- Tip income paid to employees — the tip income deduction final regulations took effect June 12, 2026. Log tip amounts monthly to support this deduction.
- Capital expenditures — the OBBBA restored enhanced bonus depreciation. Track all equipment and asset purchases monthly to maximize your 2026 depreciation write-offs.
- Vehicle and transportation costs — new car loan interest deductions apply to 2025–2028 tax years. Keep mileage logs and loan interest records current each month.
- Overseas payments and remittances — if your business makes overseas payments, the new 1% excise tax applies for 2026. Track these transactions monthly.
Per IRS Publication 334, business taxpayers must keep adequate records to support all deductions claimed on their returns. Monthly categorization is the most reliable way to satisfy that standard.
Pro Tip: Use accounting software to set rules for recurring expenses. This speeds up monthly categorization by 70% and reduces manual error.
Step 4: Monthly Financial Statements
Generate three reports at the end of every month:
- Profit and Loss (P&L) Statement — shows revenue, expenses, and net income for the month and year-to-date
- Balance Sheet — confirms assets, liabilities, and equity are balanced
- Cash Flow Statement — tracks where money actually moved, separate from accrual entries
These three reports become your primary tools for estimated tax planning. With the April 2026 inflation rate at 3.8% according to the U.S. Bureau of Labor Statistics, many businesses are seeing cost increases outpace revenue growth. Monthly P&L reviews help you spot margin compression early and adjust pricing or spending before it becomes a crisis.
How Does 2026 Tax Law Change Your Monthly Close Checklist?
Quick Answer: The OBBBA created new deductions and compliance rules effective in 2026. Your monthly close must now include OBBBA-specific tracking for tip income, bonus depreciation, charitable contributions, and digital assets to stay compliant and capture available savings.
The 2026 tax year brought the most significant changes to the federal tax code in years. The One Big Beautiful Bill Act, signed on July 4, 2025, affects how business owners track, categorize, and report multiple expense types. Adding OBBBA compliance tasks to your monthly close checklist is not optional — it is essential for maximizing 2026 tax benefits. Learn how tax prep and filing experts incorporate these new rules into each monthly cycle.
New Deductions Requiring Monthly Tracking in 2026
The table below summarizes the key 2026 OBBBA changes that require monthly recordkeeping:
| 2026 OBBBA Change | Who It Affects | Monthly Close Action |
|---|---|---|
| Tip income deduction (final regs effective June 12, 2026) | Hospitality, food service, service businesses | Log tip amounts paid by category monthly |
| Enhanced bonus depreciation | Any business purchasing equipment or assets | Record all asset purchases with acquisition dates |
| Charitable deduction for non-itemizers | Sole proprietors and pass-through owners | Track charitable contributions with receipts monthly |
| 1% excise tax on overseas remittances | Importers, retailers, global businesses | Flag and record all overseas payments monthly |
| Car loan interest deduction (2025–2028) | Business owners with qualifying vehicle loans | Record interest paid monthly; retain loan documents |
OBBBA Compliance Pitfalls to Avoid
According to a May 2026 post-tax-season review by Accounting Today, the IRS identified problems with tip income, overtime, and car loan interest deductions — largely because businesses could not reconcile amounts claimed on returns with information reported by employers or lenders. This underscores a critical point: monthly documentation is the only reliable way to support these new deductions.
Furthermore, the OBBBA limits the benefit of the 37% tax bracket for itemized deductions for wealthier taxpayers. As a result, high-income business owners should review how deduction strategies interact with their marginal rate each month — not just at year-end. Our high-net-worth tax strategy team works through these calculations as part of every monthly review cycle.
Did You Know? The Tax Foundation estimates the average U.S. taxpayer received a $611 tax cut from the OBBBA in 2026. However, business owners who track OBBBA deductions monthly consistently capture significantly more savings than the average filer.
When Are Estimated Tax Payments Due in 2026?
Quick Answer: For the 2026 tax year, quarterly estimated payments are due April 15, June 15, September 15, and January 15, 2027. Your Q2 2026 payment is due June 15, 2026. Missing these deadlines triggers IRS penalties and interest.
Estimated tax management is one of the most critical items on any monthly close checklist. Business owners — including S Corp shareholders, sole proprietors, and LLC members — must pay taxes quarterly. Failing to estimate correctly creates cash flow surprises and potential underpayment penalties. Every monthly close cycle should include a fresh estimated tax projection based on your current-month P&L.
2026 Estimated Tax Payment Schedule
| Payment Period | Due Date | Months Covered |
|---|---|---|
| Q1 2026 | April 15, 2026 | January – March 2026 |
| Q2 2026 | June 15, 2026 | April – May 2026 |
| Q3 2026 | September 15, 2026 | June – August 2026 |
| Q4 2026 | January 15, 2027 | September – December 2026 |
The IRS requires you to make payments via electronic transfer. Visit the IRS Payments page to schedule estimated payments using EFTPS or IRS Direct Pay. Paper checks are still accepted in 2026 with Form 1040-V and proper identifying information, but direct deposit and electronic payment is strongly preferred by the IRS.
How to Calculate Your Monthly Estimated Tax Projection
Use this simple formula during each monthly close:
- Step 1: Take your year-to-date net income from the P&L
- Step 2: Subtract year-to-date deductions (including OBBBA items)
- Step 3: Apply your effective tax rate (typically 25–37% for business owners)
- Step 4: Subtract estimated payments already made this year
- Step 5: The result is your remaining projected tax liability — plan cash reserves accordingly
For example: A consulting firm earning $180,000 in net income through May 2026, after $35,000 in deductions, faces a projected federal tax liability of approximately $38,500 (assuming a 27% blended effective rate). After one Q1 payment of $9,000, that leaves $29,500 still owed across Q2–Q4. Your monthly close keeps this number current so you never get surprised.
Pro Tip: The safe harbor rule lets you avoid underpayment penalties. Pay either 100% of your prior-year tax liability or 90% of your current-year liability — whichever is less. Build this into your monthly close calculation.
What Payroll Items Must You Review Each Month?
 Free Tax Write-Off Finder
Quick Answer: Your monthly payroll review should confirm payroll taxes are deposited, W-2 and 1099 contractor records are current, retirement plan contributions are processed, and 2026 OBBBA-related deductions (tip income, overtime) are documented.
Payroll is the area where most small businesses run into the most trouble during year-end reviews. Monthly payroll checks prevent these problems. For 2026, the stakes are higher because the OBBBA created new tracking requirements around tip and overtime income. Business solutions like automated payroll platforms can automate much of this process — but a human review is still required each month.
Monthly Payroll Checklist Items
- Confirm federal payroll tax deposits (Form 941) are current — monthly or semi-weekly depending on your deposit schedule
- Reconcile gross wages against your P&L expense entries
- Verify contractor payments — any individual paid $600+ requires a 1099-NEC at year-end, so track monthly
- Record tip income separately — required for 2026 tip income deduction compliance
- Confirm 401(k) contributions are deposited — for 2026, the limit is $24,500 per employee ($8,000 catch-up for age 50+, or $11,250 for ages 60–63 per SECURE 2.0)
- Review any new hires for correct W-4 withholding setup
- Track health insurance premiums paid — S Corp owner premiums have special treatment
S Corp Owner Salary Compliance in 2026
If you operate as an S Corp, your monthly close must verify that your reasonable salary is being paid and reported through payroll. The IRS applies heightened scrutiny to S Corp owner-employee compensation in 2026. Salary must be documented monthly through payroll records — not just at year-end. Underpaid salaries can trigger reclassification of distributions as wages, creating back payroll taxes and penalties.
Augusta, Maine business owners considering an S Corp election can use our LLC vs S-Corp Tax Calculator for Augusta to estimate whether an S Corp structure saves taxes at your current income level for 2026.
How Do You Track Digital Assets in Monthly Close for 2026?
Quick Answer: In 2026, IRS Form 1099-DA requires brokers to report digital asset transactions. Your monthly close must capture all crypto purchases, sales, and business payments in digital assets — with cost basis, fair market value, and gain/loss calculations for each event.
Digital asset reporting is one of the biggest new compliance burdens for 2026. The IRS Form 1099-DA — the Digital Asset Proceeds from Broker Transactions form — expanded reporting requirements that were first introduced for the 2025 tax year. If your business accepts, holds, or transacts in cryptocurrency or other digital assets, monthly tracking is now mandatory.
Monthly Digital Asset Tracking Steps
- Download and review all exchange transaction reports for the month
- Record date acquired, cost basis, and fair market value at time of each transaction
- Calculate realized gains or losses for each disposal event
- Log any business income received as cryptocurrency at fair market value on the date received
- Reconcile 1099-DA reports from brokers against your own records
- Flag short-term vs. long-term gains — holding periods matter for tax rate calculations
- Reconcile 1099-DA reports from brokers against your own records
- Flag short-term vs. long-term gains — holding periods matter for tax rate calculations
The IRS is prioritizing digital asset enforcement in 2026. The agency’s expanded use of data technology means discrepancies between 1099-DA reports and tax returns get flagged quickly. Monthly reconciliation is your best defense. Review the latest guidance directly at IRS.gov to stay current with any Form 1099-DA updates.
Pro Tip: Use dedicated crypto tax software (such as CoinTracker or Koinly) to automate monthly digital asset reconciliation. Export reports in a format compatible with your main accounting software.
What Tax Strategy Steps Belong in Your Monthly Close?
Quick Answer: Beyond bookkeeping, your monthly close checklist should include a tax strategy review. This means checking deduction pacing, retirement contribution progress, entity structure efficiency, and any OBBBA-specific planning opportunities for 2026.
The most successful business owners treat monthly close as more than a bookkeeping exercise. They use it as a tax strategy checkpoint. Each month, you have the opportunity to identify deductions you are missing, catch entity structure inefficiencies, and project your year-end tax position with precision. This is where the real tax savings happen — not at the last minute in April.
Monthly Tax Strategy Review Items
- Retirement contribution pacing: Are you on track to maximize your 2026 401(k) limit of $24,500? For ages 60–63, the SECURE 2.0 catch-up limit is $11,250 for 2026.
- OBBBA charitable deduction: Non-itemizers can now deduct charitable contributions in 2026. Track monthly donations with receipts.
- Bonus depreciation planning: The OBBBA restored enhanced bonus depreciation. If you plan to buy equipment, timing matters. Monthly reviews help you decide when to purchase.
- Pass-through entity tax (PTET): If you operate in Minnesota or another state that extended PTET for 2026, confirm your state tax election is active and payments are current.
- ERC claim deadlines: Two-year deadlines for Employee Retention Credit administrative protests and refund claims expire in 2026. Check your ERC status monthly.
- Tariff cost tracking: For importers, tariff refunds are now taxable in 2026. Track tariff refunds received monthly to ensure proper income reporting.
Entity Structure Efficiency Check
Your monthly close is also the right time to review your entity structure. If your business is growing and you have not evaluated whether an LLC or S Corp serves you better, now is the time. For 2026, S Corp owners can split income between salary and distributions — reducing self-employment tax significantly at higher income levels. Our entity structuring team can model the exact savings for your situation.
Inflation remains elevated at 3.8% through April 2026. As operating costs rise, the tax efficiency of your entity structure has a larger impact on cash flow. A business netting $200,000 per year as an S Corp may save $10,000–$15,000 in self-employment taxes compared to operating as a sole proprietor, depending on the reasonable salary set. Review this calculation in your monthly close if net income is increasing.
Did You Know? According to IRS data cited by Accounting Today, around 30 million tax returns claimed the new senior deduction in 2026 — many without fully understanding the phase-out thresholds. Monthly tax strategy reviews help you identify similar eligibility issues before filing.
Year-End Projection Update
Every month, update your year-end tax projection. Use your current-month and year-to-date figures to project where you will land by December 31, 2026. Then identify the specific actions — additional estimated payments, accelerated deductions, retirement contributions, or capital purchases — that can reduce your projected tax liability before year-end. Our MERNA Method provides a structured framework for these monthly strategy reviews.
This information is current as of 5/27/2026. Tax laws change frequently. Verify updates with the IRS if reading this later.
Uncle Kam in Action: Restaurant Owner Saves $31,200
Client Snapshot: Maria runs a mid-sized restaurant in Augusta, Maine. Her business generates approximately $620,000 in annual revenue and employs 14 staff, including tipped employees.
The Challenge: Maria came to Uncle Kam in February 2026 in a panic. She had skipped monthly close for three months. Her books were behind, she had missed the Q1 estimated tax payment, and she had no documentation for the new OBBBA tip income deduction. Her previous accountant had filed her 2025 return without flagging the potential 2026 tip deduction — leaving thousands of dollars on the table.
Furthermore, Maria had purchased $48,000 in kitchen equipment in January 2026 but had no records organized to support a bonus depreciation claim. She was also unaware that some of her overseas food supply payments may trigger the new 1% excise tax on overseas remittances.
The Uncle Kam Solution: Uncle Kam immediately implemented a structured monthly close checklist tailored to Maria’s restaurant. We:
- Caught her up on three months of bank reconciliations and expense categorization
- Set up a payroll system that separately tracked tip income by employee — required for the 2026 OBBBA tip deduction
- Documented the $48,000 equipment purchase and structured the bonus depreciation election to maximize her 2026 write-off
- Calculated her Q2 2026 estimated payment — due June 15, 2026 — based on actual year-to-date income, preventing a further underpayment penalty
- Reviewed her overseas supplier payments and flagged those subject to the 1% excise tax for separate accounting treatment
The Results: By implementing a disciplined monthly close checklist, Maria’s 2026 tax position improved dramatically:
- Tax Savings: $31,200 — combining tip income deduction, bonus depreciation, and corrected expense categorization
- Penalty Avoidance: $2,800 in estimated tax underpayment penalties avoided through timely Q2 payment
- Investment in Uncle Kam: $4,200 for the monthly advisory engagement
- First-Year ROI: 640% — $34,000 in combined savings and penalty avoidance on a $4,200 investment
Maria’s story is not unique. Most business owners who skip the monthly close lose thousands each year to missed deductions and avoidable penalties. See more stories like hers on our client results page.
Next Steps
Ready to build a monthly close checklist that keeps your business tax-optimized throughout 2026? Here is how to get started today. Our tax advisory team can build a custom monthly close framework for your business.
- Step 1: Reconcile your bank accounts for the current month before June 5, 2026.
- Step 2: Calculate and schedule your Q2 2026 estimated tax payment — due June 15, 2026.
- Step 3: Set up payroll records to separately log tip income per OBBBA requirements effective June 12, 2026.
- Step 4: Review your entity structure using our LLC vs S-Corp Tax Calculator for Augusta, Maine to see if a 2026 entity change saves you money.
- Step 5: Schedule a monthly advisory call with Uncle Kam’s tax strategy team to keep your 2026 close on track every month.
Related Resources
- 2026 Tax Strategy Planning for Business Owners
- LLC vs S Corp Entity Structuring Guide
- Business Tax Preparation and Filing Services
- 2026 Business Tax Deadline Calendar
- Bookkeeping and Payroll Business Solutions
Frequently Asked Questions
How long does a monthly close checklist typically take to complete?
For most small businesses, a thorough monthly close takes four to eight hours. This depends on transaction volume, the number of bank accounts, payroll complexity, and whether you hold digital assets. Businesses with well-organized systems and accounting software can often complete the process faster. However, rushing the close introduces errors. It is better to spend a full day doing it right than to redo it later under audit pressure. For 2026, add extra time to address OBBBA compliance items — particularly tip income and overseas remittance tracking.
What happens if I miss my Q2 2026 estimated tax payment on June 15?
Missing the June 15, 2026 estimated tax deadline triggers an underpayment penalty. The IRS calculates the penalty based on the amount underpaid and the number of days the payment is late. However, you can reduce the penalty by paying as soon as possible after the deadline. Additionally, if you meet the safe harbor threshold — paying at least 100% of your prior-year tax liability, or 90% of your current-year liability — the underpayment penalty does not apply. Visit the IRS Payments portal to schedule catch-up payments quickly through EFTPS or Direct Pay.
Do I need a separate digital asset log for my monthly close in 2026?
Yes. For 2026, the IRS expanded digital asset reporting through Form 1099-DA. If your business accepts, holds, or transacts in cryptocurrency, you need a dedicated log. This log should capture every transaction date, the type of asset, the cost basis at acquisition, the fair market value at the time of each transaction, and the resulting gain or loss. Your main accounting software likely does not handle crypto natively. Use a dedicated crypto tax platform and reconcile it monthly as part of your standard monthly close checklist. Discrepancies between your records and broker-issued 1099-DAs are a major IRS red flag in 2026.
How does the OBBBA tip income deduction affect my monthly close?
The OBBBA tip income deduction final regulations took effect June 12, 2026. Under these rules, qualifying employers can deduct a portion of tip income paid to tipped employees. However, the IRS identified reconciliation problems with this deduction during the 2026 tax filing season — specifically, businesses could not match deduction amounts on returns with amounts reported by employers. The fix is monthly documentation. Each month, record total tips paid by employee and by date. Maintain separate payroll records for tip income. This creates the paper trail required to support the deduction when you file. Hospitality businesses that skip this monthly step risk having the deduction denied.
Should I include a retirement contribution review in my monthly close checklist?
Absolutely. For 2026, the 401(k) contribution limit is $24,500 per participant. If you or your employees are age 50 or older, the catch-up limit is $8,000. For ages 60–63, SECURE 2.0 raised the catch-up to $11,250 for 2026. These limits represent significant tax-deferred savings. Including a monthly retirement contribution pacing check ensures you are on track to max out these accounts by December 31, 2026. It also confirms that employee deferrals are being deposited correctly and on time — a requirement enforced by the Department of Labor. Failure to deposit employee deferrals promptly is one of the most commonly cited plan compliance errors by the Department of Labor’s EBSA.
What is the best way to track OBBBA overseas remittance taxes in my monthly close?
The 1% excise tax on overseas remittances is a new 2026 obligation for businesses that make payments to foreign persons or entities. The best approach is to create a dedicated expense category in your accounting software labeled “Overseas Remittances — 2026 Excise Tax Tracking.” Every time you make a qualifying overseas payment, log the gross amount and set aside 1% for the excise tax liability. At quarterly close, reconcile this account against your actual payments. Consult the official guidance at IRS.gov International Businesses for the most current rules, as further regulatory guidance was expected in 2026. Importers and retailers are the most commonly affected, but any business with overseas suppliers should review this monthly.
Last updated: May, 2026