
Mega Backdoor Roth Contribution Limits 2026: The Complete Advisor Playbook
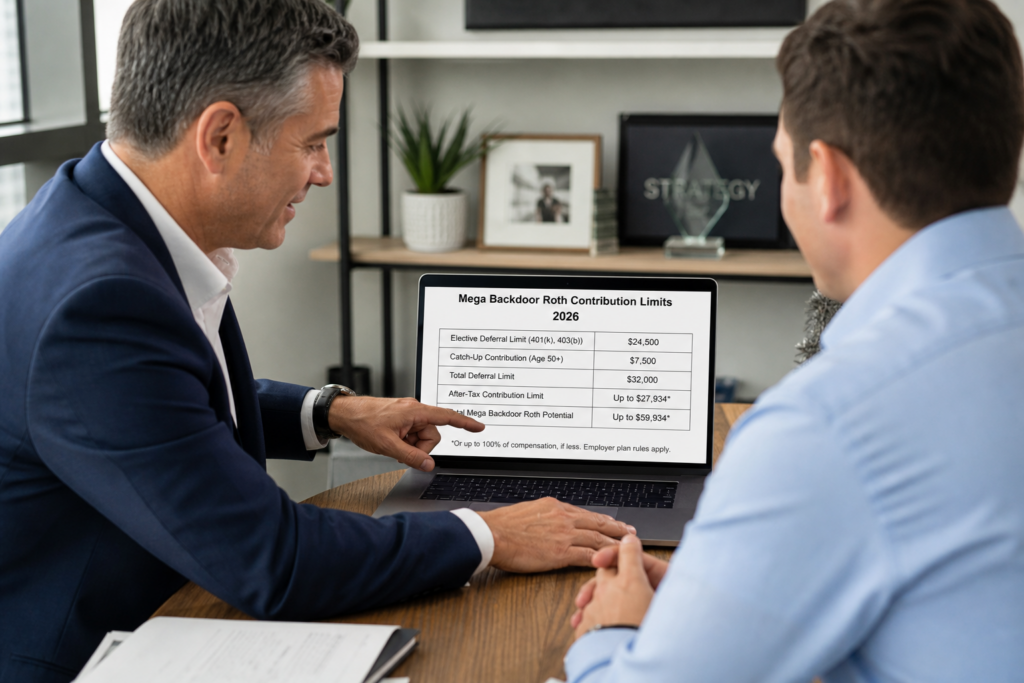
The mega backdoor Roth contribution limits 2026 offer high earners a rare chance to move up to $72,000 into tax-free growth. For the 2026 tax year, the total 401(k) plan limit rose to $72,000, up from $70,000 in 2025. As a result, tax pros can help clients shelter far more than the standard deferral cap. This guide breaks down the exact math, rules, and advisory playbook. If you serve high-income clients in Central Florida, our Orlando tax advisor team can help you execute.
Table of Contents
- Key Takeaways
- What Is a Mega Backdoor Roth?
- How Much Can Clients Contribute With a Mega Backdoor Roth in 2026?
- Who Qualifies for the Mega Backdoor Roth Strategy?
- How Does SECURE 2.0 Change the Strategy in 2026?
- How Do You Execute a Mega Backdoor Roth Step by Step?
- What Mistakes Should You Avoid With This Strategy?
- Uncle Kam in Action
- Next Steps
- Related Resources
- Frequently Asked Questions
Key Takeaways
- The 2026 total 401(k) limit is $72,000, up from $70,000 in 2025.
- After-tax room fills the gap between deferrals and the $72,000 cap.
- The mega backdoor Roth contribution limits 2026 have no income cap.
- Clients need a plan that allows after-tax contributions and in-plan conversions.
- This strategy positions you to win high-net-worth advisory clients.
What Is a Mega Backdoor Roth?
Quick Answer: A mega backdoor Roth lets clients make large after-tax 401(k) contributions. They then convert those dollars to Roth for tax-free growth.
A mega backdoor Roth is a two-step move inside a workplace retirement plan. First, the client makes after-tax contributions above the normal deferral limit. Next, they convert those after-tax dollars into a Roth account. As a result, the money grows tax-free for life.
This differs from the standard backdoor Roth. The standard version uses a traditional IRA and moves only about $7,000 per year. However, the mega version works inside a 401(k). Therefore, it can shelter far more money. For high earners, that difference matters a lot.
Why After-Tax Contributions Matter
After-tax contributions are different from Roth deferrals. The client pays tax on the money first. Then they place it in the plan. Consequently, only the growth is taxed later, unless they convert quickly. When you convert right away, the growth stays tax-free too.
How This Fits a Tax Plan
Smart advisors sequence this strategy inside a full plan. For example, our proactive tax strategy service layers Roth moves with entity and retirement choices. The IRS explains Roth basics in its Roth comparison chart. You should review that chart with each client.
Pro Tip: Convert after-tax dollars fast. This keeps taxable earnings near zero at conversion.
How Much Can Clients Contribute With a Mega Backdoor Roth in 2026?
Quick Answer: The 2026 total plan limit is $72,000. After-tax room equals $72,000 minus deferrals and employer money.
The mega backdoor Roth contribution limits 2026 flow from the IRS Section 415(c) cap. For 2026, that total limit is $72,000. It covers three buckets. First, employee deferrals. Second, employer match or profit sharing. Third, after-tax contributions. The IRS confirms these figures in its retirement contributions guidance.
To find the after-tax room, start with $72,000. Then subtract the client’s $24,500 deferral. Next, subtract any employer contribution. The remaining amount is the after-tax space. That space becomes the mega backdoor Roth.
2026 Limit Breakdown
| 2026 Limit Type | Amount |
|---|---|
| Employee deferral (under 50) | $24,500 |
| Catch-up (age 50+) | $8,000 |
| Super catch-up (ages 60-63) | $11,250 |
| Total plan limit (under 50) | $72,000 |
| Total plan limit (age 50+) | $80,000 |
A Real Calculation Example
Consider a client under 50. She defers the full $24,500. Her employer adds a $10,000 match. Therefore, $34,500 is used. That leaves $37,500 of after-tax room. She contributes that amount and converts it to Roth. As a result, $37,500 now grows tax-free forever.
Want to model client scenarios fast? Use our Mega Backdoor Roth strategy tool to estimate 2026 after-tax room. It helps you show clients the tax-free growth in minutes.
Did You Know? The 2026 total limit of $72,000 rose $2,000 from the 2025 figure of $70,000.
Who Qualifies for the Mega Backdoor Roth Strategy?
Quick Answer: Clients qualify if their plan allows after-tax contributions plus in-plan Roth conversions or in-service withdrawals.
Not every plan supports this move. The plan document must allow two features. First, it must permit after-tax contributions above deferrals. Second, it must allow in-plan Roth conversions or in-service withdrawals. Without both, the strategy fails.
The best part is the income rule. There is no income cap for this strategy. Roth IRA contributions phase out at $150,000 to $165,000 for single filers in 2026. However, the mega backdoor Roth ignores those limits. Therefore, high earners love it.
Best-Fit Client Profiles
- Physicians and executives who already max deferrals.
- Tech workers with generous after-tax plan features.
- Business owners running solo 401(k) plans.
- High-net-worth individuals seeking tax-free growth.
Solo 401(k) Owners Have an Edge
Business owners can design their own plan. As a result, they control the after-tax feature. This makes the strategy powerful for founders. Pair it with smart entity structuring choices for even more savings. Many small business owners miss this simple win.
Pro Tip: Always request the plan document first. Confirm both features before you promise results.
How Does SECURE 2.0 Change the Strategy in 2026?
Quick Answer: SECURE 2.0 forces high earners into Roth catch-ups in 2026. This makes the mega backdoor Roth even more useful.
SECURE 2.0 reshaped catch-up rules in 2026. Now, employees who earned more than $150,000 in 2025 must route catch-up dollars to Roth. In other words, the pretax catch-up shelter disappeared for high earners. You can read the law text on Congress.gov.
This shift changes client behavior. A 55-year-old in the 24% bracket lost about $1,900 in yearly deductions. Meanwhile, the $11,250 super catch-up at ages 60 to 63 lost roughly $2,700 in shelter. Consequently, clients now seek other tax-free growth. That is where the mega backdoor Roth shines.
Why This Creates Advisory Demand
High earners feel confused by these changes. Therefore, they want expert help. This is your chance to sell advisory work. Selling and delivering advisory are two different skills. The right tax advisory operating system supports both, with software, training, and inbound leads in one place. Learn how the Uncle Kam marketplace helps tax pros transition to advisory.
Pairing With HSAs
Many advisors now stack HSAs with the mega backdoor Roth. In 2026, HSA limits are $4,400 self-only and $8,750 family. Clients age 55 and older add $1,000 more. The IRS details these caps in Publication 969. Together, these accounts build strong tax-free buckets.
How Do You Execute a Mega Backdoor Roth Step by Step?
Quick Answer: Confirm plan features, max deferrals, add after-tax dollars, then convert to Roth quickly.
The process is simple once the plan allows it. Still, timing matters a lot. You want to convert fast to avoid taxable earnings. Below is a clean sequence for the 2026 tax year.
The Five-Step Playbook
- Confirm the plan allows after-tax contributions and conversions.
- Max the $24,500 deferral first to secure that space.
- Calculate after-tax room up to the $72,000 cap.
- Fund after-tax contributions through payroll.
- Convert to Roth quickly to lock in tax-free growth.
Documenting the Conversion
Clients report conversions on Form 1099-R. Keep clean records for basis tracking. The IRS explains rollover reporting in its rollover distributions guidance. Good records protect your client during any audit.
Did You Know? Some plans auto-convert after-tax dollars daily. This removes almost all taxable earnings.
What Mistakes Should You Avoid With This Strategy?
Quick Answer: Avoid slow conversions, exceeding the $72,000 cap, and ignoring the plan’s rules.
Small errors can cost real money. First, slow conversions create taxable growth. Second, over-funding past $72,000 triggers penalties. Third, some plans limit after-tax contributions each year. Therefore, you must check every detail.
Common Advisor Errors
- Forgetting to subtract the employer match from the cap.
- Missing the plan’s separate after-tax contribution limit.
- Letting after-tax dollars sit and grow before converting.
- Ignoring state tax rules on conversions.
Coordinating the Whole Plan
Never run this move in isolation. Instead, coordinate it with the full picture. Layer it with deductions, entity choices, and retirement plans. Our ongoing tax advisory service helps you build these plans. You can also study real outcomes on our client results page. Before you move to next steps, review your process with an experienced Orlando advisory team.
Pro Tip: Book a Free Strategy Session to sharpen your delivery and get a personalized roadmap for scaling your advisory firm.
Uncle Kam in Action: The EA Who Landed a $600K Physician Client
Client Snapshot: Maria is an Enrolled Agent with eight years of experience. She hit a revenue ceiling doing tax prep. She wanted high-net-worth clients but felt she could not compete with big CPA firms.
Financial Profile: Her target prospect was an anesthesiologist earning $600,000 per year. He already maxed his 401(k). Still, he paid a huge federal tax bill each year.
The Challenge: The physician felt stuck. His Roth IRA was blocked by income limits. Meanwhile, SECURE 2.0 removed his pretax catch-up shelter in 2026. He wanted tax-free growth but saw no path forward.
The Uncle Kam Solution: Maria used the mega backdoor Roth contribution limits 2026 as her lead strategy. First, she confirmed his plan allowed after-tax contributions and in-plan conversions. Next, she calculated his room. He deferred $24,500 and received a $20,000 employer match. That left $27,500 of after-tax space toward the $72,000 cap. She had him fund it and convert quickly.
The Results: The physician moved $27,500 into tax-free Roth growth. Over 20 years at 7% growth, that becomes roughly $106,000 in tax-free money. Maria projected long-term tax savings above $30,000 on future withdrawals. She charged a $6,000 advisory fee for the first year.
Return on Investment: The client gained projected tax savings of $30,000 against a $6,000 fee. That is a first-year ROI of 5x. Moreover, Maria won a recurring advisory client. She now uses this playbook to attract more physicians. See more wins on our client results page.
Next Steps
Ready to add this strategy to your firm? The gap between preparers who file returns and advisors who command $6,000 engagements comes down to systems, training, and warm leads. Uncle Kam provides the AI software, MERNA certification, and high-value client flow you need to scale. Learn how the Uncle Kam marketplace helps tax pros transition to advisory. Then take these clear actions now.
- Review each client’s plan document for after-tax features.
- Build a 2026 after-tax room worksheet for prospects.
- Explore our proactive tax strategy service for delivery support.
- Book a Free Strategy Session with a growth strategist today.
Related Resources
Frequently Asked Questions
What are the mega backdoor Roth contribution limits 2026?
The 2026 total plan limit is $72,000. After-tax room equals $72,000 minus deferrals and employer money. Clients convert that room to Roth.
Is there an income limit for this strategy?
No. Unlike a Roth IRA, the mega backdoor Roth has no income cap. Therefore, high earners can still use it in 2026.
How fast should clients convert after-tax dollars?
Convert as fast as the plan allows. Quick conversions keep taxable earnings near zero. Some plans convert daily automatically.
Does every 401(k) plan allow this move?
No. The plan must allow after-tax contributions and conversions. Always check the plan document before you promise results to a client.
Can business owners use a solo 401(k) for this?
Yes. Owners can design a plan with after-tax features. As a result, founders gain a powerful tax-free growth tool for 2026.
How much can advisors charge for this planning?
Fees often range from $3,000 to $8,000 per plan. The tax-free growth easily justifies the cost. Value pricing works well here.
This information is current as of 7/12/2026. Tax laws change frequently. Verify updates with the IRS if reading this later.
Last updated: July, 2026

