Iowa Tax Conformity Federal Changes 2026 Guide
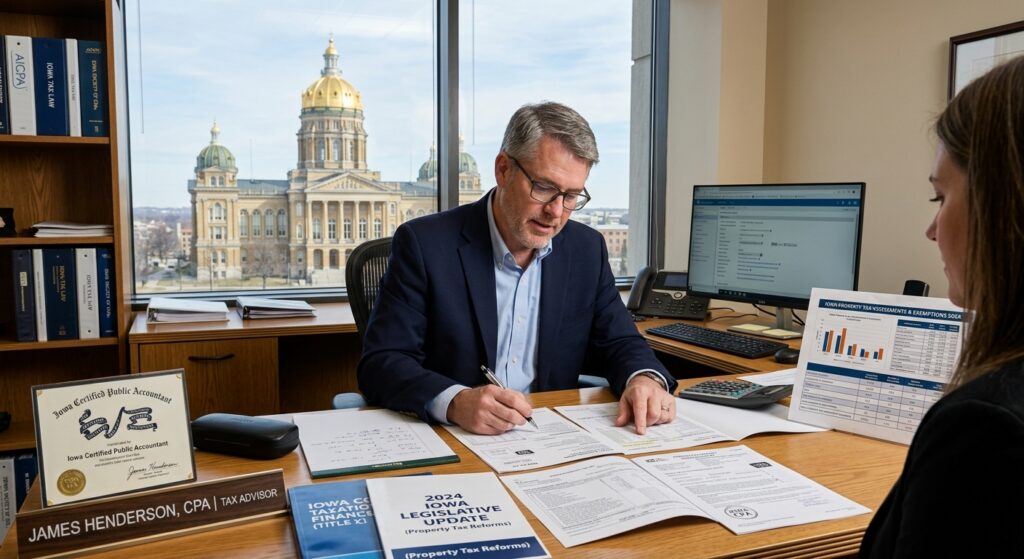
Iowa’s 2026 legislative session concluded with landmark property tax reforms that will reshape local government budgets and create unprecedented advisory opportunities for tax professionals. The Iowa tax conformity federal changes 2026 represent a critical inflection point for practitioners serving business owners, real estate investors, and high-income clients across the state. With property tax caps limiting revenue growth to just 2% annually starting in 2027, local governments face severe fiscal pressure while Iowa taxpayers anticipate nearly $4.2 billion in savings over six years.
Table of Contents
Used by 2,400+ tax professionals
- Key Takeaways
- What Are Iowa Tax Conformity Federal Changes 2026?
- How Do Iowa Tax Conformity Federal Changes 2026 Affect Your Clients?
- What Property Tax Changes Should Iowa Practitioners Understand?
- How Can Tax Professionals Leverage These Changes for Advisory Revenue?
- What Federal Provisions Affect Iowa Taxpayers in 2026?
- What Compliance Requirements Must Iowa Tax Professionals Monitor?
- Uncle Kam in Action: Des Moines CPA Pivots to Advisory
- Next Steps
- Frequently Asked Questions
- Related Resources
Key Takeaways
- Iowa’s 2026 property tax cap limits most local government revenue growth to 2% starting in the 2027-2028 fiscal year.
- Iowa taxpayers will save an estimated $4.2 billion over six years from property tax reforms.
- Federal standard deductions for 2026 are $35,500 for married filing jointly and $18,150 for single filers.
- Iowa’s new constitutional amendment requires a two-thirds legislative majority to raise income or corporate tax rates.
- Tax professionals have significant advisory opportunities helping clients navigate property tax assessments and planning strategies.
What Are Iowa Tax Conformity Federal Changes 2026?
Quick Answer: Iowa tax conformity federal changes 2026 include state legislative property tax caps, federal IRC alignment updates, and new constitutional protections against tax rate increases requiring supermajority approval.
The 2026 Iowa legislative session ended on May 3, 2026, with Governor Kim Reynolds signing sweeping property tax reform legislation that fundamentally alters the fiscal landscape for local governments and taxpayers. This represents one of the most significant shifts in Iowa’s tax policy in over a decade.
Federal Tax Code Conformity Framework
Iowa follows a “rolling conformity” approach to the federal Internal Revenue Code. This means the state automatically adopts most federal tax changes. However, practitioners must understand that Iowa state tax law may include specific decoupling provisions where state treatment differs from federal rules.
For the 2026 tax year, Iowa conforms to federal provisions made permanent by the One Big Beautiful Bill (OBBB) passed in July 2025. This includes the continuation of TCJA provisions that were scheduled to sunset, such as enhanced standard deductions and revised tax brackets.
State-Level Legislative Changes
Beyond federal conformity, Iowa enacted state-specific tax changes during the 2026 session. The property tax cap legislation represents the cornerstone of these reforms. Additionally, lawmakers advanced a constitutional amendment to voters requiring a two-thirds supermajority in both legislative chambers to raise income or corporate tax rates.
Pro Tip: Tax professionals should educate clients about the constitutional amendment protection. This creates stability for long-term tax planning and business investment decisions in Iowa.
Revenue Impact and Fiscal Context
Iowa’s fiscal environment shows significant stress. State total receipts from July through April 2026 fell by $798 million compared to the prior fiscal year, according to the Iowa Department of Management. This revenue decline creates fiscal pressure that amplifies the impact of property tax caps on local governments.
For context, this revenue drop occurs while inflation remains elevated. The 2% property tax cap falls below the U.S. annual inflation rate experienced since 2021, creating a real-terms revenue reduction for counties and cities.
How Do Iowa Tax Conformity Federal Changes 2026 Affect Your Clients?
Quick Answer: Clients benefit from federal standard deduction increases, property tax savings, and long-term rate stability, but face potential service reductions from local governments operating under revenue caps.
Tax professionals serving Iowa clients must understand how these changes create both opportunities and challenges across different taxpayer categories. The Iowa tax guide for 2026 provides detailed planning strategies for navigating these changes.
Business Owner Implications
For business owners, Iowa’s property tax cap creates competitive advantages. Commercial property owners will see slower property tax growth, improving cash flow predictability. This is particularly valuable for businesses with significant real estate holdings or those operating on thin margins.
Additionally, the constitutional amendment protecting against income and corporate tax rate increases without supermajority approval creates unprecedented tax certainty for business planning and investment decisions. This stability allows for more aggressive growth strategies and long-term capital allocation.
Real Estate Investor Considerations
Real estate investors face a complex landscape under Iowa tax conformity federal changes 2026. The new homestead exemption provides a minimum of $5,500 or 10% of a home’s value (up to $20,000), indexed to inflation. This protection shields owner-occupied residential properties from assessment growth.
However, rental properties and commercial real estate do not receive homestead protection. Investors in these asset classes benefit from the 2% levy cap but must plan for potential service reductions from local governments. Tax professionals should advise real estate investor clients to evaluate property condition and municipal service quality as investment criteria.
High-Income Taxpayer Benefits
High-income individuals benefit from both federal and state tax stability in 2026. The federal standard deduction for married filing jointly increased to $35,500 for 2026, up from prior years. Single filers receive an $18,150 standard deduction. These higher thresholds reduce taxable income for all taxpayers but provide the greatest absolute benefit to high earners.
Furthermore, federal tax brackets remain favorable. The 12% bracket for married filing jointly extends from $24,801 to $100,800 of taxable income in 2026. The 22% bracket for single filers covers income between $50,401 and $105,700. These inflation-adjusted brackets prevent bracket creep and preserve purchasing power.
Tax Professional Practice Impact
Solo practitioners and small firms face a critical decision point. Compliance-only practices will see pressure as tax software automates routine returns. However, tax advisory opportunities expand significantly for professionals who pivot to proactive planning services.
The Iowa tax conformity federal changes 2026 create multiple advisory engagement opportunities. These include property tax assessment appeals, entity structure optimization under stable rate environments, real estate investment analysis incorporating service quality risks, and multi-year tax projections leveraging rate certainty.
What Property Tax Changes Should Iowa Practitioners Understand?
Quick Answer: The 2% property tax levy cap starts in fiscal year 2027-2028. It limits most local government revenue growth but includes exceptions for county hospitals and emergency management agencies.
Iowa’s property tax legislation represents the most significant reform since 2013, when the state cut commercial and industrial property taxes and created backfill payments to local governments. Those backfill payments end in approximately four years, creating additional fiscal pressure.
The 2% Cap Mechanics
Starting with the 2027-2028 fiscal year, most city and county general levy revenue growth faces a 2% annual cap. This cap applies regardless of property value appreciation. For example, if property values increase 5% but the levy is capped at 2%, effective tax rates must decline.
The legislation includes targeted exceptions. County hospitals can increase levies by up to 4% annually. Emergency management agencies receive a 3% cap. School funding remains entirely exempt from the cap structure. These carve-outs reflect legislative priorities for essential services.
| Entity Type | Annual Revenue Growth Cap | Effective Date |
|---|---|---|
| Cities (General Levy) | 2% | FY 2027-2028 |
| Counties (General Levy) | 2% | FY 2027-2028 |
| County Hospitals | 4% | FY 2027-2028 |
| Emergency Management | 3% | FY 2027-2028 |
| School Districts | No Cap | N/A |
Homestead Exemption Enhancement
The 2026 legislation establishes an enhanced homestead exemption worth at least $5,500 or 10% of a home’s assessed value, with a maximum of $20,000. This exemption amount increases with inflation annually, providing automatic protection against bracket creep.
Tax professionals should ensure clients file for homestead exemptions promptly. Failure to claim the exemption results in unnecessary tax liability. For a home assessed at $200,000, the full $20,000 exemption reduces the taxable base to $180,000, creating material savings.
TIF Limitations and Development Impact
Tax increment financing (TIF) agreements now face a 23-year maximum term. Previously, some TIF districts extended for 30 years or longer. The new limitation affects development incentives and economic development strategies across Iowa municipalities.
For business structure planning, practitioners should evaluate TIF district participation carefully. Shorter TIF terms may reduce the total incentive value but also mean properties return to general tax rolls sooner, potentially benefiting school districts and other non-TIF entities.
Local Government Response and Service Implications
As reported by Axios Des Moines, local governments are exploring consolidation and shared services to manage within the new revenue constraints. The Taxpayers Association of Central Iowa is actively discussing government merger possibilities, though voters historically reject consolidation proposals.
Practitioners should advise clients that while property taxes decrease, municipal service levels may decline. This creates planning considerations for businesses dependent on infrastructure quality, emergency services response times, and economic development support.
How Can Tax Professionals Leverage These Changes for Advisory Revenue?
Quick Answer: Tax professionals can build recurring advisory revenue through property tax assessment appeals, multi-year tax projections, real estate investment analysis, and entity structure optimization leveraging Iowa’s new tax rate protections.
The Iowa tax conformity federal changes 2026 create unprecedented advisory opportunities for tax professionals willing to move beyond compliance. Solo practitioners especially benefit from building proactive tax strategy engagements that generate higher fees and client retention.
Property Tax Assessment Appeal Services
With property tax caps limiting revenue growth, assessors face pressure to maximize assessed values on individual properties. This creates systematic over-assessment risk. Tax professionals can offer assessment review and appeal services as annual recurring engagements.
A typical assessment appeal engagement includes reviewing the county assessor’s valuation, comparing to comparable properties, preparing appeal documentation, and representing the client at assessment board hearings. Fees typically range from $500 to $2,500 depending on property complexity.
Pro Tip: Position assessment appeal services as risk-free contingency engagements. Charge 30-50% of first-year tax savings. Clients pay nothing if the appeal fails, creating easy yes decisions.
Multi-Year Tax Projection Modeling
Iowa’s constitutional amendment creates rate certainty impossible to achieve in most states. Tax professionals can build multi-year projection models showing clients their tax liability under various income scenarios, entity structures, and investment decisions.
These projections support business sale timing, Roth conversion strategies, income acceleration or deferral decisions, and retirement distribution planning. A comprehensive multi-year projection engagement typically commands fees from $2,000 to $5,000 depending on complexity.
Real Estate Investment Due Diligence
Real estate investors need specialized due diligence evaluating not just property tax history but also municipal fiscal health. Under revenue caps, cities with weak finances may cut services affecting property values and tenant satisfaction.
Tax professionals can partner with real estate advisors to provide fiscal analysis of target municipalities. This includes reviewing city budgets, assessing service level trends, analyzing infrastructure maintenance backlogs, and projecting future tax levy increases within the 2% cap.
SALT Planning and Business Location Strategy
Iowa’s tax environment has become significantly more competitive for business attraction. Tax professionals can advise business owners on state and local tax (SALT) planning strategies leveraging Iowa’s advantages. This includes comparing total tax burdens across states, evaluating nexus considerations, and structuring multi-state operations tax-efficiently.
For businesses considering Iowa expansion or relocation, practitioners should prepare comprehensive SALT analyses demonstrating the competitive advantage of Iowa’s constitutional tax rate protection and property tax caps compared to neighboring states.
What Federal Provisions Affect Iowa Taxpayers in 2026?
Quick Answer: Federal provisions include increased standard deductions, inflation-adjusted tax brackets, permanent TCJA provisions under OBBB, and new retirement savings initiatives like TrumpIRA accounts.
Iowa’s rolling conformity to the Internal Revenue Code means federal tax changes automatically affect Iowa taxpayers. Understanding these federal provisions is critical for accurate tax preparation and filing in 2026.
Standard Deduction and Tax Bracket Updates
For the 2026 tax year, the federal standard deduction increased to $35,500 for married couples filing jointly and $18,150 for single filers. These amounts represent inflation adjustments from prior years and apply to Iowa taxpayers under the state’s conformity rules.
Federal tax brackets also adjusted for inflation. The 12% bracket for married filing jointly covers taxable income from $24,801 to $100,800. Single filers face a 22% marginal rate on income between $50,401 and $105,700. These brackets prevent inflation from pushing taxpayers into higher rate categories.
| Filing Status | 2026 Standard Deduction | Key Bracket Threshold |
|---|---|---|
| Married Filing Jointly | $35,500 | 12% rate: $24,801 – $100,800 |
| Single | $18,150 | 22% rate: $50,401 – $105,700 |
| Head of Household | Verify current IRS guidance | Consult IRS.gov |
TCJA Permanence Under One Big Beautiful Bill
The Tax Cuts and Jobs Act of 2017 included provisions scheduled to sunset at the end of 2025. Congress passed the One Big Beautiful Bill in July 2025, making these provisions permanent. This includes the enhanced standard deduction structure, individual income tax rate reductions, and estate and gift tax exemption amounts.
Iowa taxpayers benefit from this certainty. High-net-worth individuals who rushed to complete gifting strategies in 2024 and early 2025 to beat the perceived sunset now face regret about accelerated transfers, as the exemptions became permanent with inflation adjustments continuing.
New Retirement Savings Opportunities
President Trump’s April 30, 2026 executive order established the TrumpIRA.gov initiative to expand retirement savings access for workers without employer-sponsored plans. This affects approximately 56 million Americans, including many Iowa small business owners and self-employed individuals.
The Federal Saver’s Match provides up to $1,000 annually for single filers with modified adjusted gross income below $35,500, and $2,000 for joint filers earning under $71,000. Tax professionals should proactively identify clients eligible for this match and guide them through account setup when the platform launches January 1, 2027.
Medicare IRMAA Thresholds
Medicare’s income-related monthly adjustment amount (IRMAA) creates significant tax planning opportunities. For 2026, IRMAA surcharges phase in at $109,000 for single filers and $218,000 for married filing jointly. Above these thresholds, Medicare beneficiaries pay an additional $95.70 monthly, or nearly $1,150 annually.
Tax professionals serving retirees should model Roth conversion strategies, income timing decisions, and qualified charitable distributions to manage income below IRMAA thresholds. A client earning $110,000 as a single filer could save $1,150 in Medicare premiums by shifting $1,000 to a Roth conversion two years earlier or deferring $1,000 of income.
What Compliance Requirements Must Iowa Tax Professionals Monitor?
Quick Answer: Practitioners must monitor Iowa Department of Revenue guidance on conformity updates, new homestead exemption claim procedures, and constitutional amendment implementation once voters approve the measure.
Iowa Department of Revenue Guidance
The Iowa Department of Revenue will issue administrative guidance implementing the 2026 legislative changes. Tax professionals should monitor the Iowa Department of Revenue website for bulletins, rule changes, and updated forms reflecting property tax cap mechanics and homestead exemption procedures.
Particular attention should focus on how the Department handles the transition period before the constitutional amendment faces voters in November 2026. If voters approve the two-thirds requirement for tax rate increases, additional administrative procedures will follow.
Federal IRS Updates and Information Returns
The IRS continues updates to information returns and reporting thresholds. The proposed $2,000 threshold for gambling businesses to report payouts represents one example of ongoing regulatory changes tax professionals must track.
Additionally, the IRS is sunsetting the Filing Information Returns Electronically (FIRE) system in favor of the new Information Returns Intake System (IRIS). Tax professionals must transition their business systems and workflows to accommodate this change.
Continuing Education on State-Specific Changes
Iowa practitioners should prioritize continuing education focusing on state-specific tax changes. The Iowa tax conformity federal changes 2026 create knowledge gaps that competing practitioners may not address. Specializing in Iowa tax law provides competitive differentiation for solo practitioners and small firms.
| Compliance Area | Key Monitoring Action | Timeline |
|---|---|---|
| Homestead Exemption Claims | Review new claim procedures from counties | Q3 2026 |
| Constitutional Amendment Vote | Track voter approval and implementation | November 2026 |
| TIF District Updates | Review 23-year maximum term impact | Ongoing |
| IRS IRIS System | Transition from FIRE system | 2026-2027 |
Uncle Kam in Action: Des Moines CPA Pivots to Advisory
Sarah Martinez runs a solo CPA practice in Des Moines serving approximately 180 individual and small business clients. For years, her practice focused exclusively on tax preparation and bookkeeping. Annual revenue plateaued around $145,000 with Sarah working grueling hours during tax season but underutilized the rest of the year.
The Challenge
When Iowa’s property tax cap legislation passed in May 2026, Sarah recognized a critical opportunity. Her clients included 47 real estate investors and 23 business owners with significant commercial property holdings. These clients would benefit tremendously from property tax assessment appeals and strategic planning around Iowa’s new tax environment.
However, Sarah lacked the systems, pricing models, and client communication frameworks to transition from compliance to advisory. She needed a structured approach to build proactive planning engagements while maintaining her existing preparation workflow.
The Uncle Kam Solution
Sarah joined Uncle Kam’s tax advisory platform in June 2026. She immediately accessed unlimited free tax assessments to run scenarios for her real estate investor clients, modeling the impact of property tax caps on their portfolios. The platform’s MERNA™ framework helped her identify multi-strategy opportunities combining entity restructuring, property tax appeals, and income timing.
Using Uncle Kam’s AI Tax Plan Generator, Sarah created professional deliverables for 32 clients showing projected tax savings under various scenarios. These deliverables positioned her as a strategic advisor rather than just a compliance preparer. The platform’s live coaching taught her how to price, present, and close advisory engagements.
The Results
Within four months, Sarah signed 28 clients to annual tax advisory retainers ranging from $3,500 to $8,500 each. Her first-year advisory revenue totaled $127,400. After deducting her $4,997 Uncle Kam platform investment, Sarah netted $122,403 in new advisory income—an 84% increase over her previous annual revenue.
More importantly, Sarah transformed her practice economics. Instead of grinding through tax season for preparation fees averaging $800 per client, she now delivers year-round advisory value commanding $5,000+ engagements. Her first-year return on investment exceeded 24x, and she projects crossing $300,000 in total revenue in 2027.
Sarah’s success demonstrates how Iowa tax conformity federal changes 2026 create transformational opportunities for tax professionals willing to embrace advisory services. See more results at Uncle Kam client success stories.
Next Steps
Tax professionals serving Iowa clients should take immediate action to capitalize on the opportunities created by Iowa tax conformity federal changes 2026:
- Review all client property holdings and identify assessment appeal opportunities before the 2027 tax bills arrive.
- Develop standardized advisory engagement templates for property tax planning, multi-year projections, and entity structure optimization.
- Educate clients about homestead exemption claims and ensure all owner-occupied properties receive the enhanced exemption.
- Build SALT comparison models demonstrating Iowa’s competitive advantage for business attraction and retention.
- Schedule a consultation to explore Uncle Kam’s tax advisory operating system and learn how unlimited assessments, structured training, and marketplace leads can transform your practice.
Frequently Asked Questions
When does Iowa’s 2% property tax cap take effect?
The 2% property tax levy cap takes effect for the 2027-2028 fiscal year. Local governments will begin operating under the revenue constraints starting in fiscal year 2027-2028. This gives municipalities approximately one year to prepare budget adjustments and explore service consolidation strategies.
Does Iowa conform to all federal tax code changes automatically?
Iowa follows “rolling conformity” to the federal Internal Revenue Code, meaning most federal changes apply automatically. However, Iowa law includes specific decoupling provisions where state treatment differs from federal rules. Tax professionals should consult Iowa Department of Revenue guidance for any state-specific modifications to federal provisions.
How much will Iowa taxpayers save from property tax reforms?
The Iowa Department of Management estimates taxpayers will save $4.2 billion over six years from the property tax cap legislation. Individual savings vary by property value, location, and local government spending patterns. Homeowners benefit from both the levy cap and enhanced homestead exemptions worth up to $20,000.
What is the constitutional amendment about tax rate increases?
Iowa voters will decide a constitutional amendment in November 2026 requiring a two-thirds supermajority in both legislative chambers to raise individual income or corporate tax rates. If approved, this creates constitutional protection against tax rate increases, providing unprecedented certainty for long-term tax planning and business investment decisions.
How can tax professionals charge for property tax assessment appeals?
Tax professionals typically offer assessment appeal services on a contingency basis, charging 30-50% of first-year tax savings. For example, if an appeal reduces assessed value by $50,000 and the effective tax rate is 2%, annual savings equal $1,000. A 40% contingency fee generates $400 for the practitioner with zero client risk if the appeal fails.
What federal standard deduction amounts apply for 2026?
For the 2026 tax year, the federal standard deduction is $35,500 for married filing jointly and $18,150 for single filers. These amounts include inflation adjustments and apply to Iowa taxpayers under the state’s rolling conformity to federal tax law. Head of household and other filing statuses should be verified with current IRS inflation adjustment guidance.
How does the TIF limitation affect economic development?
The new 23-year maximum term for tax increment financing agreements shortens the incentive period for some development projects. Developers receive less total incentive value, but properties return to general tax rolls sooner, benefiting school districts and other entities. Tax professionals should evaluate TIF participation carefully when advising clients on real estate development projects.
Should Iowa business owners consider entity restructuring in 2026?
Iowa’s constitutional tax rate protection creates an ideal environment for entity restructuring decisions. Business owners can model multi-year tax projections with confidence that rates won’t increase without supermajority legislative approval. Tax professionals should analyze S corporation elections, LLC structures, and multi-entity arrangements to optimize long-term tax efficiency under Iowa’s stable rate environment.
Related Resources
- Tax Advisory Operating System with Unlimited Assessments
- MERNA™ Tax Strategy Framework
- Tax Strategy Blog for Professionals
- Comprehensive Tax Planning Guides
- About Uncle Kam Tax Strategy
Last updated: May, 2026
This information is current as of 5/8/2026. Tax laws change frequently. Verify updates with the IRS or Iowa Department of Revenue if reading this later.