Franklin Schedule E Audit: 2026 Guide for Tennessee Rental Property Owners
A Franklin Schedule E audit can turn rental income into a stressful IRS review. For the 2026 tax year, real estate investors, business owners, and high-net-worth taxpayers in Franklin, Tennessee face rising scrutiny. Therefore, understanding audit triggers matters now more than ever. This guide explains what the IRS looks for, how to document rental activity, and how to defend your return with confidence.
Table of Contents
- Key Takeaways
- What Is a Franklin Schedule E Audit?
- What Triggers a Schedule E Audit in 2026?
- What Records Do You Need for a Schedule E Audit?
- How Much Can You Save By Handling It Correctly?
- How Do You Respond to an IRS Notice?
- Uncle Kam in Action
- Next Steps
- Related Resources
- Frequently Asked Questions
Key Takeaways
- A Franklin Schedule E audit reviews rental income, expenses, and depreciation claims.
- The 2026 baseline individual audit rate is roughly 0.4%.
- Recurring rental losses and high deductions raise audit risk sharply.
- Strong records defend deductions and reduce assessment exposure.
- Tennessee has no state income tax, but federal rules still apply fully.
What Is a Franklin Schedule E Audit?
Quick Answer: A Franklin Schedule E audit is an IRS review of rental income and expenses reported on Schedule E. It verifies that deductions, depreciation, and losses are legitimate.
Schedule E is the IRS form used to report income and loss from rental real estate, royalties, and pass-through entities. For Franklin investors, it usually covers rental homes, short-term rentals, and multifamily units. The IRS uses this form to confirm that reported figures match reality. Therefore, accuracy protects you.
You can review the official form directly at the IRS Schedule E instructions page. Furthermore, working with an experienced tax team helps you file cleanly. Many real estate investor tax strategies reduce audit exposure while maximizing legitimate deductions.
Who Files Schedule E in Franklin?
Many Franklin taxpayers file Schedule E each year. Common filers include the following groups:
- Rental property owners with long-term tenants
- Short-term rental hosts using platforms like Airbnb
- Partners receiving pass-through income from LLCs
- Investors earning royalty income
Why the IRS Focuses on Schedule E
Rental activity involves large deductions and depreciation. As a result, small errors can create big tax differences. The IRS knows that many filers overstate expenses or misclassify passive losses. Consequently, Schedule E returns draw extra attention when numbers look unusual.
Pro Tip: Keep a separate bank account for each rental property. Clean records make any Franklin Schedule E audit far easier to defend.
What Triggers a Schedule E Audit in 2026?
Quick Answer: A Franklin Schedule E audit is often triggered by recurring rental losses, high income, unusual deductions, or mismatched reporting. For 2026, income over $1 million carries a 2.5% audit rate.
The IRS uses automated systems to flag returns that fall outside normal patterns. For 2026, the baseline individual audit rate is roughly 0.4%. However, certain factors raise that risk dramatically. Therefore, knowing these triggers helps you file defensively.
You can learn more about audit selection at the IRS audits overview page. In addition, many Franklin investors benefit from proactive real estate tax planning strategies that reduce red flags before filing.
2026 Audit Rate Comparison
| Return Characteristic | Approximate 2026 Audit Rate |
|---|---|
| Baseline individual return | 0.4% |
| Returns over $1 million income | 2.5% |
| Returns over $10 million income | 8.5% |
| Self-employment, gross receipts over $500K | 3 to 5× baseline |
Common Schedule E Red Flags
Several patterns consistently draw IRS attention on rental returns. Watch for these issues:
- Recurring rental losses year after year
- Large deductions relative to reported rent
- Claiming full real estate professional status incorrectly
- Mismatched 1099-K or 1099-MISC amounts
- Personal use of a rental not properly allocated
Did You Know? The 2026 1099-K threshold returned to $20,000 and 200 transactions after the One Big Beautiful Bill Act, signed July 4, 2025.
Passive Loss Limitation Risks
The passive activity loss rules limit how much rental loss you can deduct. Most investors can deduct up to $25,000 in losses if income stays under phase-out limits. However, this benefit phases out between $100,000 and $150,000 of modified adjusted gross income. Therefore, high earners must document material participation carefully.
What Records Do You Need for a Schedule E Audit?
Quick Answer: You need income records, expense receipts, depreciation schedules, and proof of property basis. Complete documentation is your strongest defense in a Franklin Schedule E audit.
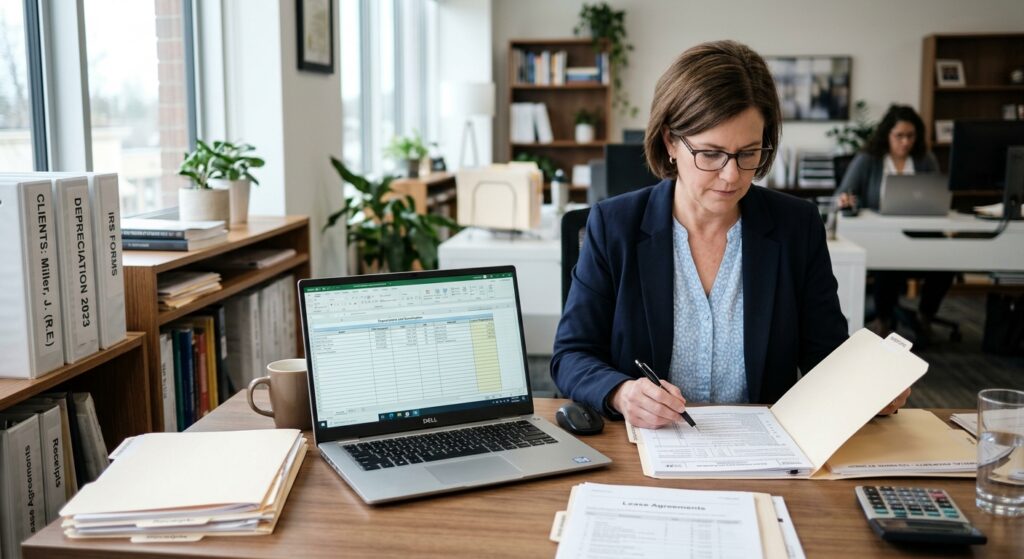
Documentation wins audits. When the IRS questions a deduction, you must prove it. As a result, organized records shift the outcome in your favor. Franklin investors should keep detailed files for every property. Furthermore, digital backups protect against loss.
The IRS explains recordkeeping standards in Publication 527 on residential rental property. In addition, a strong system supports smoother tax preparation and filing services each year. You can also find a Tax Preparation Near Me in Tennessee team to keep records audit-ready.
Essential Documents to Keep
Maintain these records for at least three years after filing. However, keep basis records much longer.
- Lease agreements and rent receipts
- Bank statements showing rental deposits
- Repair and maintenance invoices
- Property purchase and closing documents
- Depreciation schedules and prior returns
- Mileage logs for property visits
Documentation Standards Table
| Deduction Type | Required Proof |
|---|---|
| Repairs | Invoices and payment records |
| Depreciation | Basis and placed-in-service date |
| Mileage | Contemporaneous mileage log |
| Mortgage interest | Form 1098 from lender |
Pro Tip: If receipts are missing, you may reconstruct records and use reasonable approximations. Nevertheless, original documents remain far stronger.
How Much Can You Save By Handling It Correctly?
 Free Tax Write-Off Finder
Quick Answer: Proper documentation can protect thousands in deductions and prevent penalties. A well-defended Franklin Schedule E audit often results in no change to your return.
Audits carry real financial stakes. When the IRS disallows deductions, you owe back taxes plus interest and penalties. The accuracy-related penalty equals 20% of the underpayment. Therefore, defending your deductions saves both tax and penalty dollars.
Franklin business owners can estimate potential savings using our Small Business Tax Calculator for Franklin, Tennessee. Moreover, smart tax planning for business owners reduces audit exposure long before a notice arrives.
Sample Savings Calculation
Consider a Franklin investor with $40,000 in rental deductions under review. If the IRS disallows them, the impact adds up quickly:
- Disallowed deductions: $40,000
- Additional tax at 24% bracket: about $9,600
- Accuracy penalty at 20%: about $1,920
- Interest charges: additional amount over time
With proper records, that same investor could keep every deduction. As a result, strong documentation could save roughly $11,500 or more. Since Tennessee has no state income tax on wages, the federal exposure is the primary concern here.
Long-Term Value of Clean Records
Beyond a single audit, organized records improve every future return. Consequently, you reduce risk year after year. High-net-worth investors especially benefit from advanced tax strategies for high earners that combine documentation with entity planning.
How Do You Respond to an IRS Notice?
Quick Answer: Read the notice carefully, note the deadline, and gather requested records. Then respond in writing with organized documentation, ideally with professional support.
An IRS notice is not a verdict. Instead, it is a request for information. Most Franklin Schedule E audit cases are handled by mail as correspondence audits. Therefore, a clear, organized response often resolves the matter quickly.
You have rights during any audit. Review them at the IRS Taxpayer Bill of Rights page. In addition, the Nolo legal audit resource explains taxpayer options in plain language. For personalized guidance, consider ongoing tax advisory support.
Step-by-Step Response Process
Follow these steps when a notice arrives:
- Confirm the notice deadline immediately
- Identify exactly which items the IRS questions
- Assemble supporting records in order
- Write a clear cover letter referencing each item
- Send copies, never originals, and keep proof of mailing
When to Hire a Professional
Simple notices may be handled alone. However, complex issues call for expert help. A CPA or enrolled agent can represent you before the IRS. Furthermore, professional representation often improves outcomes and reduces stress. Consider help when large dollar amounts or depreciation disputes arise.
Pro Tip: Never ignore an IRS notice. Missing a deadline can trigger automatic assessment of the full disputed amount.
Uncle Kam in Action: A Franklin Rental Investor Faces Review
Here is a hypothetical example of how this works in practice.
The Scenario: A self-employed real estate investor in Franklin owns three rental homes. She reports rental income on Schedule E and claims $52,000 in combined deductions for 2026. Her return shows a rental loss for the third year in a row.
The Challenge: The IRS flags her return due to recurring losses and large deductions relative to rent. She receives a correspondence audit notice. Consequently, she must prove her repairs, mileage, and depreciation claims.
How Uncle Kam Would Approach It: First, we would organize her records by property. Next, we would reconcile bank deposits against reported rent. Then, we would rebuild her depreciation schedule from closing documents. Furthermore, we would separate capital improvements from repairs, since misclassification is a common error.
Illustrative Numbers: Suppose the IRS initially questioned $52,000 in deductions. Without records, she could owe about $12,480 in tax at a 24% bracket. Add a 20% accuracy penalty of roughly $2,496, plus interest. With organized documentation, she could defend nearly all deductions. Therefore, she could save roughly $14,900 in tax and penalties combined.
This estimate uses 2026 rules and assumes strong recordkeeping. Every situation differs, so results vary. You can review real outcomes on our client results and case studies page. Moreover, proactive entity structuring for investors often reduces future audit risk.
Next Steps
Protect your rental income with these action items. A little preparation now prevents major stress later. Consider connecting with a Tennessee tax preparation team to review your Schedule E.
- Organize rental records by property today
- Reconcile bank deposits against reported rent
- Rebuild depreciation schedules from closing files
- Schedule a review with a proactive tax strategy team
This information is current as of 9/28/2026. Tax laws change frequently. Verify updates with the IRS if reading this later.
Related Resources
- Real Estate Investor Tax Services
- Tax Preparation and Filing Help
- Uncle Kam Tax Guides Library
- Free Tax Calculators
Frequently Asked Questions
What triggers a Franklin Schedule E audit?
Recurring rental losses, high deductions, and mismatched income reports are common triggers. In addition, income over $1 million carries a 2.5% audit rate for 2026. Clean records reduce your risk.
How long should I keep rental records?
Keep most records for at least three years after filing. However, keep property basis and depreciation records much longer. These documents matter until you sell the property.
Does Tennessee tax my rental income?
Tennessee does not levy a state income tax on wage income. Therefore, your main concern is federal reporting on Schedule E. Still, follow all federal rules carefully.
Can I deduct rental losses each year?
You can deduct up to $25,000 in rental losses under passive activity rules. However, this benefit phases out between $100,000 and $150,000 of modified adjusted gross income. Material participation matters.
Do I need a CPA for a Schedule E audit?
Simple notices may not require help. Nevertheless, complex depreciation or large dollar disputes justify professional representation. A CPA or enrolled agent can represent you before the IRS.
What happens if I ignore an IRS audit notice?
Ignoring a notice can trigger automatic assessment of the disputed amount. As a result, you may owe full tax plus penalties and interest. Always respond by the deadline.
Last updated: September, 2026