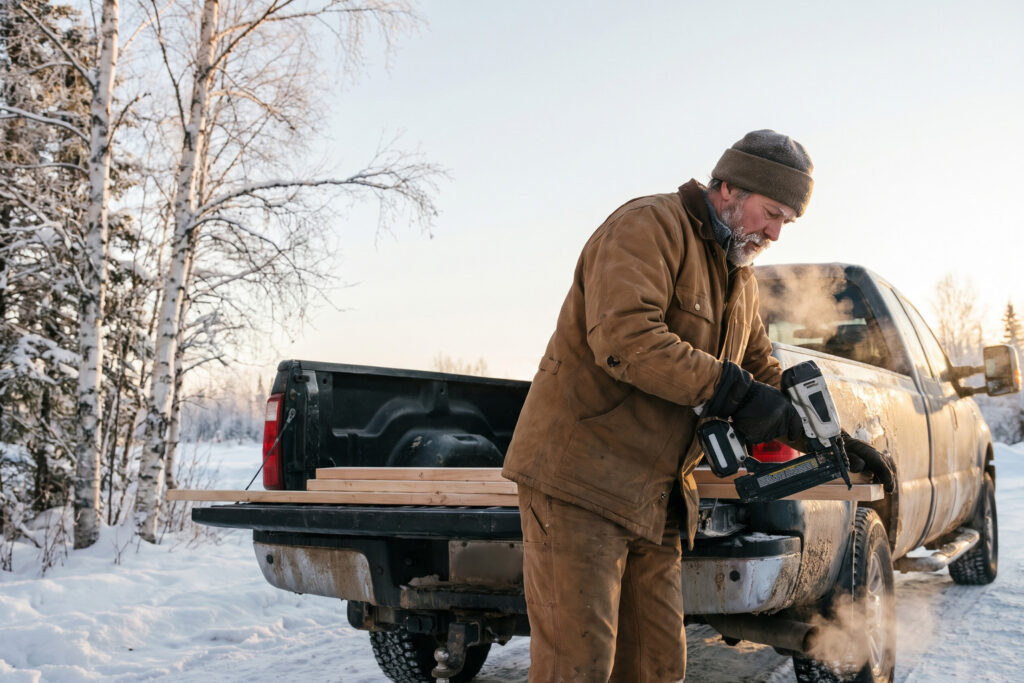
Fairbanks Business Tax Deductions: The 2026 Owner’s Guide
Fairbanks business tax deductions work differently than they do in most states, and Fairbanks tax preparation should reflect that. Alaska levies no individual income tax, so every write-off you claim is fighting a purely federal bill. For the 2026 tax year, several limits moved. Section 179 rose. Mileage rates split mid-year. The excess business loss cap dropped sharply. This guide walks Golden Heart City owners through each one.
Table of Contents
- Key Takeaways
- What Business Expenses Can Fairbanks Owners Deduct in 2026?
- How Does Alaska’s No Income Tax Change Your Deduction Strategy?
- How Much Equipment Can You Write Off Under Section 179?
- How Do You Deduct Vehicle and Home Office Costs?
- Why Does the 2026 Excess Business Loss Limit Matter?
- What Records Do Fairbanks Businesses Need to Survive an Audit?
- Uncle Kam in Action: The Fairbanks Contractor
- Related Resources
- Next Steps
- Frequently Asked Questions
Key Takeaways
- Alaska has no individual income tax, so deductions only reduce your federal bill.
- For 2026, Section 179 expensing tops out at $2,560,000, phasing down above $4,090,000.
- The IRS set two 2026 business mileage rates: 72.5 cents, then 76 cents.
- The excess business loss cap fell to $256,000 single and $512,000 joint.
- Documentation, not creativity, protects Fairbanks business tax deductions in an exam.
What Business Expenses Can Fairbanks Owners Deduct in 2026?
Quick Answer: Fairbanks businesses deduct ordinary and necessary costs. That includes equipment, vehicles, home office space, insurance, supplies, wages, and retirement contributions.
The federal standard for every deduction starts in one place. Under Internal Revenue Code Section 162, an expense must be both ordinary and necessary for your trade or business. The IRS explains this test plainly in its guidance on deducting business expenses. Ordinary means common in your industry. Necessary means helpful and appropriate. Neither word means extravagant, and neither word means you get a free pass on records.
Fairbanks adds a practical wrinkle, however. Costs that look unusual elsewhere look entirely ordinary here. Engine block heaters, extra insulation on a shop, winter tire sets, and heating fuel for a commercial space all pass the ordinary test when the business genuinely uses them. Therefore, local owners often underclaim simply because national checklists never mention Interior Alaska conditions.
Core Deduction Categories for Schedule C Filers
Most sole proprietors and single-member LLCs in Fairbanks report on Schedule C. Consequently, the form itself works as a deduction checklist. Walk the lines, and you catch categories memory alone would miss.
- Advertising, website hosting, and local sponsorships
- Contract labor paid to subcontractors issued Form 1099-NEC
- Commercial insurance, including liability and business property coverage
- Legal and professional fees, including bookkeeping and tax preparation
- Rent on shop space, storage units, and leased equipment
- Repairs, maintenance, supplies, and small tools
- Utilities, including heating fuel for business premises
- Business licenses, permits, and professional dues
Deductions That Sit Off the Schedule C
Several valuable write-offs never appear on Schedule C at all. Instead, they land on Schedule 1 of Form 1040. Owners who stop reading at the bottom of Schedule C routinely leave these on the table. Furthermore, these items reduce adjusted gross income directly, which can help you qualify for other benefits.
- One half of self-employment tax
- Self-employed health insurance premiums
- Contributions to a SEP IRA, SIMPLE IRA, or solo 401(k)
- Health savings account contributions, if you carry a qualifying plan
Retirement plan selection deserves particular attention for profitable owners. The right plan can absorb a large share of a strong year. Our breakdown of which retirement plan maximizes the deduction for self-employed owners in 2026 compares the structures side by side. Many self-employed contractors and freelancers discover thousands in missed deferrals there.
Pro Tip: Print a blank Schedule C each December. Walk every line against your books. Most owners find two or three forgotten categories.
How Does Alaska’s No Income Tax Change Your Deduction Strategy?
Quick Answer: Alaska imposes no individual income tax. Therefore, each deduction saves only the federal rate, which makes timing and self-employment tax planning far more important.
In most states, a $10,000 deduction cuts two bills at once. In Alaska, it cuts one. There is no state individual income tax on wages or business profits, a point the Alaska Department of Revenue reflects across its Tax Division program pages. As a result, your marginal federal rate alone determines what a deduction is worth to you personally.
That single-layer math changes priorities. Deductions that also reduce self-employment tax become unusually valuable. Self-employment tax runs on net Schedule C profit, so a legitimate business expense reduces both income tax and the 15.3% layer. Conversely, deductions that only shift federal taxable income deliver less punch here than they would in a high-tax state.
What the Higher Standard Deduction Means Locally
For 2026, the standard deduction rises to $16,100 for single filers and $32,200 for married couples filing jointly, according to the IRS inflation adjustments reported in October 2025. Business deductions are separate from that figure, which confuses many owners. You claim business expenses on Schedule C regardless of whether you itemize.
Fairbanks itemizers face another quirk. The state and local tax deduction cap rose to $40,000 for 2026. However, without a state income tax, most Alaskans only have property taxes to stack against that cap. Fairbanks North Star Borough property tax on a business-owned building counts, though business property taxes are generally deducted on Schedule C instead. Owners of rental and investment property should coordinate both schedules carefully.
Local Taxes Still Exist, Even Without a State Income Tax
Alaska leaves most consumption and property taxation to local governments. Consequently, Fairbanks businesses still pay deductible local costs. Borough property tax on business real estate, city levies on certain lodging and alcohol sales, and business license fees all reduce federal taxable income when they relate to your trade.
- Alaska business license fees paid to the state
- Professional licensing and continuing education required for your field
- Fairbanks North Star Borough property tax on commercial parcels
- Local permit and inspection fees tied to operations
Rates and applicability vary by jurisdiction within the borough. Therefore, verify your specific obligations directly with the Fairbanks North Star Borough before assuming a levy applies. A conversation with a local professional who handles tax preparation near me in Alaska saves guesswork during filing season.
Did You Know? Alaska does levy a corporate income tax on C corporations. Pass-through owners, however, face only the federal layer personally.
How Much Equipment Can You Write Off Under Section 179?
Quick Answer: For tax years beginning in 2026, Section 179 expensing reaches $2,560,000. The benefit phases down once qualifying purchases exceed $4,090,000.
Equipment-heavy Fairbanks businesses live and die by depreciation timing. Under Revenue Procedure 2025-32, the 2026 Section 179 limit is $2,560,000, with the phase-down threshold at $4,090,000 and a $32,000 cap on certain sport utility vehicles. The IRS lays out the underlying mechanics in Publication 946, How To Depreciate Property. Few local shops approach the ceiling, so the practical constraint is usually something else entirely.
That constraint is the business income limitation. Section 179 cannot create a loss. If your Fairbanks excavation company buys a $180,000 machine but reports only $90,000 of net income, your current Section 179 deduction stops at $90,000. The remainder carries forward. Bonus depreciation, by contrast, carries no such restriction and can push a business into a loss.
2026 Depreciation Figures at a Glance
| Provision | 2026 Figure | Practical Note |
|---|---|---|
| Section 179 maximum | $2,560,000 | Limited by business income |
| Section 179 phase-down begins | $4,090,000 | Dollar-for-dollar reduction |
| Heavy SUV Section 179 cap | $32,000 | Applies to certain SUVs |
| Bonus depreciation rate | 100% | Qualifying property acquired after Jan. 19, 2025 |
| De minimis safe harbor | $2,500 per item | Requires a written policy and election |
A Worked Fairbanks Example
Picture a Fairbanks welding shop with $240,000 of net profit before depreciation. In September 2026, the owner buys a $95,000 CNC plasma table and places it in service the same month. Section 179 covers the full $95,000 because profit exceeds the purchase. Net profit drops to $145,000.
The savings arrive in two layers. First, $95,000 escapes federal income tax at the owner’s marginal rate. Second, the same $95,000 reduces net earnings subject to self-employment tax. Assuming a 22% marginal rate and the full 15.3% self-employment layer on that slice, combined savings could approach $30,000. However, the QBI deduction shrinks alongside profit, which trims the net benefit. That interaction is exactly why modeling beats guessing.
Fairbanks owners weighing a December equipment purchase can run preliminary numbers with our Small Business Tax Calculator for Fairbanks before committing capital for 2026.
Pro Tip: Placed in service, not purchased, controls the deduction year. A machine sitting crated on December 31 does not qualify.
How Do You Deduct Vehicle and Home Office Costs?
Quick Answer: Use mileage or actual costs for vehicles. For 2026, the IRS set two business rates: 72.5 cents through June 30 and 76 cents afterward.
Vehicles dominate deductions for Interior Alaska service businesses. Distances are long, job sites are spread out, and winter driving costs real money. The IRS publishes both methods on its standard mileage rates page. Notably, 2026 brought an unusual mid-year change, so your log must separate miles driven in each half of the year.
Mileage Versus Actual Expenses
The standard mileage method is simpler and covers fuel, maintenance, insurance, and depreciation in one rate. The actual expense method tracks every cost, then applies your business-use percentage. For Fairbanks owners, actual expenses often win. Heating-related maintenance, block heaters, studded tires, and higher fuel costs push real spending above the national average the rate assumes.
| Factor | Standard Mileage | Actual Expenses |
|---|---|---|
| 2026 rate | 72.5¢ Jan–Jun; 76¢ Jul–Dec | Business-use share of real costs |
| Recordkeeping | Mileage log only | Receipts plus mileage log |
| Best for | Efficient, high-mileage vehicles | Heavy trucks and harsh conditions |
| Depreciation | Built into the rate | Claimed separately |
One rule traps new owners. Commuting from home to a regular workplace never qualifies. Driving from a qualifying home office to a job site, however, generally does. That distinction alone makes the home office deduction worth evaluating for Fairbanks tradespeople.
The Home Office Deduction in a Cold Climate
Two methods exist. The simplified option pays $5 per square foot of qualifying space, capped at 300 square feet, for a maximum of $1,500. The regular method applies your business-use percentage to actual housing costs, reported on Form 8829. The IRS compares both on its home office deduction page.
Fairbanks heating costs frequently make the regular method superior. Consider a 1,800 square foot home with a 270 square foot dedicated office, giving 15% business use. If annual heating fuel, electricity, insurance, and mortgage interest total $24,000, the business share reaches $3,600 before depreciation. That more than doubles the $1,350 simplified result.
Exclusive and regular use remains the gatekeeper, though. A desk in the living room fails. A converted spare bedroom used only for business passes. Owners juggling a W-2 job alongside side income should also review what W-2 earners with freelance income can deduct in 2026, because the rules differ by income source.
Why Does the 2026 Excess Business Loss Limit Matter?
 Free Tax Write-Off Finder
Quick Answer: For 2026, business losses offset other income only up to $256,000, or $512,000 jointly. That is down sharply from 2025.
This is the most consequential 2026 change for aggressive deduction planners. A Fairbanks CPA firm summarized the rule clearly: for 2026, the deduction limit for eligible business losses is $256,000, or $512,000 for married couples filing jointly, down from $313,000 and $626,000 respectively for 2025. The 2026 amounts will be adjusted for inflation starting in 2027.
Crucially, the limit applies per taxpayer, not per business. If you own three Fairbanks ventures, the calculation combines them. Moreover, the excess business loss rule sits last in a sequence. Basis, at-risk, and passive activity loss rules apply first. Only a loss surviving all three hits this final cap.
How the Loss Sequence Works
- Basis limitation reduces the loss to your investment in the entity.
- At-risk rules reduce it further for non-recourse financing.
- Passive activity rules suspend losses without material participation.
- The excess business loss limit caps what remains.
Real estate owners in particular should understand step two. Our guide to how at-risk rules affect real estate investors in 2026 explains why a financed property may not deliver the loss you expected.
The Disallowed Loss Is Not Lost
Here is the reassuring part. An excess business loss converts into a net operating loss carryforward. The same Fairbanks firm illustrated it with a $600,000 loss: a single filer could deduct $256,000 currently, while the remaining $344,000 becomes an NOL carryover usable in future years, subject to applicable rules and limits.
| Filing Status | 2025 Limit | 2026 Limit |
|---|---|---|
| Single | $313,000 | $256,000 |
| Married filing jointly | $626,000 | $512,000 |
The timing cost is real, nonetheless. Deferring a deduction several years erodes its present value. Therefore, owners anticipating a large 2026 loss should model whether to accelerate income or delay deductible purchases into 2027. Thoughtful proactive tax strategy turns this limitation into a scheduling question rather than a surprise.
What Records Do Fairbanks Businesses Need to Survive an Audit?
Quick Answer: Keep contemporaneous records showing amount, date, business purpose, and participants. Reconstructed records rarely hold up under examination.
Deductions fail on documentation far more often than on legal theory. The IRS explains expectations in its recordkeeping guidance for small businesses. Contemporaneous matters most. A log built in March for the prior year carries far less weight than entries made weekly throughout the year.
Documentation by Deduction Type
| Deduction | Required Proof |
|---|---|
| Vehicle mileage | Date, destination, purpose, miles, split by half-year |
| Home office | Measurements, photos, utility and mortgage statements |
| Equipment | Invoice, payment proof, placed-in-service date |
| Meals | Receipt, attendees, business topic discussed |
| Contract labor | Form W-9, Form 1099-NEC, signed agreement |
Three Mistakes Local Owners Repeat
- Mixing personal and business spending in one bank account
- Deducting a snowmachine or boat with no documented business use
- Skipping Form 1099-NEC for subcontractors paid over $600
Separate accounts solve most of this immediately. A dedicated business checking account and card create a clean audit trail without extra effort. Meanwhile, entity structure can reduce exposure further. Owners approaching six-figure profits should evaluate whether S corporation entity structuring fits their situation. Working with a professional who handles business tax filing in Fairbanks keeps that analysis grounded in your actual numbers.
Did You Know? The IRS generally expects records kept at least three years after filing. Property records should survive far longer.

Uncle Kam in Action: The Fairbanks Contractor
Here is a hypothetical example of how this works in practice.
The Scenario: Imagine a general contractor operating a single-member LLC in Fairbanks. The business generates $185,000 in net profit for 2026. The owner drives a three-quarter-ton truck roughly 21,000 business miles annually across the borough and out to Delta Junction. A spare bedroom functions as a dedicated office for estimates and scheduling.
The Challenge: The owner claims obvious costs like materials and insurance. However, mileage goes untracked. The home office is never claimed. A December equipment purchase gets delayed to January without analysis. Self-employment tax consumes a large share of profit, and no retirement plan exists.
How Uncle Kam Would Approach It: First, we would install a mileage app that separates miles before and after June 30, matching the two 2026 rates. Second, we would document the office and run both calculation methods. Third, we would time a planned equipment purchase so it is placed in service before December 31. Finally, we would evaluate a solo 401(k) and an S corporation election.
Illustrative Numbers: Suppose 11,000 miles fall in the first half and 10,000 in the second. At 72.5 cents and 76 cents respectively, mileage alone could produce roughly $15,575 in deductions. A regular-method home office might add $3,200. A $40,000 equipment purchase expensed under Section 179 could add more. Combined, these moves could reduce taxable profit by well over $58,000. At a 22% marginal rate plus self-employment tax on the Schedule C portion, the owner could save roughly $17,000 to $19,000 for 2026.
These figures are estimates only. Actual outcomes depend on facts, documentation, and entity structure. You can review documented outcomes on our client results page.
Related Resources
- Tax planning built for business owners
- Business tax preparation and filing services
- Free tax calculators for business owners
- Key filing deadlines and tax calendar
- More strategy articles on the Uncle Kam blog
Before you act on any single deduction, step back and look at the full year. Deduction decisions interact with each other, with your entity choice, and with the new loss limits. A short planning conversation with a team that understands tax preparation across Alaska often reveals more savings than any single write-off.
Next Steps
- Open a dedicated business bank account before January 1, 2027.
- Reconstruct 2026 mileage now, splitting miles at June 30.
- Decide on equipment purchases before the December 31 placed-in-service deadline.
- Model whether a 2026 loss will hit the $256,000 excess business loss cap.
- Schedule a review with our tax advisory team before filing season.
Frequently Asked Questions
Does Alaska tax my business profits?
Alaska imposes no individual income tax on wages or pass-through business profits. Therefore, sole proprietors, partners, and S corporation shareholders in Fairbanks face only federal income tax and self-employment tax on business earnings. C corporations are different, because Alaska does levy a corporate income tax. Local property and excise taxes may still apply depending on your location and industry.
Can I deduct heating fuel for my Fairbanks shop?
Yes. Heating fuel for a commercial space is a deductible utility expense when the space is used for business. If the building serves both personal and business purposes, allocate costs by business-use percentage. Keep delivery invoices and payment records. For a home office, heating fuel flows through the regular method on Form 8829 rather than as a separate Schedule C line item.
How do the two 2026 mileage rates work together?
The IRS set 72.5 cents per business mile for January 1 through June 30, 2026, then 76 cents for July 1 through December 31. Consequently, you must track which miles fall in each period. Calculate each half separately, then add the results. A mileage app with date stamps handles this automatically and produces better audit documentation than a handwritten notebook.
What happens if my business loss exceeds the 2026 limit?
The excess becomes a net operating loss carryforward. For 2026, you may offset other income with business losses only up to $256,000 single or $512,000 joint. Anything above that converts to an NOL usable in later years, subject to separate NOL rules. You do not permanently lose the deduction. However, you lose the current-year benefit and the time value that goes with it.
Is Section 179 better than bonus depreciation in 2026?
It depends on your profit. Section 179 lets you choose asset by asset and amount by amount, but it cannot create a loss. Bonus depreciation runs at 100% for qualifying property and can create a loss, though it applies to an entire class of property unless you elect out. Profitable Fairbanks businesses often prefer Section 179 for precision. Businesses expecting a strong future year sometimes prefer slower depreciation instead.
Should I elect S corporation status to increase my deductions?
An S corporation election does not add deductions. Instead, it can reduce self-employment tax by splitting profit between reasonable wages and distributions. That matters in Alaska, where self-employment tax is a large share of the total bill. Nevertheless, the election brings payroll costs, filing requirements, and reasonable compensation scrutiny. Model the numbers before electing, because low-profit businesses often lose money on the switch.
When is the deadline to make 2026 deduction decisions?
Most decisions close on December 31, 2026. Equipment must be placed in service by then. Expenses must be paid or incurred by then under your accounting method. A few choices extend into 2027, including SEP IRA contributions, which can be made up to the extended due date of your return. Act in December rather than April for the broadest set of options.
This information is current as of 11/18/2026. Tax laws change frequently. Verify updates with the IRS or the Alaska Department of Revenue if reading this later. Figures cited reflect 2026 inflation adjustments and should be confirmed against final IRS instructions before filing.
Last updated: November, 2026

