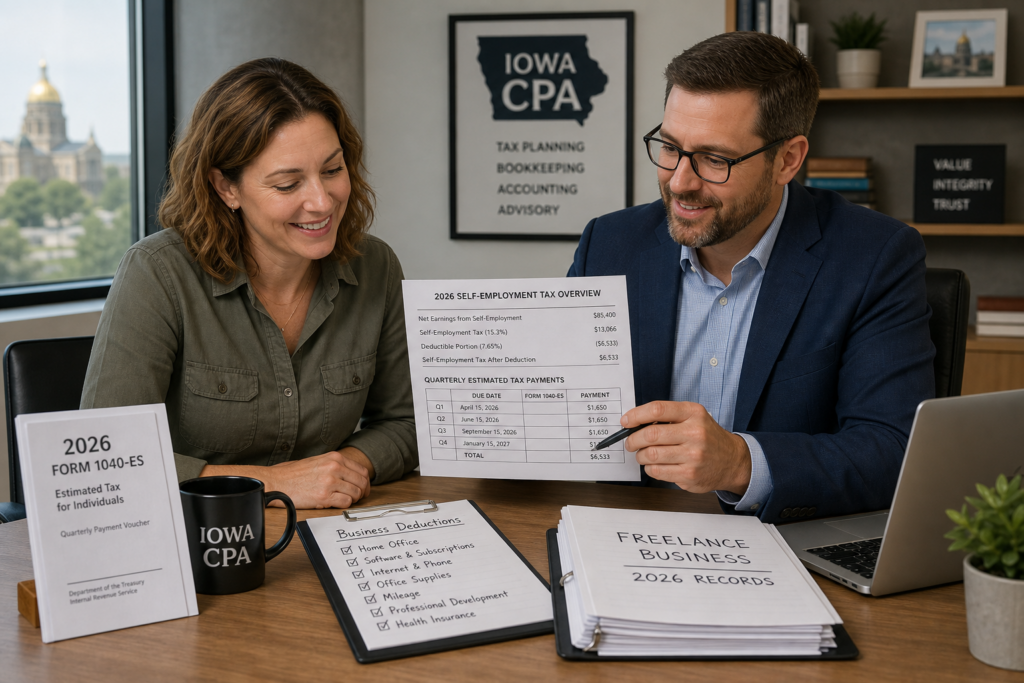
How an Iowa CPA Can Help You Master Self-Employment Taxes for 2026
How an Iowa CPA Can Help You Master Self-Employment Taxes for 2026
Self-employed professionals across Iowa face a unique tax challenge that many underestimate. Unlike traditional employees, self-employed individuals working with an Iowa CPA must manage both income tax and self-employment tax obligations simultaneously. For the 2026 tax year, understanding these requirements—and leveraging professional guidance—can mean the difference between owing thousands in taxes at year-end and proactively planning a manageable payment strategy. This guide explores how an experienced Iowa CPA helps freelancers, contractors, and business owners navigate complex self-employment tax rules while identifying legitimate deductions and optimization opportunities.
Table of Contents
- Key Takeaways
- What Is Self-Employment Tax and Why Does It Matter?
- Understanding Quarterly Estimated Tax Payments for 2026
- How Much Self-Employment Tax Will You Owe in 2026?
- How to Maximize Self-Employment Deductions and Lower Your Tax Bill
- Iowa-Specific Tax Considerations for Self-Employed Professionals
- Why Work With an Iowa CPA for Your Self-Employment Taxes?
- Next Steps
- Frequently Asked Questions
Key Takeaways
- Self-employment tax in 2026 is 15.3%, consisting of 12.4% for Social Security and 2.9% for Medicare on net earnings.
- Quarterly estimated tax payments are due June 15, September 15, and December 15, 2026 to avoid penalties.
- An Iowa CPA helps identify deductions you might miss, potentially saving thousands annually on self-employment taxes.
- Iowa has its own state income tax requirements that interact with federal self-employment obligations.
- Professional tax planning throughout the year beats scrambling to file during tax season and prevents underpayment penalties.
What Is Self-Employment Tax and Why Does It Matter?
Quick Answer: Self-employment tax covers Social Security and Medicare contributions that self-employed individuals must pay. Unlike employees who split these costs with employers, you pay the full amount—currently 15.3% of net self-employment income for the 2026 tax year.
When you work as a freelancer, consultant, or independent contractor, the IRS requires you to pay self-employment tax on top of regular income tax. This obligation is separate from—and in addition to—federal income tax. For many self-employed individuals in Iowa, self-employment tax represents a shock that significantly increases their total tax bill if they haven’t planned ahead with an Iowa CPA.
Self-employment tax funds Social Security and Medicare programs. The 2026 rate breaks down as follows: 12.4% goes toward Social Security (with an earnings cap of approximately $168,600) and 2.9% toward Medicare (with no earnings cap). You calculate this tax on Schedule SE, a form that accompanies your main tax return.
How Self-Employment Tax Differs From Income Tax
Many self-employed professionals confuse self-employment tax with income tax. They are distinct obligations. Income tax is based on your total taxable income and is subject to standard deductions (single filers get $14,600 for 2026). Self-employment tax applies directly to your net business profits before standard deduction calculations. An experienced Iowa CPA ensures you understand both obligations and don’t underpay on either front.
Why Self-Employed Individuals Often Underestimate This Obligation
Self-employed professionals frequently assume their income tax refund or small tax bill represents their entire tax situation. However, self-employment tax can easily exceed $3,000 to $5,000 annually on modest business income. Without quarterly planning, this creates an unwelcome surprise when filing taxes. Working with an Iowa CPA throughout the year prevents this shock by tracking self-employment tax liability quarterly.
Understanding Quarterly Estimated Tax Payments for 2026
Quick Answer: Estimated tax payments are quarterly advance payments covering both income tax and self-employment tax. For 2026, deadlines fall on June 15, September 15, and December 15. The April 15 deadline already passed earlier this year.
Unlike traditional employees who have taxes withheld from paychecks, self-employed individuals must remit estimated taxes throughout the year using Form 1040-ES. The IRS requires you to pay estimated tax if you expect to owe more than $1,000 in taxes for the year. Missing these deadlines results in underpayment penalties, even if you ultimately owe less than expected.
2026 Estimated Tax Payment Deadlines and Amounts
For the 2026 tax year, you need to plan for estimated payments on these dates. Each quarter typically represents one-fourth of your annual tax liability, though the amounts may vary based on income fluctuations. Working with an Iowa CPA helps ensure you calculate accurate amounts to avoid both underpayment penalties and overpayment carry-forwards.
| Quarter | Income Period | Payment Due Date |
|---|---|---|
| Q1 | January – March 2026 | April 15, 2026 (already passed) |
| Q2 | April – June 2026 | June 15, 2026 |
| Q3 | July – September 2026 | September 15, 2026 |
| Q4 | October – December 2026 | December 15, 2026 |
Calculating Your Estimated Tax Payment
Calculating estimated taxes involves projecting your full-year income, subtracting allowable deductions, then applying both income tax and self-employment tax rates. An Iowa CPA adjusts estimates as your business income changes throughout the year. This prevents overpayment if business slows down or adjusts for higher payments if growth accelerates.
Pro Tip: Request Safe Harbor relief from underpayment penalties by paying either 90% of 2026 tax liability or 100% of 2025 tax liability. An Iowa CPA ensures you meet these thresholds to avoid IRS penalties.
How Much Self-Employment Tax Will You Owe in 2026?
Quick Answer: For every dollar of net self-employment income, you owe approximately 15.3% in self-employment tax (after adjustments). Use our Self-Employment Tax Calculator to estimate your 2026 liability based on your projected income.
Understanding your potential self-employment tax liability is critical for budgeting and quarterly payment planning. Consider a freelance consultant in Iowa earning $75,000 in net self-employment income. On this amount, self-employment tax would be approximately $10,605 for 2026 (though actual calculations account for specific adjustments). This substantial obligation requires proactive planning throughout the year.
Factors That Affect Your Self-Employment Tax Bill
Several factors influence your self-employment tax. First, only 92.35% of net earnings count toward self-employment tax—the remaining 7.65% accounts for an employee-side tax deduction. Second, Social Security tax has an earnings cap (roughly $168,600 for 2026), above which no Social Security tax applies. High-income self-employed individuals benefit from this cap, while mid-range earners do not. An Iowa CPA tracks these nuances to ensure you don’t overpay.
Additionally, business expenses directly reduce net self-employment income, which directly reduces self-employment tax owed. This is where working with an Iowa CPA provides exceptional value. Every deduction you legitimately claim reduces not just income tax but also the self-employment tax base itself.
Why Your Self-Employment Tax Is Higher Than You Expect
Many self-employed individuals expect self-employment tax to equal roughly 15% of income. However, the effective rate often feels higher because most people haven’t accounted for this obligation while managing cash flow. Additionally, self-employment tax combines with income tax, creating a total tax burden that shocks unprepared business owners. Professional guidance from an Iowa CPA prevents this surprise.
How to Maximize Self-Employment Deductions and Lower Your Tax Bill
 Free Tax Write-Off Finder
Quick Answer: Deductible business expenses include office supplies, equipment, vehicle mileage, professional services, health insurance premiums, and home office costs. Each deduction reduces your net income and therefore your self-employment tax liability directly.
One of the most powerful benefits of working with an Iowa CPA is identifying deductions you might overlook on your own. Self-employed individuals often leave hundreds or thousands in potential tax savings on the table by not claiming legitimate business expenses. The IRS allows any expense that is both ordinary and necessary for your business. This is broad language that encompasses far more than many professionals realize.
Essential Business Deductions for Self-Employed Professionals
- Office supplies and equipment (computers, printers, software subscriptions)
- Vehicle mileage for business travel (standard mileage rate for 2026)
- Home office deduction (simplified or actual expense method)
- Health insurance premiums for self-employed individuals
- Retirement contributions (SEP-IRA or Solo 401k up to IRS limits)
- Professional memberships and licensing fees
- Continuing education and professional development courses
- Professional services (accounting, legal, consulting fees)
- Marketing and advertising expenses
- Client entertainment and meals (subject to 50% limitation)
The Home Office Deduction: A Common Missed Opportunity
Many self-employed professionals in Iowa operate from home but never claim a home office deduction. The IRS allows two methods: simplified ($5 per square foot, maximum 300 feet) or actual expenses. If you use 300 square feet of your home exclusively for business, the simplified method yields $1,500 annually. For larger home offices or those with higher utility costs, actual expense calculations may yield even more. An Iowa CPA evaluates both methods and chooses the optimal approach for your situation.
Remember, every dollar of business expense deduction reduces your net self-employment income by one dollar, which then reduces your self-employment tax obligation. This magnifies the value of thorough deduction documentation. An Iowa CPA ensures you capture every legitimate deduction available under 2026 tax law.
Iowa-Specific Tax Considerations for Self-Employed Professionals
Quick Answer: Iowa has progressive state income tax rates that apply to self-employed income. Additionally, Iowa does not have a separate self-employment tax, but self-employed income is subject to regular Iowa income tax calculations at rates ranging up to 5.7%.
Self-employed professionals in Iowa must navigate both federal and state tax obligations. While much of this guide focuses on federal self-employment tax, Iowa state income tax compounds your total tax liability. Unlike some states that exempt certain self-employed income, Iowa taxes all self-employment income according to its standard income tax brackets.
Iowa State Income Tax Rates and Self-Employment Income
Iowa applies progressive income tax rates based on your filing status and total taxable income. For 2026, Iowa’s top state income tax rate is approximately 5.7%, applied to higher-income earners. Self-employment income is fully taxable in Iowa, meaning your net business income counts toward Iowa income tax calculations. This adds to your federal income tax and self-employment tax obligations, making comprehensive tax planning essential.
An experienced Iowa CPA understands how federal deductions flow through to Iowa tax calculations. Certain deductions that apply at the federal level may be treated differently for Iowa purposes. Additionally, Iowa offers specific tax credits for small businesses and self-employed individuals that a knowledgeable CPA identifies and claims on your behalf.
Iowa Business Registration and Withholding Requirements
Depending on your business structure and income level, Iowa may require business registration with the state. Sole proprietors often operate under their personal name, while LLCs and corporations require formal registration. An Iowa CPA advises on appropriate business structure from a tax perspective. Additionally, if you hire employees, you must withhold Iowa income tax and understand Iowa-specific employment tax obligations. This complexity further underscores the value of professional guidance.
Why Work With an Iowa CPA for Your Self-Employment Taxes?
Quick Answer: An Iowa CPA provides year-round tax planning, identifies overlooked deductions, ensures compliance with federal and state requirements, minimizes tax liability, and helps you avoid costly mistakes and penalties.
Working with a qualified tax preparation professional in Iowa transforms how you manage self-employment taxes. Rather than scrambling to gather documents in March or April, a proactive CPA relationship means monthly or quarterly reviews of your business finances, ongoing tax optimization, and strategic planning throughout the year.
Year-Round Tax Planning vs. Annual Tax Filing
Many self-employed individuals treat tax work as an annual burden—meeting their CPA once yearly to file returns. A better approach involves ongoing advisory relationships where you meet quarterly to review tax results, project year-end liability, adjust estimated payments, and discuss tax-saving strategies. An Iowa CPA supporting year-round planning catches opportunities in real-time rather than discovering missed deductions months after the tax year ends.
Expertise in Complex Self-Employment Scenarios
Self-employed situations vary widely. Some professionals have multiple income streams from freelance work plus passive investment income. Others balance W-2 employment with side business income. Still others run formal business entities. An experienced Iowa CPA understands how these different income sources interact, how to allocate expenses properly, and how to structure your business optimally for tax purposes. This expertise directly translates to tax savings that far exceed CPA fees.
Pro Tip: Many Iowa CPAs offer fixed quarterly advisory fees that cost less than the tax savings they identify. View professional guidance as an investment, not an expense.
Risk Mitigation and Audit Protection
The IRS scrutinizes self-employed income more closely than W-2 wages. An experienced Iowa CPA ensures your returns are prepared correctly, documented thoroughly, and defensible under audit. Should the IRS question specific deductions or calculations, your CPA representation during audit proceedings provides valuable expertise and protection. This alone justifies the investment in professional guidance.

Uncle Kam in Action: How Professional Tax Planning Saved an Iowa Freelancer $4,200
Meet Sarah, a graphic designer operating as a sole proprietor in Des Moines, Iowa. In 2025, Sarah earned $68,000 in freelance design work and made four estimated tax payments totaling $14,000. When tax time came, she expected a small refund or modest balance due. Instead, she discovered she underpaid by $2,800 and faced a small penalty.
Sarah engaged Uncle Kam—a local Iowa CPA firm specializing in self-employed professionals—for 2026 planning. During their January meeting, the CPA reviewed Sarah’s 2025 returns and noticed several missed deductions: a home office she’d operated but never claimed (worth $1,200 in deductions), professional software subscriptions totaling $1,500 annually that she’d considered personal expenses, and vehicle mileage from client meetings (approximately $1,800 in deductions) that she’d tracked but never claimed.
Additionally, the CPA structured a Solo 401(k) retirement plan, allowing Sarah to reduce her 2026 self-employment tax through contributions up to IRS limits. For 2026, with projected income of $72,000, the CPA recommended quarterly estimated payments of $4,100 instead of the prior-year’s $3,500, preventing another underpayment situation.
By engaging professional guidance, Sarah achieved multiple benefits: First, the 2025 analysis revealed $4,500 in missed deductions. Second, 2026 planning prevented another underpayment penalty. Third, the Solo 401(k) structure created retirement savings while reducing 2026 tax liability by approximately $2,800 through contribution deductions. Fourth, quarterly check-ins throughout 2026 ensured ongoing optimization.
The total value? By year-end 2026, Sarah had legitimate tax savings exceeding $4,200, plus a properly-funded retirement vehicle and confidence in her tax compliance. The cost of professional guidance was entirely offset by identified savings and prevented penalties.
Next Steps
If you’re self-employed in Iowa and managing 2026 taxes without professional guidance, now is the ideal time to establish a relationship with a qualified CPA. Here’s how to move forward:
- Schedule a Consultation: Meet with an experienced Iowa tax professional to review your 2026 situation, discuss estimated tax needs, and identify missed deductions.
- Gather Financial Documents: Compile your business income statements, expense receipts, and prior-year tax returns. This provides your Iowa CPA with the information needed for accurate quarterly planning.
- Establish Quarterly Meetings: Commit to monthly or quarterly reviews with your CPA. These touchpoints ensure optimal tax planning and prevent year-end surprises.
- Implement Deduction Tracking: Work with your CPA to establish systems for documenting business expenses throughout the year, making deduction claiming easier at year-end.
- Review Business Structure: Discuss whether your current business setup (sole proprietor, LLC, or corporation) optimizes your tax position, and consider changes for 2027 if beneficial.
Frequently Asked Questions
At what income level do I need to pay self-employment tax in 2026?
You must pay self-employment tax on any net self-employment income of $400 or more. Even if you owe no federal income tax (because deductions reduce your taxable income below the standard deduction), you still owe self-employment tax on income exceeding $400. An Iowa CPA ensures you understand this requirement and file Schedule SE correctly.
Can I deduct business losses against other income as a self-employed person?
Yes, you can deduct business losses on Schedule C, which flows through to reduce your overall taxable income. If your business produces a net loss, that loss reduces income from other sources (like W-2 wages if you have a day job). However, losses are limited in certain situations (passive activity rules, excess business loss limitations). An Iowa CPA navigates these rules to maximize the benefit of business losses while maintaining IRS compliance.
What if I have both W-2 employment income and self-employment income in 2026?
This is a complex situation requiring careful estimated tax planning. W-2 withholding may cover some federal tax, but you likely owe additional self-employment tax on your business income. Your Iowa CPA coordinates W-2 withholding with self-employment tax payments to ensure neither overpayment nor underpayment penalties occur. Additionally, the interaction of both income sources affects your overall tax bracket and any applicable credits.
Is incorporating my business better than remaining a sole proprietor for 2026 tax purposes?
This depends on your specific circumstances. S-Corporations and C-Corporations offer different tax treatments. S-Corps may reduce self-employment tax through reasonable salary and distribution strategies, potentially saving thousands annually for high-income earners. However, incorporation creates additional compliance costs and complexity. An Iowa CPA evaluates your income, expenses, and growth plans to recommend the optimal business structure for maximum tax efficiency.
What retirement options are available for self-employed individuals in 2026?
Self-employed individuals can establish SEP-IRAs, Solo 401(k)s, or Simple IRAs. For 2026, traditional IRAs allow contributions of up to $7,500 (if over age 50). Solo 401(k)s offer higher limits through employer contributions. These retirement vehicles reduce your current-year self-employment and income tax while building retirement savings. An Iowa CPA helps you select the plan that maximizes your contribution capacity and tax savings.
What expenses can I never deduct as self-employed?
Certain expenses are never deductible, regardless of self-employment status. Personal expenses (clothing, commuting to a regular workplace, personal hygiene) are not deductible. Meals and entertainment are only 50% deductible. Penalties and fines paid to government agencies are generally non-deductible. Additionally, capital improvements to your home (new roof, foundation repairs) are capitalized rather than deducted, though depreciation may apply. An Iowa CPA advises on proper classification of gray-area expenses.
Do I need to file quarterly estimated taxes if my business is just starting in 2026?
If you begin a business mid-year and expect to owe more than $1,000 in total tax for the year, estimated taxes apply. Some new business owners underestimate their tax liability, then face underpayment penalties. An Iowa CPA helps new entrepreneurs project realistic income, file estimated taxes only when necessary, and avoid penalties. Additionally, Safe Harbor provisions sometimes protect new business owners from underpayment penalties in their first year.
Can I claim a home office deduction if I use one room in my home for multiple purposes?
No. The home office must be used exclusively for business to qualify for the deduction. A room that doubles as a guest bedroom does not qualify. However, a dedicated office space used only for your business absolutely qualifies. An Iowa CPA helps you determine whether your home office meets IRS criteria and, if so, calculates the maximum deduction allowed.
Should I keep all business receipts for my Iowa tax return?
Yes. The IRS may request substantiation for any deduction claimed. While you typically don’t attach receipts to your tax return, you must retain them for at least three years (six years if there’s underreporting of income, indefinitely if fraud is suspected). An Iowa CPA recommends establishing organized receipt retention systems—photographing receipts, using accounting software, or digitizing documents. This preparation prevents stress if audited and ensures you can substantiate claimed deductions.
Related Resources
- Comprehensive Tax Strategy Planning for Self-Employed Professionals
- Complete Self-Employed Tax Guide and Deduction Strategies
- Business Owner Tax Planning and Optimization
- Ongoing Tax Advisory Services for Year-Round Planning
Last updated: June, 2026
This information is current as of 6/8/2026. Tax laws change frequently. Verify updates with the IRS or an Iowa CPA if reading this later in the year.

